Buying Or Selling? Call today on 0418 728 201 to organise a FREE APPRAISAL
Terminology Index
Banking & Finance
Wealth & Investment
Property Ownership
Property Development
Arrears
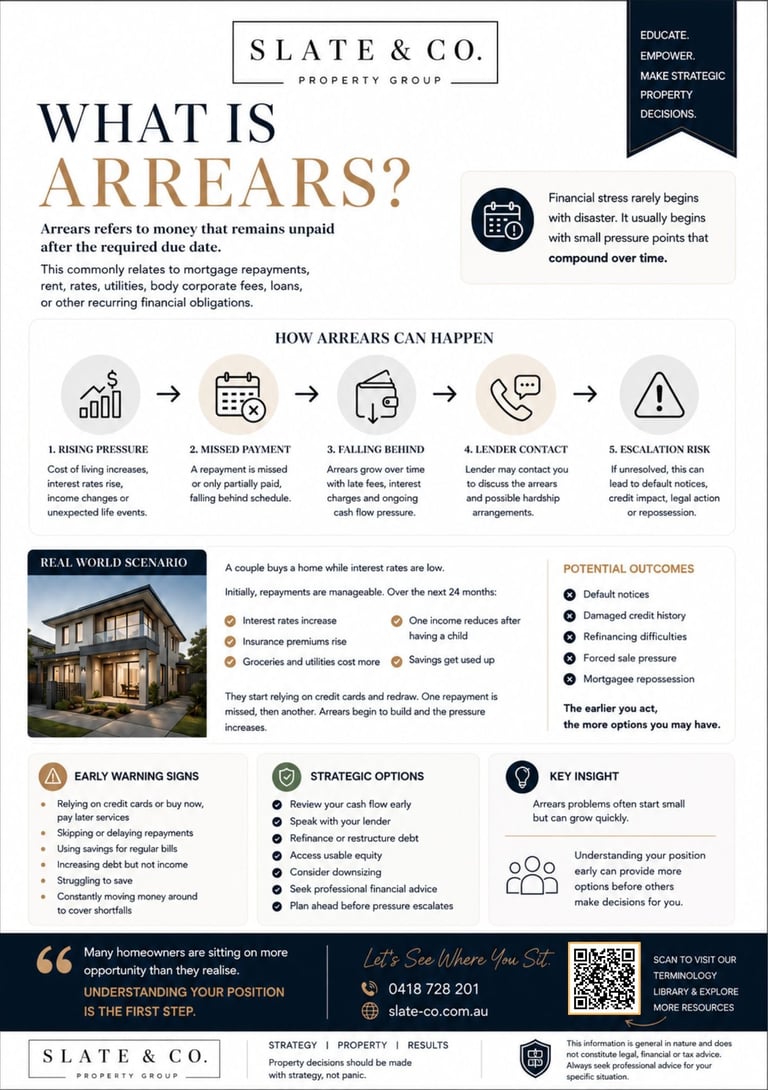
Arrears refers to money that remains unpaid after the required due date.
This commonly relates to:
mortgage repayments,
rent,
loan repayments,
utilities,
rates,
or other recurring financial obligations.
Arrears often begin with small financial pressure that compounds over time if left unresolved.
Download the full guide to understand:
how arrears situations commonly develop,
warning signs to watch for,
potential consequences,
and strategic considerations property owners should understand.

Banking & Finance
Bond Yield
Bond yield refers to the return an investor earns from holding a bond based on its interest payments and market value.
Bond yields are closely watched because they can influence:
interest rates,
borrowing costs,
lending conditions,
investor behaviour,
and broader property market activity.
Changes in bond yields can affect mortgage pricing, borrowing power, and overall market confidence.
Download the full guide to understand:
how bond yields work,
why markets monitor them closely,
and how rising or falling yields may influence property and finance decisions.


Banking & Finance
Borrowing Capacity
Borrowing capacity refers to the amount of money a lender may be willing to loan you based on your financial position.
Lenders typically assess:
income,
existing debts,
living expenses,
credit history,
loan commitments,
interest rates,
and overall financial stability.
Borrowing capacity can significantly influence:
what type of property you may be able to purchase,
investment opportunities,
refinancing options,
and long-term financial flexibility.
Changes in interest rates, living costs, lending policy, or personal income can all affect borrowing power over time.
Download the full guide to understand:
how lenders assess borrowing capacity,
common mistakes that reduce borrowing power,
real-world borrowing scenarios,
and strategic considerations buyers and homeowners should understand.


Banking & Finance
Cash Flow
Cash flow refers to the movement of money coming into and going out of a household, business, or investment over time.
Positive cash flow means more money is coming in than going out.
Negative cash flow means expenses are exceeding income, which can place financial pressure on individuals or businesses if sustained over long periods.
Cash flow can influence:
mortgage repayments,
borrowing capacity,
investment performance,
financial stability,
and long-term property decisions.
Even people with strong incomes or significant assets can experience financial stress if cash flow is poorly managed.
Download the full guide to understand:
how cash flow works in the real world,
common causes of cash flow pressure,
warning signs to watch for,
and strategic considerations property owners and investors should understand.


Banking & Finance
Cash Rate
The cash rate is the interest rate set by the Reserve Bank of Australia (RBA) that influences the cost of borrowing money throughout the Australian economy.
It plays a major role in:
mortgage interest rates,
borrowing costs,
savings rates,
consumer spending,
business activity,
and overall economic confidence.
When the cash rate rises:
borrowing generally becomes more expensive,
mortgage repayments may increase,
and borrowing power can reduce.
When the cash rate falls:
lending conditions may ease,
borrowing costs can reduce,
and spending and investment activity may increase.
Changes in the cash rate can influence:
property market activity,
buyer confidence,
investor behaviour,
and household financial pressure.
Even small movements in the cash rate can create significant flow-on effects across property and finance markets over time.
Download the full guide to understand:
how the cash rate works,
why the RBA changes it,
how it affects mortgages and borrowing power,
and the broader impact it can have on property markets, households, and the economy.


Banking & Finance
Central Bank
A central bank is the primary financial institution responsible for managing a country’s monetary system, financial stability, and money supply.
In Australia, the central bank is the Reserve Bank of Australia (RBA).
Central banks play a major role in influencing:
interest rates,
inflation,
lending conditions,
economic activity,
employment,
and overall financial confidence.
Central banks typically manage monetary policy by adjusting tools such as:
the cash rate,
money supply,
and broader financial system settings.
Their decisions can create significant flow-on effects across:
mortgage rates,
borrowing power,
business activity,
consumer spending,
investment markets,
and property markets.
When central banks attempt to slow inflation, borrowing costs may rise and economic activity can cool.
When they attempt to stimulate the economy, lending conditions may ease to encourage spending and investment.
Central bank decisions are closely monitored because even small policy changes can influence property, finance, and investment markets over time.
Download the full guide to understand:
how central banks operate,
the role of the Reserve Bank of Australia,
how monetary policy works,
and how central bank decisions can affect households, businesses, lending conditions, and property markets.


Banking & Finance
Comparison Rate
A comparison rate is a lending figure designed to help borrowers compare the overall cost of different loan products.
It combines:
the advertised interest rate,
plus many standard loan fees and charges,
to provide a broader indication of the loan’s true cost over time.
Comparison rates are commonly used when comparing:
home loans,
investment loans,
personal loans,
and other finance products.
A loan with a lower advertised interest rate may not always be the cheaper option once fees and charges are included.
Comparison rates can help borrowers identify:
hidden costs,
expensive fee structures,
and differences between loan products that may not be obvious at first glance.
However, comparison rates may not include every possible fee, feature, or future change associated with a loan.
Loan features such as:
offset accounts,
redraw facilities,
introductory rates,
or flexible repayment options,
may still influence which loan is most suitable for a borrower’s situation.
Understanding comparison rates can help borrowers make more informed lending decisions rather than focusing only on headline interest rates.
Download the full guide to understand:
how comparison rates work,
what is included,
limitations borrowers should understand,
and how loan structure, fees, and features can affect the real cost of borrowing over time.


Banking & Finance
Consumer Confidence
Consumer confidence refers to how optimistic or pessimistic people feel about their financial position, job security, the economy, and future spending decisions.
When consumer confidence is strong, people are generally more willing to:
spend money,
borrow,
invest,
renovate,
upgrade property,
and make larger financial commitments.
When consumer confidence weakens, people may become more cautious by:
reducing spending,
delaying major purchases,
avoiding new debt,
or postponing property and investment decisions.
Consumer confidence can be influenced by:
interest rates,
inflation,
employment conditions,
cost of living pressures,
economic uncertainty,
government policy,
and broader financial market conditions.
Confidence levels can create significant flow-on effects across:
retail spending,
business activity,
borrowing demand,
investment markets,
and property markets.
In property markets, consumer confidence can affect:
buyer activity,
listing volumes,
auction clearance rates,
property prices,
and overall market momentum.
Even when financial conditions remain stable, changing sentiment alone can sometimes influence market behaviour and decision-making.
Download the full guide to understand:
how consumer confidence works,
what influences public sentiment,
how confidence impacts property and finance markets,
and why market psychology can play a major role in economic activity over time.


Banking & Finance
Cost of Living
Cost of living refers to the amount of money required to cover everyday expenses needed to maintain a certain lifestyle or standard of living.
These expenses can include:
housing costs,
mortgage repayments,
rent,
groceries,
utilities,
fuel,
insurance,
healthcare,
education,
and general household spending.
When the cost of living rises, households may experience increased financial pressure as more income is required to maintain the same lifestyle.
Cost of living pressures can be influenced by:
inflation,
interest rates,
energy prices,
housing shortages,
insurance costs,
wage growth,
supply chain disruptions,
and broader economic conditions.
Rising living costs can create significant flow-on effects across:
household budgets,
borrowing capacity,
savings,
consumer confidence,
spending behaviour,
and property markets.
For property owners and buyers, higher living costs may affect:
borrowing power,
mortgage serviceability,
investment decisions,
renovation plans,
and overall financial flexibility.
Even relatively small increases across multiple household expenses can compound over time and significantly impact long-term financial stability.
Download the full guide to understand:
what drives cost of living changes,
how rising expenses affect households,
the relationship between inflation and living costs,
and how cost of living pressures can influence property, finance, and investment decisions over time.


Banking & Finance
Credit Assessment
A credit assessment is the process a lender uses to determine whether a borrower is financially capable of repaying a loan.
Before approving finance, banks and lenders assess a range of financial factors to measure:
borrowing risk,
repayment capacity,
financial stability,
and overall suitability for the loan being requested.
In simple terms, a credit assessment is the lender deciding:
“Can this person realistically afford this debt both now and into the future?”
What Do Lenders Look At?
During a credit assessment, lenders commonly review:
Income and employment stability
Existing debts and liabilities
Credit history and repayment behaviour
Living expenses
Savings and available cash reserves
Loan-to-Value Ratio (LVR)
Debt-to-Income Ratio (DTI)
Dependants and household expenses
Asset ownership
Business income (if self-employed)
They also assess whether the borrower could still manage repayments if:
interest rates rise,
living costs increase,
or personal circumstances change.
Why Credit Assessments Matter
Credit assessments are one of the biggest gatekeepers in the property and finance market.
A buyer may:
earn a strong income,
own assets,
and still struggle to obtain finance if their servicing position does not meet lender policy.
Likewise, some borrowers may qualify for far more finance than they initially expected.
This is why understanding your position before making property decisions can be extremely important.
Common Reasons Finance Gets Declined
Loan applications may be declined due to:
high existing debt,
poor credit history,
unstable employment,
excessive spending habits,
insufficient savings,
low borrowing capacity,
or lender policy restrictions.
Sometimes the issue is not the borrower itself — it is simply that the loan structure does not fit the lender’s current appetite or lending criteria.
Credit Assessments and the Property Market
Credit assessments directly influence:
borrowing power,
buyer demand,
investor activity,
and overall property market momentum.
When lending becomes tighter:
buyers may borrow less,
competition may reduce,
and price growth can slow.
When lending conditions ease:
borrowing capacity often improves,
more buyers enter the market,
and demand can strengthen.
This is why interest rates, inflation, employment, and banking policy all play a major role in the property market.
Key Insight
A credit assessment is not just about whether a lender says “yes” or “no.”
It is about understanding:
what a lender believes you can safely afford,
how your financial position is viewed,
and how finance conditions may affect your future property options.
Many homeowners and buyers are sitting on more opportunity than they realise — but understanding your financial position properly is the first step.


Banking & Finance
Debt-to-Income Ratio (DTI)
Debt-to-Income Ratio (DTI) is a financial measurement lenders use to compare how much debt a person has against how much income they earn.
In simple terms, it helps lenders determine whether a borrower may already be carrying too much debt relative to their income.
DTI has become an increasingly important part of modern lending assessments, particularly as property prices and living costs have risen.
How Debt-to-Income Ratio Works
A lender typically calculates DTI by dividing:
total existing debt,
bygross annual income.
Example:
If someone earns:
$100,000 per year
And has:
$500,000 in total debt
Their DTI ratio would be:
5:1
Meaning:
they owe five times their annual income.
What Counts as Debt?
Lenders may include:
home loans,
investment loans,
personal loans,
car loans,
credit cards,
buy-now-pay-later facilities,
and other financial liabilities.
Even unused credit card limits can sometimes impact borrowing assessments because lenders may treat them as potential future debt exposure.
Why DTI Matters
Debt-to-Income Ratio helps lenders assess:
borrowing risk,
financial pressure,
and repayment sustainability.
A high DTI may suggest:
repayments could become difficult if interest rates rise,
living costs increase,
or income changes unexpectedly.
This is why borrowers with strong incomes can still face lending restrictions if their debt levels are already considered too high.
What Is Considered a High DTI?
Different lenders have different policies, but generally:
Lower DTI ratios are viewed more favourably.
Higher DTI ratios may trigger tighter lending scrutiny.
Very high DTI levels may reduce borrowing capacity or result in finance being declined.
Importantly:
DTI is only one part of a broader credit assessment.
Lenders also consider:
savings,
employment stability,
credit history,
living expenses,
asset position,
and overall financial behaviour.
DTI and the Property Market
Debt-to-Income policies can directly affect:
borrowing capacity,
buyer demand,
investor activity,
and property price growth.
When lenders tighten DTI limits:
buyers may be approved for less finance,
competition can reduce,
and market momentum may slow.
When lending conditions ease:
borrowing power may improve,
more buyers can enter the market,
and property demand may strengthen.
This is one reason why interest rates, inflation, wages, and banking policy all influence the broader property market.
Key Insight
Debt-to-Income Ratio is not simply about how much money you earn.
It is about:
how your debt compares to your income,
how sustainable your financial position appears,
and how lenders assess your ability to manage future repayments.
Many homeowners and buyers are sitting on more opportunity than they realise — but understanding your position properly is the first step.


Banking & Finance
Default
A default occurs when a borrower fails to meet the repayment obligations on a loan or financial agreement.
In simple terms, it means repayments have not been made as agreed.
Defaults can apply to:
home loans,
credit cards,
personal loans,
car finance,
and other financial commitments.
If repayments continue to be missed, lenders may:
apply fees and penalties,
report the default on a credit file,
begin debt recovery action,
or pursue legal enforcement.
Defaults can negatively affect:
credit scores,
borrowing capacity,
refinancing options,
and future loan approvals.
For property owners, prolonged default on a mortgage may eventually lead to enforcement action or forced sale proceedings.
Financial pressure does not always lead to default — many situations can often be managed early through planning, restructuring, refinancing, or strategic decision-making.
Understanding your position early is often the most important step.


Banking & Finance
Deflation
Deflation occurs when the general price of goods and services across the economy falls over time.
In simple terms:
money becomes more valuable because things cost less.
While lower prices may sound positive at first, prolonged deflation can create serious economic pressure because it often signals:
slowing economic activity,
reduced spending,
weaker business confidence,
and declining demand.
Why Deflation Happens
Deflation can occur when:
consumer spending slows,
unemployment rises,
borrowing reduces,
wages weaken,
or economic confidence falls.
Businesses may lower prices to attract spending, which can place pressure on profits, employment, and investment.
How Deflation Affects Property
Deflation can influence the property market by:
reducing buyer confidence,
slowing borrowing activity,
tightening lending conditions,
and lowering demand for property purchases.
During deflationary periods:
people may delay buying decisions,
investors may become more cautious,
and economic uncertainty can increase.
Property markets generally perform more strongly during periods of stable economic growth and moderate inflation rather than prolonged deflation.
Deflation vs Inflation
Inflation = prices rise over time.
Deflation = prices fall over time.
Both can affect:
borrowing power,
interest rates,
property demand,
and financial decision-making.
Key Insight
Deflation is often less about “cheap prices” and more about weakening economic confidence and slowing financial activity.
Understanding how broader economic conditions affect borrowing, confidence, and property markets can help people make more informed decisions.
Property decisions should be made with strategy, not panic.


Banking & Finance
Disposable Income
Disposable income is the amount of money a person or household has left after tax has been paid.
In simple terms:
it is the money available to spend, save, invest, or put toward living expenses.
Disposable income plays a major role in:
borrowing power,
lifestyle choices,
savings capacity,
and property decisions.
Why Disposable Income Matters
The more disposable income a household has:
the easier it may be to manage repayments,
build savings,
invest,
or absorb rising living costs.
When disposable income tightens due to:
higher interest rates,
inflation,
rising insurance costs,
or increasing household expenses,
financial pressure can begin to build.
Disposable Income and Property
Disposable income directly affects:
borrowing capacity,
buyer confidence,
investor activity,
and housing demand.
When households have stronger disposable income:
spending confidence often improves,
buyers may borrow more comfortably,
and property activity can strengthen.
When disposable income reduces:
buyers may become more cautious,
borrowing power can tighten,
and upgrading or investing decisions may slow.
What Impacts Disposable Income?
Disposable income can be affected by:
wages and salary growth,
taxation,
inflation,
mortgage repayments,
rent,
utilities,
fuel prices,
insurance costs,
and general cost of living pressures.
Even small increases across multiple household expenses can significantly reduce financial flexibility over time.
Key Insight
Disposable income is not just about how much money you earn.
It is about:
how much money remains available after expenses,
how flexible your financial position is,
and how comfortably you can manage future financial decisions.
Understanding your position properly is often the first step toward making stronger long-term property and financial decisions.


Banking & Finance
Fiscal Policy
Fiscal policy refers to how governments use taxation and government spending to influence the economy.
In simple terms:
it is the government adjusting where money is collected and where money is spent in an attempt to influence:
economic growth,
employment,
inflation,
business activity,
and consumer confidence.
Fiscal policy is one of the major tools governments use to manage economic conditions.
How Fiscal Policy Works
Governments influence the economy through:
taxation,
infrastructure spending,
grants and subsidies,
welfare programs,
stimulus packages,
and public investment.
Examples of fiscal policy may include:
reducing taxes to stimulate spending,
increasing infrastructure projects,
offering housing incentives,
or increasing government spending during economic slowdowns.
Expansionary vs Contractionary Fiscal Policy
Expansionary Fiscal Policy
Used to stimulate the economy.
This may involve:
lower taxes,
increased government spending,
or stimulus measures.
The goal is usually to:
increase spending,
boost employment,
and support economic growth.
Contractionary Fiscal Policy
Used to slow inflation or reduce government debt pressure.
This may involve:
reducing spending,
increasing taxes,
or tightening government budgets.
The goal is usually to reduce excess demand and financial pressure in the economy.
Fiscal Policy and Property Markets
Fiscal policy can strongly influence property markets because it affects:
household confidence,
borrowing conditions,
employment,
infrastructure growth,
and disposable income.
Government decisions relating to:
housing schemes,
first-home buyer incentives,
taxation changes,
infrastructure spending,
and migration policies
can all directly impact property demand and market activity.
Fiscal Policy vs Monetary Policy
Fiscal Policy = Government decisions involving spending and taxation.
Monetary Policy = Central bank decisions involving interest rates and money supply.
Both work together to influence the broader economy.
Key Insight
Fiscal policy is not just about government budgets.
It directly affects:
consumer confidence,
borrowing conditions,
household finances,
and property market activity.
Understanding how government decisions flow through the economy can help people make more informed financial and property decisions over time.
Property decisions should be made with strategy, not panic.


Banking & Finance
Fixed Rate
A fixed rate loan is a loan where the interest rate stays the same for a set period of time.
In simple terms:
your repayments remain predictable during the fixed term, regardless of whether interest rates rise or fall in the broader market.
Fixed rate periods commonly range from:
1 year,
2 years,
3 years,
5 years,
or longer depending on the lender.
Why People Choose Fixed Rates
Many borrowers choose fixed rates because they provide:
repayment certainty,
budgeting stability,
and protection from rising interest rates.
Knowing exactly what repayments will be during the fixed term can help households better manage:
cash flow,
living expenses,
and long-term planning.
Advantages of a Fixed Rate
Potential benefits may include:
stable repayments,
protection from rate increases,
easier budgeting,
and greater financial certainty.
Fixed rates are often more attractive during periods of:
rising interest rates,
inflation pressure,
or economic uncertainty.
Things to Consider
Fixed rate loans can also come with limitations, including:
less flexibility,
break costs if the loan is changed early,
limits on extra repayments,
and reduced access to some loan features.
If market interest rates fall, borrowers on a fixed rate may also miss out on lower repayments available on variable loans.
Fixed Rate vs Variable Rate
Fixed Rate = interest rate stays locked for a set period.
Variable Rate = interest rate can rise or fall over time.
Some borrowers also choose split loans, combining both fixed and variable portions to balance certainty and flexibility.
Fixed Rates and Property Markets
Fixed rates can strongly influence:
borrowing confidence,
buyer activity,
refinancing decisions,
and overall market momentum.
When fixed rates are low:
borrowing demand may increase,
buyers may feel more confident entering the market,
and property activity can strengthen.
When fixed rates rise:
borrowing costs increase,
affordability pressure grows,
and some buyers may become more cautious.
Key Insight
A fixed rate is not simply about locking in an interest rate.
It is about balancing:
certainty,
flexibility,
risk management,
and long-term financial planning.
Understanding how loan structures align with your goals and financial position is often one of the most important parts of making confident property decisions.


Banking & Finance
GDP (Gross Domestic Product)
GDP stands for Gross Domestic Product.
It is one of the main measurements used to track the size and performance of an economy.
In simple terms:
GDP measures the total value of goods and services produced within a country over a specific period of time.
This includes things like:
construction,
retail spending,
business activity,
manufacturing,
exports,
professional services,
and government spending.
Why GDP Matters
GDP is used to measure:
economic growth,
business activity,
consumer confidence,
and the overall strength of the economy.
When GDP is growing:
businesses are often producing more,
employment may improve,
spending confidence can rise,
and economic activity generally strengthens.
When GDP slows or contracts:
economic confidence may weaken,
businesses may reduce spending,
unemployment pressure can increase,
and financial conditions may tighten.
GDP and Property Markets
GDP can strongly influence property markets because economic growth affects:
employment,
borrowing confidence,
wages,
migration,
and investment activity.
A growing economy can support:
stronger buyer confidence,
increased housing demand,
higher construction activity,
and improved lending conditions.
A slowing economy may lead to:
reduced buyer activity,
tighter lending,
cautious investors,
and slower market conditions.
What Drives GDP Growth?
GDP growth can be influenced by:
consumer spending,
business investment,
government infrastructure spending,
exports,
population growth,
and borrowing activity.
Major industries such as:
mining,
agriculture,
tourism,
construction,
and property
can all contribute significantly to economic performance.
GDP and Recessions
If GDP declines for an extended period, it can signal economic weakness or recessionary conditions.
This is why GDP figures are closely watched by:
governments,
banks,
investors,
and financial markets.
Key Insight
GDP is not just an economic statistic.
It reflects:
the strength of economic activity,
confidence within the economy,
and the financial environment influencing households, businesses, and property markets.
Understanding broader economic conditions can help people make more informed long-term financial and property decisions.


Banking & Finance
Guarantor
A guarantor is a person who agrees to support someone else’s loan by offering their own financial backing or security.
In simple terms:
a guarantor helps reduce the lender’s risk if the borrower cannot meet their loan repayments.
Guarantors are commonly used when:
a borrower has a smaller deposit,
lower borrowing capacity,
or limited financial history.
How a Guarantor Works
A guarantor agrees that if the borrower defaults on the loan:
the guarantor may become financially responsible for part or all of the debt.
In many cases, a guarantor uses equity in their own property as additional security for the loan.
This can sometimes help borrowers:
avoid lender’s mortgage insurance (LMI),
increase borrowing capacity,
or enter the property market sooner.
Common Guarantor Situations
Guarantor arrangements are often used:
by first-home buyers,
younger borrowers,
family members,
or people needing additional support to secure finance.
Parents acting as guarantors for children is one of the most common examples.
Risks of Being a Guarantor
Being a guarantor can carry significant financial risk.
If the borrower cannot meet repayments:
the guarantor may become responsible for the debt,
their own property or assets may be affected,
and their future borrowing capacity may reduce.
This is why guarantors should fully understand:
the loan structure,
the risks involved,
and their legal obligations before agreeing.
Independent legal and financial advice is often strongly recommended.
Guarantors and Property Markets
Guarantor arrangements can influence property markets by helping:
buyers enter the market sooner,
younger households secure finance,
and borrowing capacity improve in some situations.
They are often more common during periods where:
property prices are high,
deposits are difficult to save,
or affordability pressure increases.
Key Insight
A guarantor arrangement is not simply about helping someone obtain a loan.
It is a serious financial commitment that can affect:
both parties’ financial positions,
future borrowing ability,
and long-term financial security.
Understanding the risks, responsibilities, and structure properly is critical before entering any guarantor arrangement.
Banking & Finance
Inflation
Inflation refers to the increase in the cost of goods and services over time, which reduces the purchasing power of money.
In simple terms:
As inflation rises, your money buys less.
For example:
groceries become more expensive,
fuel prices rise,
rents increase,
and construction costs climb.
Inflation is one of the biggest drivers behind:
interest rate changes,
mortgage repayments,
borrowing power,
property prices,
and overall cost of living.
When inflation rises too quickly, the Reserve Bank may increase interest rates to slow spending across the economy.
Inflation and Property
Inflation can impact the property market in several ways:
higher interest rates may reduce borrowing capacity,
rising construction costs can increase replacement values,
and rental pressure may push rents upward.
In regional markets like Bundaberg, inflation has also contributed to:
higher building costs,
tighter housing supply,
and increased pressure on established homes.
Property is often viewed as a long-term asset that may hold value better than cash during inflationary periods.
Understanding inflation helps property owners, buyers, and investors make more informed financial decisions.


Banking & Finance
Interest Only
An interest-only loan is a type of loan where the borrower only pays the interest charged on the loan for a set period of time.
During this period:
repayments are lower,
but the actual loan balance usually does not reduce.
Once the interest-only period ends, the loan generally converts to Principal & Interest repayments, which are usually higher.
Why People Use Interest-Only Loans
Interest-only lending is commonly used to:
improve short-term cash flow,
reduce holding costs,
increase financial flexibility,
or assist with investment strategies.
It is often used by:
property investors,
developers,
business owners,
or borrowers planning future asset sales or refinancing.
Interest Only and Property Investment
Many investors use interest-only loans to:
maximise cash flow,
manage multiple properties,
or direct extra funds into other investments or projects.
In some situations, lower repayments may improve:
borrowing flexibility,
serviceability,
and portfolio growth opportunities.
However, because the loan balance is not reducing during the interest-only period, the debt can remain higher for longer.
Things to Consider
Interest-only loans can be useful tools when used strategically, but they are not suitable for every borrower.
Important considerations include:
future repayment increases,
overall interest costs,
refinancing risk,
and long-term financial goals.
The right structure depends on:
your income,
cash flow,
investment strategy,
and future plans.
Property decisions should be made with strategy, not panic. Understanding your position is the first step.


Banking & Finance
Interest Rate
An interest rate is the percentage charged by a lender for borrowing money.
In simple terms:
It is the cost of using someone else’s money.
Interest rates directly affect:
mortgage repayments,
borrowing capacity,
business lending,
investment returns,
and overall affordability.
How Interest Rates Work
When interest rates rise:
loan repayments usually increase,
borrowing power may reduce,
and household budgets can come under pressure.
When interest rates fall:
repayments may decrease,
borrowing capacity can improve,
and buyers may become more active in the property market.
Even small interest rate changes can significantly impact long-term loan costs.
Interest Rates and Property
Interest rates are one of the biggest drivers of property market activity.
Higher rates can:
slow buyer demand,
reduce borrowing confidence,
and place pressure on affordability.
Lower rates can:
stimulate buyer activity,
improve serviceability,
and increase competition for property.
This is why interest rate movements are closely watched across the property industry.
Fixed vs Variable Rates
Most home loans fall into two main categories:
Fixed Rate
locks in an interest rate for a set period,
offering repayment certainty.
Variable Rate
can move up or down over time,
depending on market conditions and lender changes.
Each structure has advantages depending on:
market conditions,
risk tolerance,
and financial strategy.
The Bigger Picture
Interest rates are heavily influenced by:
inflation,
economic growth,
employment conditions,
and decisions made by the Reserve Bank.
Understanding how interest rates affect your position is an important part of making informed property and financial decisions.
Property decisions should be made with strategy, not panic. Understanding your position is the first step.


Banking & Finance
Liquidity
Liquidity refers to how quickly and easily an asset can be converted into cash without significantly affecting its value.
In simple terms:
The easier something is to turn into usable cash, the more liquid it is.
Cash in a bank account is considered highly liquid because it is immediately available.
Property, on the other hand, is generally considered less liquid because:
it can take time to sell,
market conditions can affect demand,
and there are costs involved in accessing the equity.
Why Liquidity Matters
Liquidity plays a major role in:
personal financial stability,
investment flexibility,
business operations,
and property decision-making.
Having strong liquidity can help people:
manage unexpected expenses,
take advantage of opportunities,
reduce financial stress,
and maintain flexibility during changing market conditions.
Liquidity and Property
Property owners often have significant wealth tied up in real estate, but that wealth may not always be immediately accessible.
This is why many people explore strategies such as:
refinancing,
accessing usable equity,
restructuring debt,
or selling assets to improve liquidity.
A person may appear asset-rich on paper while still experiencing cash flow pressure.
Liquidity in Changing Markets
Liquidity can become especially important during:
rising interest rate periods,
economic uncertainty,
business downturns,
or market slowdowns.
When borrowing conditions tighten, access to cash and financial flexibility often become more important than ever.
The Bigger Picture
Good financial planning is not just about building wealth — it is also about maintaining flexibility and access to funds when needed.
Understanding your liquidity position can help you make more strategic decisions around:
property,
investing,
debt,
and long-term financial goals.
Property decisions should be made with strategy, not panic. Understanding your position is the first step.


Banking & Finance
Loan Term
A loan term is the length of time you have to repay a loan in full.
For home loans, the loan term is usually expressed in years. Common examples include 20-year, 25-year or 30-year loan terms.
The loan term affects how long you make repayments, how much your regular repayments may be, and how much interest you may pay over the life of the loan.
In simple terms
A shorter loan term usually means higher repayments, but less interest paid over time.
A longer loan term usually means lower repayments, but more interest paid overall.
Why loan term matters
Your loan term can influence:
your monthly repayment amount
your cash flow
your total interest cost
your borrowing capacity
how quickly you build equity
your long-term financial position
This is why the cheapest monthly repayment is not always the best long-term option.
Loan term and property decisions
When buying, refinancing or reviewing your financial position, the loan term should match your broader strategy.
For example, someone focused on keeping repayments manageable may choose a longer loan term. Someone focused on reducing debt faster may prefer a shorter term, provided the repayments are affordable.
The right answer depends on your income, lifestyle, risk comfort, future plans and property goals.
Things to consider
Before choosing or changing a loan term, it is worth considering:
Can you comfortably afford the repayments?
How much interest will be paid over the full loan?
Are you planning to sell, upgrade or refinance later?
Do you need flexibility for family, business or investment goals?
Can extra repayments help reduce the loan faster?
Key Insight
A loan term is not just a repayment timeline. It is a financial structure that can shape your cash flow, debt position and future options.
Understanding your position is the first step.


Banking & Finance
Loan-to-Value Ratio (LVR)
Loan-to-Value Ratio, commonly called LVR, is the percentage of a property’s value that is being borrowed from a lender.
It is one of the key measurements banks use when assessing risk on a home loan.
How LVR works
LVR is calculated by comparing the loan amount to the value of the property.
For example:
Property value: $800,000
Loan amount: $640,000
The LVR would be 80%.
In simple terms:
The higher the LVR, the more money is being borrowed compared to the property value.
Why LVR matters
LVR can affect:
loan approval
borrowing capacity
interest rates
lender requirements
access to certain loan products
whether Lenders Mortgage Insurance (LMI) applies
Banks generally see lower LVR loans as lower risk because the borrower has contributed a larger deposit or holds more equity.
Common LVR levels
80% LVR or below
Often considered a stronger lending position.
Many borrowers try to stay at or below 80% to avoid paying Lenders Mortgage Insurance (LMI).
Above 80% LVR
The lender may require LMI, which is an insurance cost that protects the lender, not the borrower.
Higher LVR loans can sometimes face tighter lending conditions or additional checks.
LVR and property owners
LVR is important for:
first-home buyers
refinancing
accessing usable equity
property investors
upgrading or restructuring debt
As property values rise or loans reduce over time, the LVR can improve and create more financial flexibility.
Things to consider
A lower LVR can provide:
stronger equity position
lower lending risk
improved borrowing flexibility
access to better lending options
However, waiting too long to save a larger deposit may also delay entering the market.
Property decisions should be made with strategy, not panic.
Key Insight
LVR is not just a banking number. It is a measurement of risk, equity and financial position.
Understanding your position is the first step.


Banking & Finance
Monetary Policy
Monetary policy refers to the actions taken by a central bank to influence the economy, inflation, borrowing conditions and financial activity.
In Australia, monetary policy is primarily managed by the Reserve Bank of Australia (RBA).
One of the main tools used in monetary policy is the cash rate, which influences interest rates across the banking system.
In simple terms
Monetary policy is used to help manage:
inflation
economic growth
employment
borrowing activity
spending confidence
financial stability
When the economy is running too hot and inflation rises, interest rates may increase to slow spending and borrowing.
When economic activity slows, interest rates may decrease to encourage borrowing, investment and spending.
How monetary policy affects property
Monetary policy has a direct impact on the property market because it influences borrowing costs and buyer confidence.
Changes in monetary policy can affect:
mortgage repayments
borrowing capacity
property demand
investor activity
refinancing opportunities
construction and development activity
Even small interest rate movements can significantly affect affordability and buyer behaviour.
Monetary policy and interest rates
When interest rates rise:
borrowing generally becomes more expensive
repayments may increase
borrowing power may reduce
buyer demand can slow
When interest rates fall:
borrowing may become cheaper
repayments may reduce
borrowing capacity may improve
market activity can increase
This is why property markets closely watch Reserve Bank announcements and economic conditions.
The bigger picture
Monetary policy is influenced by many economic factors, including:
inflation
employment levels
consumer spending
economic growth
global financial conditions
business confidence
Property markets do not move in isolation. They are closely tied to broader economic conditions.
Things to consider
Interest rate environments can change over time, so property owners and buyers should consider:
repayment buffers
long-term affordability
debt structure
risk tolerance
future financial flexibility
Property decisions should be made with strategy, not panic.
Key Insight
Monetary policy is not just an economic term discussed by banks and governments.
It directly influences borrowing conditions, property affordability and financial decision-making across the market.
Understanding your position is the first step.


Banking & Finance
Mortgage
A mortgage is a loan used to purchase property, where the property itself is used as security for the loan.
The lender provides funds to help buy the property, and the borrower agrees to repay the loan over time through regular repayments.
If the loan is not repaid according to the agreement, the lender may have the legal right to recover the debt by selling the secured property.
In simple terms
A mortgage allows people to buy property without paying the full purchase price upfront.
Instead, the borrower contributes a deposit and borrows the remaining amount from a lender.
The loan is then repaid over an agreed period, often 20 to 30 years.
How a mortgage works
A mortgage generally includes:
the loan amount
the interest rate
the loan term
repayment structure
lender conditions
Repayments usually consist of:
Principal — reducing the loan balance
Interest — the cost charged for borrowing the money
Some loans may also include features such as:
offset accounts
redraw facilities
fixed or variable interest rates
interest-only periods
Why mortgages matter
Mortgages play a major role in the property market because they influence:
borrowing capacity
affordability
property demand
investment activity
cash flow and financial flexibility
Changes in interest rates or lending conditions can significantly affect mortgage repayments and buyer confidence.
Mortgage and property ownership
For many Australians, a mortgage is one of the largest financial commitments they will take on.
This is why understanding the structure of the loan is important before making property decisions.
The right mortgage structure depends on factors such as:
income and cash flow
long-term goals
lifestyle
investment strategy
risk tolerance
future plans
Things to consider
Before taking on or reviewing a mortgage, it is important to consider:
repayment affordability
interest rate risk
loan flexibility
extra repayment options
future financial goals
refinancing opportunities
Property decisions should be made with strategy, not panic.
Key Insight
A mortgage is not just a loan.
It is a long-term financial structure that can influence your cash flow, equity position and future opportunities for many years.
Understanding your position is the first step.


Banking & Finance
Mortgage Stress
Mortgage stress occurs when a household is struggling to comfortably manage their mortgage repayments and ongoing living costs.
It can happen when too much income is being directed toward loan repayments, leaving limited financial breathing room.
In simple terms
Mortgage stress usually means a property owner is feeling financial pressure from their home loan.
This pressure may increase due to:
rising interest rates
increased living costs
reduced income
unexpected expenses
high levels of debt
Signs of mortgage stress
Common signs can include:
difficulty meeting repayments
relying on credit cards or savings
falling behind on bills
financial anxiety or pressure
having little money left after expenses
Why mortgage stress matters
Mortgage stress can affect:
financial stability
borrowing capacity
investment decisions
lifestyle flexibility
long-term property plans
In severe situations, ongoing mortgage stress can lead to arrears or forced property sales.
Managing mortgage stress
Options may include:
reviewing your loan structure
refinancing
reducing expenses
restructuring debt
accessing usable equity
speaking with your lender early
Property decisions should be made with strategy, not panic.
Key Insight
Mortgage stress is not always caused by bad decisions.
Sometimes changing interest rates, economic conditions and life circumstances place pressure on households over time.
Understanding your position is the first step.


Banking & Finance
Net Worth
Net worth is the total value of what you own, minus what you owe.
It is a simple way of measuring your overall financial position.
In simple terms
Net worth is calculated by taking your assets and subtracting your liabilities.
Assets may include:
property
savings
investments
vehicles
superannuation
business interests
Liabilities may include:
mortgages
personal loans
credit cards
business debt
Why net worth matters
Net worth helps show:
your financial progress
your equity position
your overall financial strength
your long-term wealth position
A person with high income is not always wealthy if they also carry high levels of debt.
Net worth and property
Property is often one of the largest contributors to household net worth in Australia.
As property values rise and debt reduces over time, net worth can improve.
This is why equity, debt management and long-term planning are important parts of building wealth.
Things to consider
Net worth is not only about income.
It is influenced by:
asset growth
debt levels
spending habits
investment decisions
financial strategy
Property decisions should be made with strategy, not panic.
Key Insight
Net worth is not just about what you earn.
It is about what you own, what you owe, and how your financial position changes over time.
Understanding your position is the first step.


Banking & Finance
Offset Account
An offset account is a bank account linked to a home loan that helps reduce the amount of interest charged on the loan.
The money sitting in the offset account is offset against the loan balance when interest is calculated.
In simple terms
Instead of earning high interest like a savings account, the money in an offset account helps reduce your home loan interest.
For example:
Home loan balance: $600,000
Offset account balance: $50,000
Interest may only be calculated on $550,000.
Why offset accounts matter
Offset accounts can help:
reduce interest costs
improve cash flow
pay off a loan faster
increase financial flexibility
keep savings accessible
Even small amounts held consistently in an offset account can reduce long-term interest over time.
Offset accounts and property strategy
Offset accounts are commonly used by:
owner-occupiers
investors
business owners
borrowers wanting repayment flexibility
Some people use offset accounts to hold savings, wages or emergency funds while still reducing loan interest.
Things to consider
Not all loans include offset accounts, and some may have:
additional fees
account conditions
partial offset features
The value of an offset account often depends on:
loan size
interest rate
savings balance
how consistently funds are kept in the account
Property decisions should be made with strategy, not panic.
Key Insight
An offset account is not just a savings account linked to a loan.
Used properly, it can become a powerful tool for improving cash flow, reducing interest and building long-term financial flexibility.
Understanding your position is the first step.


Banking & Finance
Pre-Approval
Pre-approval is an indication from a lender showing how much you may be able to borrow before purchasing a property.
It is commonly used by buyers to understand their budget and borrowing position before making offers or attending inspections.
In simple terms
Pre-approval is an early assessment of your borrowing capacity based on your financial position.
The lender will usually review factors such as:
income
savings
debts
living expenses
credit history
If approved, the lender may provide a borrowing limit for a set period of time.
Why pre-approval matters
Pre-approval can help buyers:
understand their budget
narrow their property search
move faster when opportunities arise
show confidence to agents and sellers
identify financial issues early
It can also reduce uncertainty during the buying process.
Things to understand
Pre-approval is not always a full or unconditional loan approval.
Final approval may still depend on:
the property itself
valuation results
updated financial checks
lender policy changes
This is why buyers should avoid assuming pre-approval guarantees finance.
Pre-approval and property strategy
Pre-approval can be useful for:
first-home buyers
investors
upsizers
downsizers
buyers using sell-to-buy strategies
Knowing your financial position early can help you plan with more confidence and reduce rushed decisions.
Things to consider
Before applying for pre-approval, it is important to consider:
your repayment comfort level
interest rate changes
additional buying costs
your long-term goals
future financial flexibility
Property decisions should be made with strategy, not panic.
Key Insight
Pre-approval is not just about finding out how much you can borrow.
It is about understanding your financial position before making major property decisions.
Understanding your position is the first step.


Banking & Finance
Principal & Interest
Principal & Interest, often called P&I, is a loan repayment structure where your repayments cover both:
the principal (the amount borrowed), and
the interest charged on the loan.
Over time, the loan balance gradually reduces as repayments are made.
In simple terms
With a Principal & Interest loan:
part of your repayment reduces the debt
part of your repayment pays the lender’s interest charge
As the loan reduces, the interest portion usually becomes smaller over time.
Why it matters
Principal & Interest repayments can help:
reduce debt over time
build equity in the property
improve long-term financial position
lower total interest paid compared to some interest-only structures
Things to consider
Principal & Interest repayments are often higher than interest-only repayments because the loan balance is actively being reduced.
The right loan structure depends on:
cash flow
financial goals
investment strategy
risk comfort
long-term plans
Property decisions should be made with strategy, not panic.
Key Insight
Principal & Interest loans are designed to gradually reduce debt over time, not just cover interest costs.
Understanding your position is the first step.


Banking & Finance
Quantitative Easing
Quantitative Easing, often called QE, is an economic strategy where a central bank injects money into the financial system to help support the economy.
This is usually done by purchasing government bonds or other financial assets from banks and financial institutions.
In simple terms
Quantitative Easing is designed to increase liquidity and encourage:
borrowing
spending
lending
investment activity
It is generally used during periods of economic slowdown or financial uncertainty.
Why Quantitative Easing matters
When more money flows through the financial system, it can influence:
interest rates
borrowing conditions
property markets
business activity
investor confidence
Lower borrowing costs and increased liquidity can encourage more market activity.
Quantitative Easing and property
QE can affect property markets by:
improving access to finance
increasing borrowing activity
supporting buyer confidence
encouraging investment into assets like property
In some cases, strong liquidity and lower rates can place upward pressure on asset prices.
Things to consider
Quantitative Easing is a broad economic tool and can also contribute to:
inflation pressure
rising asset prices
changing lending conditions
long-term economic risks
Property markets are closely linked to broader financial conditions.
Key Insight
Quantitative Easing is not simply “printing money.”
It is a monetary policy tool designed to support liquidity, confidence and economic activity during difficult conditions.
Understanding your position is the first step.


Banking & Finance
Recession
A recession is a period of economic slowdown where business activity, spending and growth begin to weaken across the economy.
Recessions are often associated with reduced consumer confidence, lower investment activity and tighter financial conditions.
In simple terms
During a recession, people and businesses generally become more cautious with money.
This can lead to:
lower spending
weaker business activity
job losses or reduced hiring
slower property activity
tighter lending conditions
Why recessions matter
Recessions can affect:
employment
borrowing confidence
interest rates
business growth
property demand
investment decisions
Some industries and regions may be affected more heavily than others.
Recession and property markets
Property markets can slow during recessions because buyers may become more cautious and borrowing conditions can tighten.
This may lead to:
reduced buyer activity
longer selling times
lower competition
slower price growth
However, not all property markets react the same way. Some areas remain resilient due to supply shortages, population growth or local economic drivers.
Things to consider
Economic cycles are a normal part of long-term markets.
During uncertain periods, many people focus on:
cash flow
debt management
financial buffers
long-term strategy
maintaining flexibility
Property decisions should be made with strategy, not panic.
Key Insight
A recession does not automatically mean property markets collapse.
Markets respond differently depending on interest rates, supply, employment and local economic conditions.
Understanding your position is the first step.


Banking & Finance
Redraw Facility
A redraw facility is a feature on some home loans that allows you to access extra repayments you have already made on the loan.
If you have paid more than the minimum required repayment, those additional funds may become available to redraw later if needed.
In simple terms
A redraw facility can allow you to:
make extra repayments when possible
reduce your loan balance faster
access those extra funds again in the future
For example, some borrowers use redraw facilities for:
emergencies
renovations
vehicle purchases
investing
managing cash flow
Why redraw facilities matter
Making extra repayments can help:
reduce interest costs
shorten the loan term
build equity faster
A redraw facility can also provide flexibility by allowing access to those additional repayments if circumstances change.
Things to consider
Not all loans offer redraw facilities, and some lenders may have:
redraw limits
minimum withdrawal amounts
fees or conditions
processing delays
Access to redraw funds is also controlled by the lender and loan terms.
Redraw vs Offset Account
A redraw facility and an offset account can both help reduce interest, but they work differently.
A redraw facility involves accessing extra loan repayments already made.
An offset account is a separate savings account linked to the loan.
The right structure depends on your financial goals, flexibility needs and loan strategy.
Key Insight
A redraw facility is not free money.
It is access to extra repayments you have already contributed toward your loan.
Understanding your position is the first step.


Banking & Finance
Refinancing
Refinancing is the process of replacing your current loan with a new loan, either with the same lender or a different lender.
People refinance for many different reasons, including reducing repayments, improving loan features or accessing equity.
In simple terms
Refinancing means reviewing your current loan structure and changing it to better suit your financial position or goals.
This may involve:
a lower interest rate
different loan features
debt consolidation
accessing usable equity
changing repayment structures
improving cash flow
Why refinancing matters
Refinancing can help:
reduce interest costs
lower repayments
improve flexibility
shorten the loan term
restructure debt
support investment or renovation plans
In some cases, refinancing may also improve long-term financial efficiency.
Refinancing and property strategy
Refinancing is commonly used by:
owner-occupiers
investors
upsizers and downsizers
borrowers wanting to access equity
people restructuring finances during changing market conditions
The right structure depends on your income, goals, debt levels and long-term plans.
Things to consider
Refinancing is not always automatically beneficial.
It is important to consider:
fees and discharge costs
loan term changes
interest rate structure
borrowing conditions
lender policies
long-term financial impact
Property decisions should be made with strategy, not panic.
Key Insight
Refinancing is not just about chasing a lower interest rate.
It is about making sure your loan structure still aligns with your financial position and future goals.
Understanding your position is the first step.


Banking & Finance
Security
In lending and finance, security refers to an asset that is used as protection for a loan.
For property loans, the security is usually the property being purchased or an existing property owned by the borrower.
In simple terms
When a lender provides a loan, they take security over an asset to reduce their risk.
If the borrower cannot meet the loan repayments, the lender may have legal rights relating to the secured asset.
Common types of security
Security can include:
residential property
investment property
vacant land
vehicles
business assets
savings or cash deposits
Property is one of the most common forms of loan security in Australia.
Why security matters
Security helps lenders assess:
lending risk
borrowing capacity
loan conditions
interest rates
approval strength
The value and type of security can influence how much a lender may be willing to lend.
Security and property
In property lending, the lender generally registers an interest against the property until the loan is repaid.
As the loan balance reduces and equity grows, the property owner may gain greater financial flexibility.
Security can also be important when:
refinancing
accessing equity
restructuring debt
supporting investment strategies
Things to consider
Using an asset as security is a serious financial commitment.
It is important to understand:
repayment obligations
lender rights
risks if repayments cannot be maintained
the impact on future borrowing
Property decisions should be made with strategy, not panic.
Key Insight
Security is not simply paperwork attached to a loan.
It is the asset position supporting the finance structure behind the transaction.
Understanding your position is the first step.


Banking & Finance
Serviceability
Serviceability refers to a lender’s assessment of whether a borrower can comfortably afford to repay a loan.
It is one of the key factors banks use when deciding how much someone may be able to borrow.
In simple terms
Serviceability is about income versus expenses.
Lenders look at factors such as:
income
living expenses
existing debts
credit commitments
interest rates
household spending
The goal is to determine whether the borrower can manage repayments now and into the future.
Why serviceability matters
Serviceability affects:
borrowing capacity
loan approval
refinancing options
investment opportunities
financial flexibility
Even if a borrower has a strong deposit or valuable assets, poor serviceability may limit borrowing ability.
Serviceability and property
Changes in interest rates, debt levels or living costs can impact serviceability over time.
This is why many borrowers review their position before:
buying property
refinancing
investing
upgrading homes
restructuring debt
Things to consider
Improving serviceability may involve:
reducing debt
increasing income
lowering expenses
restructuring loans
improving cash flow
Property decisions should be made with strategy, not panic.
Key Insight
Serviceability is not just about what you earn.
It is about whether your overall financial position can sustainably support the loan.
Understanding your position is the first step.


Banking & Finance
Stagflation
Stagflation is an economic situation where inflation remains high while economic growth slows and unemployment may increase.
It is considered challenging because prices continue rising even though the economy is weakening.
In simple terms
Stagflation can create pressure on households and businesses at the same time.
This may involve:
rising living costs
slower wage growth
weaker business activity
reduced consumer confidence
higher interest rates
slower economic growth
Why stagflation matters
Stagflation can affect:
borrowing power
household budgets
investment confidence
business profitability
property affordability
lending conditions
It can also create uncertainty across financial and property markets.
Stagflation and property
Property markets may react differently during stagflation depending on:
interest rates
supply shortages
local employment
population growth
lending policies
Higher costs and tighter borrowing conditions can slow buyer activity, while limited housing supply may continue supporting some property values.
Things to consider
During uncertain economic conditions, many people focus on:
cash flow management
reducing unnecessary debt
maintaining financial buffers
reviewing long-term strategies
improving financial flexibility
Property decisions should be made with strategy, not panic.
Key Insight
Stagflation is difficult because it combines rising costs with slower economic conditions.
Understanding your position becomes even more important during uncertain markets.


Banking & Finance
Variable Rate
A variable rate is an interest rate that can move up or down over time.
Unlike a fixed rate, a variable rate changes depending on market conditions, lender decisions and broader economic factors.
In simple terms
With a variable rate loan:
repayments may increase
repayments may decrease
interest costs can change over time
This means the cost of the loan is not locked in for a fixed period.
Why variable rates matter
Variable rates can affect:
mortgage repayments
borrowing capacity
cash flow
investment returns
refinancing opportunities
Even small interest rate changes can influence long-term loan costs and affordability.
Variable rates and property
Variable rate loans are commonly used by:
owner-occupiers
investors
borrowers wanting flexibility
people planning to make extra repayments
Many variable loans may include features such as:
offset accounts
redraw facilities
extra repayment flexibility
Things to consider
Variable rates can provide flexibility, but they also carry uncertainty.
It is important to consider:
repayment buffers
future interest rate movements
financial flexibility
risk tolerance
long-term affordability
Property decisions should be made with strategy, not panic.
Key Insight
A variable rate can create opportunities when rates fall, but it can also increase pressure when rates rise.
Understanding your position is the first step.


Banking & Finance
Wage Growth
Wage growth refers to the increase in wages and salaries over time across the economy.
It is commonly used as an indicator of income growth, employment conditions and overall economic strength.
In simple terms
Wage growth measures whether workers are earning more money over time.
This can happen due to:
promotions
skills shortages
inflation pressures
stronger business conditions
increased demand for workers
Why wage growth matters
Wage growth can affect:
household spending
borrowing capacity
property affordability
consumer confidence
inflation
interest rate decisions
Stronger wages may improve financial flexibility, while weak wage growth can place pressure on household budgets.
Wage growth and property
Wage growth can influence the property market because income levels affect what buyers may be able to borrow and repay.
Higher wage growth may support:
stronger buyer demand
improved serviceability
increased borrowing confidence
higher spending activity
However, if property prices rise faster than wages, affordability pressure can increase.
Things to consider
Wage growth does not always move evenly across industries or regions.
Factors that may influence wage growth include:
economic conditions
unemployment levels
inflation
business profitability
labour shortages
Property decisions should be made with strategy, not panic.
Key Insight
Wage growth is not just about earning more money.
It influences borrowing power, affordability and overall financial confidence throughout the economy.
Understanding your position is the first step.


Banking & Finance
Asset Allocation
Asset allocation refers to how investments and assets are divided across different asset types.
The goal is to balance risk, growth potential, income and financial stability over time.
In simple terms
Asset allocation is about not having all your money tied up in one type of asset.
A portfolio may include a mix of:
property
shares
cash
superannuation
bonds
businesses or alternative investments
Different assets perform differently under changing market conditions.
Why asset allocation matters
Asset allocation can influence:
investment risk
long-term returns
cash flow
financial stability
market exposure
wealth growth
The right balance depends on a person’s goals, time frame and tolerance for risk.
Asset allocation and property
Property is often a major part of many Australians’ asset allocation strategy.
Some people focus heavily on property, while others prefer a broader mix of investments to spread risk and improve flexibility.
Diversifying assets may help reduce exposure to any single market or economic event.
Things to consider
Asset allocation may change over time depending on:
age and life stage
income and cash flow
market conditions
debt levels
financial goals
risk comfort
There is no one-size-fits-all strategy.
Property decisions should be made with strategy, not panic.
Key Insight
Asset allocation is not simply about owning multiple assets.
It is about building a balanced financial position that aligns with your long-term goals and risk profile.
Understanding your position is the first step.


Wealth & Investment
Bear Market
A bear market is a period where asset prices fall over an extended time and market confidence weakens.
Bear markets are commonly associated with shares and investment markets, but they can also affect property, business activity and broader economic confidence.
In simple terms
A bear market usually means:
prices are falling
buyers become more cautious
confidence weakens
investment activity slows
uncertainty increases
People may hold back on spending, borrowing or investing while waiting to see what happens next.
Why bear markets matter
Bear markets can affect:
investment portfolios
borrowing confidence
consumer sentiment
business activity
property demand
lending conditions
They can also create opportunities for long-term investors who are financially prepared.
Bear markets and property
Property markets may slow during bearish conditions because buyers and investors become more cautious.
This can lead to:
longer selling times
reduced competition
softer price growth
lower transaction volumes
However, not all markets respond the same way. Some regions or property types may remain resilient due to supply shortages, population growth or local demand.
Things to consider
During uncertain markets, many people focus on:
protecting cash flow
maintaining financial buffers
reviewing debt levels
avoiding emotional decisions
focusing on long-term strategy
Property decisions should be made with strategy, not panic.
Key Insight
Bear markets are a normal part of long-term economic and investment cycles.
Periods of uncertainty can create both risks and opportunities depending on your financial position and strategy.
Understanding your position is the first step.


Banking & Finance
Blue Chip Investment
A blue chip investment generally refers to a well-established, financially stable asset or company with a strong long-term reputation.
Blue chip investments are often viewed as more stable and lower risk compared to speculative or emerging investments.
In simple terms
Blue chip investments are usually associated with:
established businesses
consistent performance
strong market reputation
long operating history
reliable income potential
In property, blue chip assets are often located in highly desirable areas with strong long-term demand.
Why blue chip investments matter
Blue chip investments may provide:
greater long-term stability
lower volatility
stronger confidence during uncertain markets
consistent income potential
long-term capital growth opportunities
They are commonly used as part of a long-term wealth-building strategy.
Blue chip property
Blue chip property is often linked to:
premium locations
strong infrastructure
high owner-occupier demand
limited supply
long-term desirability
These markets may hold value more strongly during changing economic conditions, although no investment is completely risk-free.
Things to consider
Blue chip investments may still experience:
market downturns
changing economic conditions
interest rate impacts
periods of slower growth
They can also require larger entry costs due to strong demand and premium positioning.
Property decisions should be made with strategy, not panic.
Key Insight
A blue chip investment is not about chasing quick wins.
It is usually focused on quality, stability and long-term performance over time.
Understanding your position is the first step.


Wealth & Investment
Bull Market
A bull market is a period where asset prices are generally rising and market confidence is strong.
Bull markets are commonly associated with shares, property and investment markets during periods of economic growth and positive sentiment.
In simple terms
A bull market usually means:
prices are increasing
buyer confidence improves
investment activity rises
demand strengthens
optimism grows
People are generally more willing to spend, borrow and invest during strong market conditions.
Why bull markets matter
Bull markets can affect:
investment portfolios
borrowing confidence
property demand
business activity
consumer spending
market competition
Strong confidence can lead to increased transaction activity and rising asset values.
Bull markets and property
Property markets often become more active during bullish conditions.
This may lead to:
stronger buyer demand
increased competition
faster sales
rising property prices
higher investor activity
However, rapidly rising markets can also create affordability pressure and emotional decision-making.
Things to consider
Even during strong markets, it is important to focus on:
financial sustainability
cash flow
debt management
long-term strategy
avoiding overextending financially
Property decisions should be made with strategy, not panic.
Key Insight
Bull markets can create confidence and opportunity, but strong markets still carry risk if decisions are made emotionally or without planning.
Understanding your position is the first step.


Banking & Finance
Capital Gains Tax (CGT)
Capital Gains Tax, commonly called CGT, is the tax that may apply when you make a profit from selling an asset.
This can include:
investment property
shares
businesses
cryptocurrency
other investments
In Australia, CGT is generally considered part of your income tax rather than a separate tax.
In simple terms
If you buy an asset and later sell it for more than you paid, the profit may be considered a capital gain.
The difference between:
the purchase price, and
the sale price
may be subject to tax after allowable costs and adjustments are considered.
Why CGT matters
Capital Gains Tax can affect:
investment returns
property sale profits
business sales
long-term wealth strategies
timing of asset sales
Understanding potential tax outcomes can help investors plan more effectively.
CGT and property
CGT commonly applies to:
investment properties
holiday homes
commercial property
development sites
However, the family home (principal place of residence) may qualify for exemptions in certain situations.
Things to consider
CGT outcomes can depend on factors such as:
how long the asset was held
ownership structure
improvements and costs
personal tax position
whether exemptions apply
In many cases, assets held longer than 12 months may qualify for CGT discounts under Australian tax rules.
Important note
Tax laws can be complex and may change over time.
Always seek professional accounting or taxation advice before making financial or property decisions involving Capital Gains Tax.
Key Insight
Capital Gains Tax is not simply about selling for a profit.
It is about understanding how asset growth, timing and structure can impact your overall financial position.
Understanding your position is the first step.


Wealth & Investment
Capital Growth
Capital growth refers to the increase in the value of an asset over time.
In property and investing, it usually describes how much an asset has increased in value since it was purchased.
In simple terms
If you buy an asset for one price and it becomes worth more in the future, the increase in value is known as capital growth.
For example:
Buy a property for $500,000
Property value later increases to $650,000
Capital growth = $150,000
Why capital growth matters
Capital growth can help build:
long-term wealth
usable equity
borrowing power
financial flexibility
future investment opportunities
Many investors focus on capital growth as part of a long-term strategy rather than short-term cash flow alone.
Capital growth and property
Property capital growth is often influenced by:
location
supply and demand
infrastructure
population growth
economic conditions
buyer confidence
Different suburbs and property types can perform very differently over time.
Bundaberg is not one market. Different areas behave like different products.
Things to consider
Capital growth is not guaranteed.
Markets move through cycles and values can rise or fall depending on changing conditions.
It is important to consider:
holding costs
cash flow
market timing
long-term strategy
risk tolerance
Property decisions should be made with strategy, not panic.
Key Insight
Capital growth is not simply about rising prices.
It is about how asset value growth can strengthen your long-term financial position over time.
Understanding your position is the first step.


Banking & Finance
Cash-on-Cash Return
Cash-on-cash return is a property investment measurement used to compare the annual cash income generated by an investment against the actual cash invested into the deal.
It is commonly used by investors to assess how efficiently their invested cash is performing.
In simple terms
Cash-on-cash return looks at:
how much cash you invested, and
how much cash the property returns each year
For example:
Total cash invested: $100,000
Annual positive cash flow: $10,000
Cash-on-cash return: 10%
Why cash-on-cash return matters
This measurement can help investors understand:
cash flow performance
investment efficiency
return on invested capital
income potential
portfolio performance
It is often used when comparing multiple investment opportunities.
Cash-on-cash return and property
Cash-on-cash return is commonly influenced by:
rental income
loan repayments
interest rates
operating expenses
vacancy rates
purchase costs
leverage
Different properties may produce very different cash-on-cash returns depending on their location, debt structure and holding costs.
Things to consider
A high cash-on-cash return does not always mean a better long-term investment.
It is important to also consider:
capital growth potential
market conditions
asset quality
long-term demand
risk levels
maintenance costs
Some investments prioritise strong cash flow, while others focus more heavily on long-term growth.
Property decisions should be made with strategy, not panic.
Key Insight
Cash-on-cash return is not just about rental income.
It is about understanding how effectively your invested cash is working within the overall investment strategy.
Understanding your position is the first step.


Wealth & Investment
Compound Growth
Compound growth refers to growth that builds on previous growth over time.
In investing and property, it means returns are generated not only on the original investment, but also on the gains already achieved.
In simple terms
Compound growth is often described as “growth on growth.”
For example:
an asset increases in value,
then future growth occurs on the higher value,
allowing growth to accelerate over time.
The longer the time frame, the more powerful compound growth can become.
Why compound growth matters
Compound growth can help:
build long-term wealth
increase equity faster
strengthen investment portfolios
improve future borrowing power
create larger long-term returns
Time is one of the biggest drivers behind compound growth.
Compound growth and property
Property investors often use compound growth through:
long-term capital growth
reinvesting equity
portfolio expansion
debt reduction over time
rental income growth
Even moderate annual growth can create significant differences over longer periods.
Things to consider
Compound growth is not guaranteed and markets move through cycles.
Factors that may influence long-term growth include:
location quality
supply and demand
economic conditions
interest rates
holding costs
time in the market
Many investors focus on long-term consistency rather than short-term market movements.
Property decisions should be made with strategy, not panic.
Key Insight
Compound growth is not about getting rich quickly.
It is about allowing time, consistency and asset growth to work together over the long term.
Understanding your position is the first step.


Banking & Finance
Cryptocurrency
Cryptocurrency is a type of digital asset that uses blockchain technology and cryptography to record and verify transactions.
Unlike traditional currencies, cryptocurrencies are generally decentralised and are not controlled by a central bank or government.
In simple terms
Cryptocurrency exists digitally rather than physically.
People may use cryptocurrency for:
investing
transferring value
trading
online transactions
diversification strategies
Some of the more widely known cryptocurrencies include Bitcoin and Ethereum.
Why cryptocurrency matters
Cryptocurrency markets can influence:
investment sentiment
risk appetite
portfolio diversification
global financial discussions
wealth creation opportunities
The sector has grown significantly over recent years, although it remains highly volatile.
Cryptocurrency and investing
Many investors view cryptocurrency as a speculative or high-risk asset due to large price movements and changing regulations.
Potential benefits may include:
strong growth potential
accessibility
diversification opportunities
However, risks may include:
extreme volatility
rapid market corrections
regulatory uncertainty
cybersecurity risks
liquidity concerns
Things to consider
Cryptocurrency is not guaranteed to increase in value.
Before investing, it is important to consider:
your risk tolerance
investment time frame
financial position
portfolio diversification
security and storage methods
Many investors only allocate a portion of their portfolio to higher-risk assets.
Property decisions should be made with strategy, not panic.
Key Insight
Cryptocurrency is not simply about chasing fast returns.
It is a highly volatile asset class that should be understood properly before becoming part of any investment strategy.
Understanding your position is the first step.


Wealth & Investment
Defensive Asset
A defensive asset is an investment that is generally designed to provide greater stability and lower risk during changing market conditions.
Defensive assets are often used to help protect capital, reduce volatility and provide more predictable returns over time.
In simple terms
Defensive assets are usually focused on stability rather than aggressive growth.
Common defensive assets may include:
cash
savings accounts
term deposits
bonds
some income-focused investments
These assets are often less volatile than growth-focused investments such as shares or cryptocurrency.
Why defensive assets matter
Defensive assets can help:
reduce portfolio risk
provide financial stability
improve cash flow reliability
preserve capital
balance investment portfolios
Many investors use defensive assets to create a more balanced long-term strategy.
Defensive assets and investing
Defensive assets are commonly used during:
uncertain economic conditions
market downturns
retirement planning
risk management strategies
While defensive assets may offer lower potential returns, they can help reduce exposure to sharp market swings.
Things to consider
Defensive assets may still carry risks, including:
inflation reducing purchasing power
lower long-term growth potential
interest rate impacts
reduced returns compared to growth assets during strong markets
The right balance between defensive and growth assets depends on:
financial goals
risk tolerance
age and life stage
investment time frame
cash flow needs
Property decisions should be made with strategy, not panic.
Key Insight
Defensive assets are not about chasing maximum returns.
They are about creating stability, flexibility and risk management within a broader financial strategy.
Understanding your position is the first step.


Banking & Finance
Depreciation
Depreciation refers to the reduction in value of an asset over time due to age, wear, use or obsolescence.
In property investing, depreciation is commonly used to describe the decline in value of building components, fixtures and fittings for taxation purposes.
In simple terms
Certain property assets may lose value as they age or are used over time.
Examples can include:
carpets
appliances
air conditioning systems
blinds
hot water systems
building structures
In many cases, eligible depreciation may be claimed as a tax deduction by investment property owners.
Why depreciation matters
Depreciation may help investors:
reduce taxable income
improve cash flow
increase after-tax returns
better understand property holding costs
It is often an important part of property investment strategy and financial planning.
Depreciation and property
Property depreciation is commonly divided into two areas:
building depreciation (capital works)
plant and equipment depreciation
Newer properties may sometimes provide higher depreciation benefits due to newer fixtures and construction costs.
Things to consider
Depreciation rules can be complex and may change over time.
Factors that may affect depreciation include:
property age
renovation history
asset types
ownership structure
taxation legislation
Many investors obtain a professional depreciation schedule prepared by a qualified quantity surveyor.
Important note
Depreciation outcomes vary depending on personal circumstances and current tax legislation.
Always seek professional accounting or taxation advice before relying on depreciation estimates or strategies.
Key Insight
Depreciation is not simply about assets losing value.
It can also play an important role in improving cash flow and long-term investment performance when structured properly.
Understanding your position is the first step.


Wealth & Investment
Diversification
Diversification refers to spreading investments across different asset types, industries or markets to help reduce overall risk.
The idea is to avoid relying too heavily on a single investment or market.
In simple terms
Diversification is often described as:
“Not putting all your eggs in one basket.”
An investor may diversify across:
property
shares
cash
bonds
businesses
different locations or industries
Different assets often perform differently under changing market conditions.
Why diversification matters
Diversification may help:
reduce investment risk
smooth portfolio performance
improve financial stability
reduce exposure to market downturns
create broader opportunities
If one investment performs poorly, other assets may help balance the overall portfolio.
Diversification and property
Property investors may diversify by:
owning different property types
investing in different locations
balancing growth and income assets
combining property with other investments
Different suburbs, regions and property sectors can behave very differently over time.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Diversification does not remove risk completely.
It is still important to consider:
asset quality
cash flow
debt levels
market conditions
long-term strategy
investment goals
Too much diversification can also become difficult to manage or dilute performance.
Property decisions should be made with strategy, not panic.
Key Insight
Diversification is not simply about owning more assets.
It is about building a balanced financial position designed to manage risk while creating long-term opportunity.
Understanding your position is the first step.


Banking & Finance
Dividend
A dividend is a payment made by a company to its shareholders from profits earned by the business.
Dividends are commonly associated with shares and investments that generate regular income.
In simple terms
When a company makes a profit, it may choose to:
reinvest the money back into the business, or
distribute part of the profit to shareholders as a dividend.
Investors who own shares in the company may receive these payments regularly.
Why dividends matter
Dividends can help investors:
generate passive income
improve cash flow
build long-term wealth
reinvest earnings for compound growth
create portfolio stability
Some investors focus heavily on dividend income as part of their financial strategy.
Dividends and investing
Dividend-paying investments are often linked to:
established businesses
blue chip companies
income-focused portfolios
retirement strategies
Some companies pay consistent dividends over long periods, while others may reduce or stop dividends depending on business conditions.
Things to consider
Dividend income is not guaranteed.
Factors that may affect dividends include:
company profitability
economic conditions
market performance
business debt levels
company strategy
It is also important to consider:
capital growth potential
taxation implications
diversification
long-term investment goals
Property decisions should be made with strategy, not panic.
Key Insight
Dividends are not simply about receiving income.
They can form part of a broader long-term strategy focused on cash flow, stability and wealth creation over time.
Understanding your position is the first step.


Wealth & Investment
Equities
Equities refer to ownership in a company, usually through shares or stock.
When you own equities, you own a portion of that business and may benefit from its growth, profits and performance over time.
In simple terms
Buying equities means investing in a company.
If the company performs well, investors may benefit through:
rising share prices
dividend income
long-term capital growth
If the company performs poorly, the value of the investment may fall.
Why equities matter
Equities are commonly used to help:
build long-term wealth
generate investment returns
create dividend income
diversify portfolios
participate in business growth
Over the long term, equities have historically been viewed as growth-focused investments.
Equities and investing
Equities can include investments in:
Australian companies
international companies
blue chip businesses
growth companies
exchange traded funds (ETFs)
Different equities carry different levels of risk, volatility and growth potential.
Things to consider
Equity markets can move up and down quickly depending on:
economic conditions
company performance
interest rates
investor sentiment
global events
Before investing in equities, it is important to consider:
risk tolerance
diversification
investment time frame
cash flow needs
long-term strategy
Property decisions should be made with strategy, not panic.
Key Insight
Equities are not simply about buying shares.
They are about participating in business ownership and long-term economic growth while balancing opportunity and risk.
Understanding your position is the first step.


Banking & Finance
ETF
ETF stands for Exchange Traded Fund.
An ETF is an investment fund that holds a collection of assets and is bought and sold on a stock exchange, similar to shares.
ETFs are commonly used to gain exposure to multiple investments through a single purchase.
In simple terms
Instead of buying one individual company or asset, an ETF may hold:
shares
bonds
commodities
property-related investments
international markets
entire stock indexes
This allows investors to spread their money across many investments at once.
Why ETFs matter
ETFs are often used to help:
diversify investments
reduce concentration risk
simplify investing
access global markets
build long-term portfolios
Many investors use ETFs as part of a long-term wealth-building strategy.
ETFs and investing
Different ETFs focus on different investment areas, including:
Australian shares
international shares
dividend income
technology sectors
property markets
defensive assets
Some ETFs focus on growth, while others focus on income or stability.
Things to consider
ETFs still carry investment risk and values can rise or fall.
Factors that may affect ETF performance include:
market conditions
economic trends
interest rates
global events
the assets held within the ETF
It is important to understand:
what the ETF invests in
management fees
risk levels
investment goals
time frame
Property decisions should be made with strategy, not panic.
Key Insight
ETFs are not simply about convenience.
They are designed to provide broader market exposure, diversification and flexibility within an investment strategy.
Understanding your position is the first step.


Wealth & Investment
Franking Credits
Franking credits are tax credits attached to dividends paid by Australian companies that have already paid company tax on their profits.
They are designed to help reduce the effect of double taxation on company profits distributed to shareholders.
In simple terms
When an Australian company earns a profit, it may first pay company tax.
If the company then pays a dividend to shareholders, franking credits may be attached to show tax has already been paid on that income.
This can provide tax benefits to eligible investors depending on their personal tax situation.
Why franking credits matter
Franking credits may help investors:
improve after-tax returns
increase investment income
reduce personal tax payable
support retirement income strategies
improve dividend investment performance
They are commonly associated with Australian share investments.
Franking credits and investing
Franking credits are often important for investors focused on:
dividend income
long-term wealth building
retirement planning
Australian share portfolios
passive income strategies
Some investors specifically seek fully franked dividends as part of their investment approach.
Things to consider
Franking credit outcomes can depend on:
personal tax position
ownership structure
tax residency
current tax legislation
the company’s dividend policy
Not all dividends are fully franked, and taxation rules may change over time.
Important note
Franking credits and taxation rules can be complex.
Always seek professional accounting or taxation advice before making financial or investment decisions.
Key Insight
Franking credits are not simply extra income.
They are part of Australia’s taxation system designed to improve the efficiency of dividend investing and long-term investment returns.
Understanding your position is the first step.


Banking & Finance
Gross Yield
Gross yield is a measurement used to estimate the income return generated by an investment property before expenses are deducted.
It is commonly used by property investors to compare rental performance between different properties or locations.
In simple terms
Gross yield compares:
the annual rental income, against
the property’s purchase price or value.
The calculation is generally:
Annual Rent ÷ Property Value × 100
For example:
Annual rent: $31,200
Property value: $600,000
Gross yield: 5.2%
Why gross yield matters
Gross yield can help investors:
compare investment properties
assess rental performance
identify cash flow opportunities
understand market conditions
balance growth and income strategies
Higher gross yields may indicate stronger rental income relative to property value.
Gross yield and property
Gross yield can vary depending on:
location
property type
rental demand
vacancy rates
market conditions
purchase price
Some areas may offer higher yields but lower long-term growth, while others may focus more heavily on capital growth.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Gross yield does not include expenses such as:
rates
insurance
maintenance
management fees
vacancy periods
loan repayments
Because of this, gross yield should not be relied on alone when assessing an investment.
Many investors also review net yield, cash flow and long-term growth potential.
Property decisions should be made with strategy, not panic.
Key Insight
Gross yield is not simply about chasing the highest percentage.
It is about understanding how rental income fits within the broader investment strategy, risk profile and long-term goals.
Understanding your position is the first step.


Wealth & Investment
Growth Asset
A growth asset is an investment that is primarily focused on increasing in value over time rather than generating stable short-term income.
Growth assets are commonly used in long-term wealth-building strategies.
In simple terms
Growth assets are investments that aim to produce capital growth.
Common growth assets may include:
property
shares
equities
growth-focused managed funds
some ETFs
businesses
These assets are usually expected to increase in value over the long term, although prices may move up and down along the way.
Why growth assets matter
Growth assets may help investors:
build long-term wealth
increase equity
grow investment portfolios
improve future financial flexibility
outperform inflation over time
Many investors use growth assets to strengthen their long-term financial position.
Growth assets and investing
Growth assets are often associated with:
higher potential returns
longer investment time frames
market volatility
economic growth
compounding wealth strategies
While growth assets may experience short-term fluctuations, investors often focus on long-term performance rather than short-term movements.
Things to consider
Growth assets can also carry higher risk and volatility.
Factors that may affect performance include:
market conditions
economic cycles
interest rates
investor confidence
global events
Before investing, it is important to consider:
risk tolerance
time frame
diversification
cash flow needs
long-term goals
Property decisions should be made with strategy, not panic.
Key Insight
Growth assets are not simply about chasing rising prices.
They are about using long-term asset growth to build wealth, flexibility and future opportunity over time.
Understanding your position is the first step.


Banking & Finance
Hedging
Hedging is a strategy used to help reduce or manage financial risk.
Investors and businesses use hedging to protect themselves against potential losses caused by changing market conditions, interest rates, currency movements or asset prices.
In simple terms
Hedging is similar to creating a financial safety buffer.
The goal is not usually to maximise profits.
The goal is to help reduce the impact of unexpected market movements.
Examples of hedging may include:
diversifying investments
fixing interest rates
holding defensive assets
using insurance
balancing different asset types
Why hedging matters
Hedging may help:
reduce portfolio risk
improve financial stability
protect against volatility
manage uncertainty
improve long-term planning
Many investors and businesses use hedging strategies during uncertain economic conditions.
Hedging and investing
Hedging strategies are commonly used in:
property investing
share portfolios
business operations
foreign currency exposure
interest rate management
For example, some borrowers choose fixed-rate loans to hedge against rising interest rates.
Things to consider
Hedging does not remove risk completely.
In some situations, hedging may:
reduce potential profits
increase costs
limit flexibility
add complexity
The right strategy depends on:
risk tolerance
investment goals
market conditions
time frame
financial position
Property decisions should be made with strategy, not panic.
Key Insight
Hedging is not about eliminating uncertainty.
It is about creating strategies that help manage risk and improve financial stability over time.
Understanding your position is the first step.


Wealth & Investment
Income-Producing Asset
An income-producing asset is an investment that generates regular income while you own it.
The income may come from rent, dividends, interest or business earnings depending on the type of asset.
In simple terms
Income-producing assets are designed to provide cash flow.
Common examples include:
investment properties
dividend-paying shares
bonds
term deposits
commercial property
businesses
These assets may generate ongoing income while also potentially increasing in value over time.
Why income-producing assets matter
Income-producing assets may help:
improve cash flow
build passive income
support retirement planning
increase financial stability
create long-term wealth
Many investors use income-producing assets to help cover living costs or reinvest income into future growth.
Income-producing assets and investing
Different income-producing assets generate income in different ways.
For example:
property may generate rental income
shares may pay dividends
bonds may pay interest
businesses may produce profits
Some assets focus more heavily on stable income, while others combine income with capital growth potential.
Things to consider
Income is not always guaranteed and may change over time.
Factors that may affect income include:
vacancy rates
market conditions
business performance
interest rates
maintenance costs
economic conditions
It is also important to consider:
risk levels
diversification
cash flow needs
taxation implications
long-term goals
Property decisions should be made with strategy, not panic.
Key Insight
Income-producing assets are not simply about generating cash flow.
They are about creating financial stability, flexibility and long-term opportunity through consistent income generation.
Understanding your position is the first step.


Banking & Finance
Leverage
Leverage refers to using borrowed money to increase the size of an investment.
In property and investing, leverage is commonly used to gain exposure to larger assets while using less of your own cash upfront.
In simple terms
Leverage allows investors to control a larger asset using a combination of:
their own money, and
borrowed funds.
For example:
an investor may contribute a deposit,
while a lender provides the remaining funds through a loan.
If the asset increases in value, the returns on the investor’s original cash contribution may also increase.
Why leverage matters
Leverage may help investors:
enter markets sooner
build wealth faster
increase purchasing power
grow investment portfolios
improve long-term opportunities
Leverage is one of the main reasons property investing can create significant long-term wealth growth.
Leverage and property
Property investors commonly use leverage through:
home loans
investment loans
equity access
refinancing
portfolio expansion
As property values increase, investors may build equity that can potentially be used to assist with future investments.
Things to consider
Leverage can increase both gains and losses.
Risks may include:
higher debt levels
increased repayment pressure
rising interest rates
market downturns
cash flow stress
Before using leverage, it is important to consider:
serviceability
risk tolerance
income stability
long-term goals
market conditions
Property decisions should be made with strategy, not panic.
Key Insight
Leverage is not simply about borrowing more money.
It is about using debt strategically to create opportunities while carefully managing risk and financial stability.
Understanding your position is the first step.


Wealth & Investment
Managed Fund
A managed fund is an investment where money from multiple investors is pooled together and managed by a professional fund manager.
The fund manager invests the money into assets such as shares, property, bonds or other investments on behalf of investors.
In simple terms
Instead of selecting and managing investments yourself, a managed fund allows a professional manager to make investment decisions for the fund.
A managed fund may invest in:
shares
property
bonds
infrastructure
international markets
mixed investment portfolios
Investors own units in the fund rather than directly owning the underlying assets.
Why managed funds matter
Managed funds may help investors:
diversify investments
access professional management
reduce complexity
gain exposure to larger markets
build long-term wealth
Many investors use managed funds as part of a broader investment strategy.
Managed funds and investing
Different managed funds focus on different goals, including:
growth
income
balanced investing
defensive investing
property exposure
Some funds focus on higher growth potential, while others focus more heavily on stability and income generation.
Things to consider
Managed funds still carry investment risk.
Factors that may affect performance include:
market conditions
management decisions
fees and costs
economic conditions
asset selection
investment time frame
Before investing, it is important to understand:
the fund strategy
risk levels
management fees
withdrawal conditions
long-term goals
Property decisions should be made with strategy, not panic.
Key Insight
Managed funds are not simply about handing money to someone else.
They are about accessing diversified investments and professional management as part of a long-term financial strategy.
Understanding your position is the first step.


Banking & Finance
Margin Loan
A margin loan is a type of loan used to borrow money for investing, usually into shares or managed funds.
It allows investors to increase their purchasing power by combining their own money with borrowed funds.
In simple terms
A margin loan works similarly to leverage.
An investor contributes part of the investment themselves, while the lender provides the remaining funds.
For example:
you invest your own money,
borrow additional funds,
and purchase a larger investment portfolio.
If the investment increases in value, returns may be amplified.
However, losses can also increase if the market falls.
Why margin loans matter
Margin loans may help investors:
increase market exposure
grow investment portfolios faster
access leverage opportunities
potentially improve long-term returns
Some investors use margin loans as part of aggressive growth strategies.
Margin loans and investing
Margin loans are commonly used for investments such as:
shares
managed funds
ETFs
diversified investment portfolios
The investment itself is usually used as security for the loan.
Things to consider
Margin loans carry significant risk.
Risks may include:
amplified losses
interest costs
market volatility
margin calls
forced asset sales
A margin call may occur if the value of the investment falls below the lender’s required level, requiring the investor to contribute more funds or sell assets.
Before using a margin loan, it is important to consider:
risk tolerance
financial stability
investment experience
cash flow position
long-term strategy
Property decisions should be made with strategy, not panic.
Key Insight
Margin loans are not simply about increasing investment size.
They are a high-risk leverage strategy that can magnify both gains and losses and should be approached carefully.
Understanding your position is the first step.


Wealth & Investment
Market Correction
A market correction is when the market pulls back after prices have risen too quickly.
It is a normal part of investment and property market cycles and may involve:
slower price growth,
reduced buyer activity,
longer selling times,
or moderate price declines.
In simple terms
Markets do not move up forever.
Sometimes prices rise too fast, affordability tightens, or buyer confidence slows — causing the market to reset and stabilise.
For example:
buyers may become more cautious,
borrowing power may reduce,
competition may ease,
and sellers may need to adjust expectations.
A correction does not automatically mean a crash.
Why market corrections matter
Market corrections can:
create buying opportunities,
reduce emotional competition,
improve negotiation conditions,
and expose overleveraged positions.
For strategic buyers and investors, corrections can sometimes create opportunity.
Market corrections and property
Property markets rarely move evenly.
Some areas may soften while others remain strong due to:
supply shortages,
migration,
affordability,
local employment,
and housing demand.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
During a correction, it is important to understand:
your cash flow,
debt levels,
holding ability,
risk tolerance,
and long-term strategy.
Property decisions should be made with strategy, not panic.
Key Insight
A market correction is often the market rebalancing itself after periods of strong growth — not the end of the market.
Understanding your position is the first step.


Banking & Finance
Negative Gearing
Negative gearing is when the costs of owning an investment asset are higher than the income it produces.
In property, this usually means the rental income does not fully cover expenses such as:
loan repayments,
interest,
maintenance,
insurance,
rates,
and other holding costs.
In simple terms
The investment runs at a short-term loss while the owner hopes the asset increases in value over time.
For example:
rental income may be lower than repayments,
the owner contributes extra money each week,
and future capital growth becomes part of the long-term strategy.
Why negative gearing matters
Negative gearing may help investors:
access larger assets,
build long-term wealth,
benefit from potential capital growth,
and potentially reduce taxable income.
Many investors use negative gearing as part of a long-term investment strategy rather than for immediate cash flow.
Negative gearing and property
Negative gearing is commonly associated with:
investment properties,
growth-focused suburbs,
higher-value assets,
and long-term wealth creation strategies.
Some investors accept short-term losses in exchange for potential long-term gains.
Things to consider
Negative gearing still carries financial risk.
Important considerations include:
cash flow pressure,
interest rate increases,
vacancy periods,
maintenance costs,
and market conditions.
An investment should not rely purely on future growth assumptions.
Property decisions should be made with strategy, not panic.
Key Insight
Negative gearing is not about losing money for the sake of tax benefits.
It is a strategy where investors accept short-term holding costs in pursuit of long-term asset growth and wealth creation.
Understanding your position is the first step.


Wealth & Investment
Net Yield
Net yield is the return an investment produces after expenses have been deducted.
In property investing, net yield measures how much income remains after costs such as:
rates,
insurance,
maintenance,
property management,
and other holding expenses.
In simple terms
Net yield shows the “real” income return of an investment — not just the rental income collected.
For example:
a property may have strong rental income,
but high expenses can reduce the actual return,
lowering the net yield.
Why net yield matters
Net yield may help investors:
compare investment performance,
understand true cash flow,
identify holding costs,
and assess long-term investment viability.
A higher rental income does not always mean a better investment if expenses are also high.
Net yield and property
Net yield is commonly used when assessing:
investment properties,
commercial assets,
rental portfolios,
and cash flow strategies.
Different property types may produce very different net yields depending on:
vacancy rates,
maintenance costs,
body corporate fees,
and local demand.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
When assessing net yield, it is important to understand:
total holding costs,
vacancy risk,
maintenance requirements,
rental demand,
and long-term growth potential.
Strong cash flow should still align with long-term strategy.
Property decisions should be made with strategy, not panic.
Key Insight
Net yield is about understanding what an investment actually returns after expenses — not just what it earns on paper.
Understanding your position is the first step.


Banking & Finance
Passive Income
Passive income is money earned regularly with limited ongoing day-to-day work.
It is commonly generated through investments or assets that continue producing income over time.
In simple terms
Passive income is designed to create cash flow even when you are not actively working for every dollar earned.
Examples may include:
rental income,
dividends from shares,
managed funds,
business distributions,
or interest from investments.
Why passive income matters
Passive income may help people:
build long-term wealth,
improve financial flexibility,
reduce reliance on wages,
support retirement goals,
and create additional cash flow.
Many investors aim to build multiple income streams over time.
Passive income and property
Property is one of the most common passive income strategies in Australia.
Investment properties may generate income through:
weekly rent,
long-term capital growth,
and equity creation.
Some investors focus on strong cash flow, while others focus on long-term growth potential.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Passive income investments still carry risk.
Important considerations include:
vacancy periods,
maintenance costs,
interest rates,
management expenses,
and market conditions.
Strong passive income strategies usually involve long-term planning and risk management.
Property decisions should be made with strategy, not panic.
Key Insight
Passive income is not about making money with no effort.
It is about building assets that can continue producing income and opportunity over time.
Understanding your position is the first step.


Wealth & Investment
Portfolio
A portfolio is a collection of investments or assets owned by an individual, business or investor.
A portfolio may include:
property,
shares,
ETFs,
managed funds,
cash,
or other investments.
In simple terms
A portfolio is the combination of assets working together to build income, growth or long-term wealth.
For example:
one investor may hold several investment properties,
another may combine property with shares and ETFs,
while others may focus on diversification across different asset types.
Why portfolios matter
Building a portfolio may help investors:
spread risk,
create multiple income streams,
build long-term wealth,
improve financial flexibility,
and reduce reliance on a single asset.
Different portfolios are built for different goals and risk levels.
Portfolio and property
Property is commonly used as part of a broader investment portfolio.
Some investors focus on:
cash flow,
capital growth,
passive income,
development opportunities,
or long-term asset accumulation.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
When building a portfolio, it is important to consider:
risk tolerance,
diversification,
cash flow,
debt levels,
time frame,
and long-term strategy.
Strong portfolios are usually built over time — not overnight.
Property decisions should be made with strategy, not panic.
Key Insight
A portfolio is not simply a collection of assets.
It is a strategy designed to create growth, income and long-term financial opportunity.
Understanding your position is the first step.


Banking & Finance
Positive Gearing
Positive gearing is when an investment produces more income than the total costs of holding it.
In property, this usually means the rental income is higher than expenses such as:
loan repayments,
interest,
rates,
insurance,
maintenance,
and management fees.
In simple terms
The investment generates surplus cash flow after expenses are paid.
For example:
rental income may exceed holding costs,
the owner receives additional income each week,
and the property may still grow in value over time.
Why positive gearing matters
Positive gearing may help investors:
improve cash flow,
reduce financial pressure,
build passive income,
increase borrowing flexibility,
and support long-term wealth strategies.
Many investors use positive gearing to strengthen financial stability and create additional income streams.
Positive gearing and property
Positive gearing is commonly associated with:
high-yield properties,
affordable investment markets,
strong rental demand,
and cash flow-focused strategies.
Some investors prioritise positive cash flow over rapid capital growth.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Positive gearing does not remove investment risk.
Important considerations include:
vacancy periods,
maintenance costs,
interest rate changes,
tenant demand,
and long-term growth potential.
Strong cash flow should still align with long-term strategy.
Property decisions should be made with strategy, not panic.
Key Insight
Positive gearing is about creating surplus income from an investment while still positioning for long-term financial growth.
Understanding your position is the first step.


Wealth & Investment
Return on Investment (ROI)
Return on Investment (ROI) is a way of measuring how profitable an investment is compared to the amount of money invested.
ROI helps investors understand whether an investment is producing a strong financial return.
In simple terms
ROI compares what you gained from an investment against what it cost you.
For example:
if an investment grows in value,
produces rental income,
or generates profit,
the ROI measures how effectively the money performed.
Why ROI matters
ROI may help investors:
compare investment opportunities,
measure profitability,
track performance over time,
and make more informed financial decisions.
A higher ROI generally means the investment generated a stronger return relative to its cost.
ROI and property
ROI is commonly used when assessing:
investment properties,
renovations,
developments,
commercial property,
and long-term wealth strategies.
ROI may include:
rental income,
capital growth,
equity gains,
and overall profitability.
Different suburbs, property types and strategies may produce very different returns.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
ROI should not be viewed in isolation.
Important considerations include:
holding costs,
risk levels,
vacancy periods,
finance costs,
tax implications,
and long-term growth potential.
Strong returns should still align with long-term strategy.
Property decisions should be made with strategy, not panic.
Key Insight
ROI is not just about how much money an investment makes.
It is about understanding how effectively your money is working for you over time.
Understanding your position is the first step.


Banking & Finance
Risk Profile
A risk profile is an assessment of how much financial risk an individual is comfortable taking when investing.
It helps determine which types of investments or strategies may be suitable based on a person’s:
financial position,
goals,
time frame,
and tolerance for market fluctuations.
In simple terms
A risk profile measures how comfortable someone is with the possibility of gains and losses.
For example:
some investors prefer stable, lower-risk assets,
while others are comfortable taking higher risks for potentially higher returns.
Why risk profiles matter
Understanding a risk profile may help investors:
choose suitable investments,
avoid unnecessary financial pressure,
manage market volatility,
build long-term strategies,
and make more confident decisions.
Different investors can respond very differently to the same market conditions.
Risk profiles and property
Risk profiles are commonly considered when assessing:
investment properties,
leverage levels,
development opportunities,
portfolio structures,
and growth strategies.
Some investors prioritise stability and cash flow, while others focus on aggressive growth.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Risk tolerance may change over time depending on:
income stability,
debt levels,
life stage,
financial goals,
and market conditions.
Higher potential returns often come with higher levels of risk.
Property decisions should be made with strategy, not panic.
Key Insight
A strong investment strategy should match your risk profile — not someone else’s.
Understanding your position is the first step.


Wealth & Investment
Shares
Shares represent ownership in a company.
When someone buys shares, they are purchasing a small portion of that business and may benefit from:
company growth,
dividend income,
and increases in share value.
In simple terms
Shares allow investors to participate in the performance of a business without owning the entire company.
For example:
if a company grows and becomes more profitable,
the value of its shares may increase,
and shareholders may receive dividend payments.
Why shares matter
Shares may help investors:
build long-term wealth,
generate passive income,
diversify investments,
and access growth opportunities.
Many investors use shares as part of a broader investment portfolio.
Shares and investing
Shares are commonly used for:
long-term investing,
dividend income,
retirement planning,
and wealth creation strategies.
Different shares may carry different levels of risk depending on:
company performance,
market conditions,
industry trends,
and economic factors.
Things to consider
Share markets can be volatile.
Important considerations include:
risk tolerance,
diversification,
investment time frame,
market conditions,
and long-term strategy.
Higher potential returns may also involve higher levels of risk.
Property decisions should be made with strategy, not panic.
Key Insight
Shares are not simply pieces of paper or numbers on a screen.
They represent ownership in businesses and can play a major role in long-term wealth creation when used strategically.
Understanding your position is the first step.


Banking & Finance
Speculative Asset
A speculative asset is an investment purchased mainly for the potential of high future returns rather than stable income or predictable performance.
Speculative assets are generally considered higher risk and may experience significant price volatility.
In simple terms
Speculative investing usually focuses on the possibility of rapid growth, even though the investment may also carry a higher chance of loss.
Examples may include:
cryptocurrencies,
small speculative shares,
early-stage businesses,
undeveloped land,
or high-risk growth investments.
Why speculative assets matter
Some investors use speculative assets to:
pursue high growth opportunities,
diversify investment strategies,
gain exposure to emerging industries,
and potentially achieve larger returns.
However, speculative assets can also experience rapid declines in value.
Speculative assets and investing
Speculative assets are commonly associated with:
aggressive growth strategies,
high market volatility,
uncertain future performance,
and shorter-term market speculation.
Some investors allocate only a small portion of their portfolio to speculative assets to manage risk.
Things to consider
Speculative assets can involve significant financial risk.
Important considerations include:
risk tolerance,
market volatility,
investment time frame,
financial stability,
and diversification.
Higher potential returns usually come with higher levels of uncertainty.
Property decisions should be made with strategy, not panic.
Key Insight
Speculative assets are not guaranteed wealth-building tools.
They are high-risk investments that should be approached carefully and balanced within a broader long-term strategy.
Understanding your position is the first step.


Wealth & Investment
Volatility
Volatility refers to how much and how quickly the value of an investment or market can rise or fall over time.
High volatility means prices move sharply and unpredictably, while low volatility usually means more stable price movements.
In simple terms
Volatility measures how unstable or unpredictable a market or investment may be.
For example:
share markets may rise and fall quickly,
cryptocurrencies may experience large price swings,
while some assets may remain relatively stable over time.
Why volatility matters
Understanding volatility may help investors:
manage risk,
prepare for market fluctuations,
make informed investment decisions,
and build long-term strategies.
Different assets can experience very different levels of volatility.
Volatility and investing
Volatility is commonly associated with:
shares,
cryptocurrencies,
speculative assets,
property markets,
and economic uncertainty.
Some investors are comfortable with higher volatility in pursuit of higher potential returns.
Things to consider
Volatility can create both opportunity and risk.
Important considerations include:
risk tolerance,
investment time frame,
diversification,
financial stability,
and long-term strategy.
Short-term market movements do not always reflect long-term value.
Property decisions should be made with strategy, not panic.
Key Insight
Volatility is not always negative.
It is a normal part of investing and financial markets, but understanding your risk exposure is critical.
Understanding your position is the first step.


Banking & Finance
Yield
Yield is the income return generated from an investment, usually shown as a percentage of the asset’s value.
In property, yield is commonly based on the rental income a property produces compared to its purchase price or market value.
In simple terms
Yield measures how much income an investment generates relative to what it costs.
For example:
a property with strong rental income may produce a higher yield,
while a lower-income property may produce a lower yield.
Why yield matters
Yield may help investors:
assess cash flow,
compare investment opportunities,
understand income performance,
and build long-term investment strategies.
Different investments can produce very different yield levels.
Yield and property
Yield is commonly used when assessing:
investment properties,
commercial assets,
rental portfolios,
and income-producing investments.
Some investors focus on:
high yield for stronger cash flow,
while others prioritise long-term capital growth.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Yield should not be viewed in isolation.
Important considerations include:
holding costs,
vacancy risk,
maintenance expenses,
market conditions,
and long-term growth potential.
A high yield does not always mean a low-risk investment.
Property decisions should be made with strategy, not panic.
Key Insight
Yield is about understanding how effectively an investment produces income — not just how much the asset is worth.
Understanding your position is the first step.


Wealth & Investment
Appraisal
An appraisal is an estimate of a property’s current market value based on recent sales, market conditions and the property’s features.
Real estate agents commonly provide appraisals to help owners understand where their property may sit in the current market.
In simple terms
An appraisal is a professional opinion of what a property could potentially sell for in today’s market.
An appraisal may consider:
recent comparable sales,
property condition,
location,
land size,
improvements,
and buyer demand.
Why appraisals matter
An appraisal may help owners:
understand their property position,
plan a future move,
assess equity opportunities,
prepare for sale,
and make more informed decisions.
Property markets can change over time, meaning property values may also change.
Appraisals and property strategy
Many owners seek appraisals when considering:
selling,
upgrading,
downsizing,
refinancing,
investment planning,
or development opportunities.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
An appraisal is not the same as a formal bank valuation.
Important factors may include:
market conditions,
buyer demand,
presentation,
timing,
and competition from similar properties.
Property decisions should be made with strategy, not panic.
Key Insight
An appraisal is not just about finding a price.
It is about understanding your position and exploring the opportunities available to you.
Understanding your position is the first step.


Property Ownership
Body Corporate
A body corporate is the legal entity responsible for managing and maintaining shared property within a community title or strata development.
This commonly applies to:
apartment complexes,
townhouses,
unit developments,
and some gated communities.
In simple terms
When you own a property within a body corporate, you usually own:
your individual lot or unit,
plus a shared interest in common areas such as driveways, gardens, lifts, pools or building structures.
Owners contribute fees to help cover the maintenance and management of these shared areas.
Why body corporates matter
Body corporates help manage:
maintenance of common property,
building insurance,
shared facilities,
administration,
and community rules or by-laws.
They are designed to help protect the presentation, operation and value of the development.
Body corporate and property ownership
Body corporate fees and rules can vary significantly between properties.
Important factors may include:
the size of the complex,
facilities provided,
maintenance requirements,
sinking fund balances,
and management quality.
Some developments may have low fees and simple structures, while others may involve significant ongoing costs.
Things to consider
Before purchasing a body corporate property, it is important to understand:
annual fees,
by-laws and restrictions,
sinking fund health,
insurance arrangements,
special levies,
and maintenance obligations.
Body corporate properties may suit some lifestyles and investment strategies more than others.
Property decisions should be made with strategy, not panic.
Key Insight
A body corporate is not just an extra fee.
It is part of the ownership structure and can significantly influence the costs, management and long-term appeal of a property.
Understanding your position is the first step.


Property Ownership
Building & Pest Inspection
A building and pest inspection is a professional assessment of a property’s condition before purchase.
It is designed to identify visible structural issues, defects, safety concerns and pest activity such as termites.
In simple terms
A building and pest inspection helps buyers better understand the condition of a property before committing to a purchase.
The inspection may identify issues such as:
structural movement,
water damage,
cracking,
roof defects,
drainage problems,
timber pests,
or maintenance concerns.
Why building & pest inspections matter
Building and pest inspections may help buyers:
reduce unexpected risks,
identify costly repairs,
negotiate with confidence,
understand maintenance requirements,
and make more informed decisions.
Some issues may not be obvious during a standard property inspection.
Building & pest inspections and property
Building and pest inspections are commonly used during:
residential purchases,
investment property purchases,
pre-auction due diligence,
and older property assessments.
Different properties may carry different risks depending on:
age,
construction type,
maintenance history,
location,
and environmental conditions.
Things to consider
A building and pest inspection is not a guarantee against future problems.
Important considerations may include:
the inspector’s scope,
visible versus hidden defects,
repair costs,
ongoing maintenance,
and specialist reports if required.
Property decisions should be made with strategy, not panic.
Key Insight
A building and pest inspection is not just about finding problems.
It is about understanding the condition of the asset and making informed decisions before moving forward.
Understanding your position is the first step.


Property Ownership
Comparable Sales
Comparable sales are recently sold properties used to help estimate the market value of another property.
They are commonly referred to as “comps” within the real estate industry.
In simple terms
Comparable sales help determine what buyers may be willing to pay for a property based on what similar properties have recently sold for.
Agents and valuers may compare factors such as:
location,
land size,
property condition,
bedrooms and bathrooms,
improvements,
and overall appeal.
Why comparable sales matter
Comparable sales may help owners and buyers:
understand market value,
price properties more accurately,
assess buyer demand,
negotiate with confidence,
and make more informed decisions.
The stronger and more relevant the comparable sales, the more reliable the pricing guidance may become.
Comparable sales and property
Comparable sales are commonly used during:
appraisals,
property valuations,
buyer research,
finance assessments,
and sales campaigns.
Different suburbs and property types may produce very different comparable results.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Not all comparable sales are equal.
Important considerations may include:
how recent the sale was,
whether the properties are truly similar,
market conditions at the time,
renovations or upgrades,
and buyer competition.
A single sale does not always define the market.
Property decisions should be made with strategy, not panic.
Key Insight
Comparable sales are not just numbers on a list.
They are one of the key tools used to understand how the market is currently valuing property.
Understanding your position is the first step.


Property Ownership
Community Title
Community title is a form of property ownership where individual owners hold their own lot or property, while also sharing ownership of common areas within the development.
It is commonly used for:
townhouse complexes,
unit developments,
gated communities,
and some master-planned estates.
In simple terms
A community title property usually includes:
private ownership of a home, unit or lot,
plus shared ownership of areas such as driveways, gardens, pools, lifts or recreation facilities.
Owners are generally part of a body corporate or community management structure.
Why community title matters
Community title developments help manage:
shared facilities,
maintenance responsibilities,
building insurance,
community rules,
and common property expenses.
They are designed to create structured management of shared living environments.
Community title and property ownership
Community title properties can vary significantly depending on:
the type of development,
shared facilities,
body corporate structure,
ongoing fees,
and management quality.
Some developments have minimal shared areas, while others include extensive facilities and higher ongoing costs.
Things to consider
Before purchasing a community title property, it is important to understand:
body corporate fees,
by-laws and restrictions,
insurance responsibilities,
maintenance obligations,
sinking fund balances,
and any planned future works.
Different community title properties may suit different lifestyles and investment goals.
Property decisions should be made with strategy, not panic.
Key Insight
Community title ownership is not just about the individual property.
It also involves shared responsibilities, shared costs and the long-term management of the broader development.
Understanding your position is the first step.


Property Ownership
Contract of Sale
A Contract of Sale is the legally binding agreement between a buyer and seller for the purchase of a property.
It sets out the terms and conditions of the transaction, including:
the purchase price,
deposit amount,
settlement date,
and any special conditions.
In simple terms
The contract outlines exactly what both parties are agreeing to before the property changes ownership.
Once signed by both parties, the contract may become legally binding depending on the conditions within the agreement.
Why contracts of sale matter
A Contract of Sale helps provide clarity and legal protection for both buyers and sellers.
It may outline:
finance conditions,
building and pest clauses,
settlement time frames,
inclusions and exclusions,
and buyer or seller obligations.
The contract becomes one of the most important documents in the transaction process.
Contracts of sale and property transactions
Contracts may vary depending on:
the property type,
state legislation,
special conditions,
and the structure of the transaction.
Different sales strategies such as auctions, private treaty sales or off-market transactions may also involve different contract conditions.
Things to consider
Before signing a Contract of Sale, it is important to understand:
all terms and conditions,
finance obligations,
cooling-off rights,
settlement requirements,
deposit conditions,
and any special clauses.
Legal or conveyancing advice is often recommended before proceeding.
Property decisions should be made with strategy, not panic.
Key Insight
A Contract of Sale is not just paperwork.
It is the legal framework that controls the property transaction and protects the interests of both parties.
Understanding your position is the first step.


Property Ownership
Conveyancing
Conveyancing is the legal and administrative process of transferring property ownership from one party to another.
It usually begins once a contract is signed and continues through to settlement.
In simple terms
Conveyancing helps manage the legal side of a property transaction.
A conveyancer or solicitor may assist with:
reviewing contracts,
conducting property searches,
managing legal documents,
coordinating settlement,
and ensuring ownership transfers correctly.
Why conveyancing matters
Conveyancing helps buyers and sellers:
understand their legal obligations,
reduce transaction risks,
manage deadlines,
complete settlement correctly,
and avoid costly mistakes.
Property transactions involve legal processes that must be handled accurately and on time.
Conveyancing and property transactions
Conveyancing is commonly involved in:
residential sales,
investment property purchases,
vacant land transactions,
commercial property,
and off-the-plan purchases.
Different transactions may involve different legal requirements and complexities.
Things to consider
Before choosing a conveyancer or solicitor, it is important to consider:
experience,
communication,
costs,
contract review services,
and settlement support.
Delays or errors in the conveyancing process may impact settlement time frames and legal obligations.
Property decisions should be made with strategy, not panic.
Key Insight
Conveyancing is not just paperwork.
It is the legal process that helps ensure a property transaction is completed correctly, securely and legally.
Understanding your position is the first step.


Property Ownership
Cooling-Off Period
A cooling-off period is a legally defined time frame that allows a buyer to cancel a property contract after signing, subject to the rules and conditions of the relevant state or territory.
It is designed to give buyers a short period to reconsider the purchase decision.
In simple terms
A cooling-off period provides buyers with limited time to:
review the contract,
seek legal or financial advice,
organise inspections,
and confirm they are comfortable proceeding.
If the buyer cancels during the cooling-off period, financial penalties or deductions may still apply depending on the legislation.
Why cooling-off periods matter
Cooling-off periods may help buyers:
reduce pressure,
avoid rushed decisions,
review important information,
and better understand their obligations.
Property transactions involve significant financial commitments, so understanding the contract is critical.
Cooling-off periods and property transactions
Cooling-off periods commonly apply to:
private treaty sales,
residential property purchases,
and some off-the-plan contracts.
They may not apply to:
auction purchases,
commercial property,
or certain contract structures.
Rules and time frames vary between states and territories.
Things to consider
Before relying on a cooling-off period, it is important to understand:
the exact time frame,
cancellation procedures,
potential penalties,
finance obligations,
and contract conditions.
Cooling-off rights are not designed to replace proper due diligence.
Property decisions should be made with strategy, not panic.
Key Insight
A cooling-off period is a short legal safety window — not a substitute for careful planning and professional advice.
Understanding your position is the first step.


Property Ownership
Covenant
A covenant is a legal condition or restriction placed on a property title that controls how the land can be used or developed.
Covenants are commonly used within residential estates and developments to help maintain certain standards or protect the character of an area.
In simple terms
A covenant may place rules or restrictions on a property owner.
For example, a covenant may control:
building sizes,
property appearance,
fencing styles,
secondary dwellings,
building materials,
or how the land can be used.
Why covenants matter
Covenants may help:
maintain neighbourhood presentation,
protect property values,
create consistency within developments,
and manage future land use outcomes.
They can significantly affect what an owner can and cannot do with a property.
Covenants and property ownership
Covenants are commonly found in:
new residential estates,
master-planned communities,
acreage developments,
and some older land titles.
Different properties may have very different covenant conditions.
Things to consider
Before purchasing a property, it is important to understand:
what restrictions apply,
whether approvals are required,
building limitations,
design guidelines,
and how the covenant may affect future plans.
Ignoring a covenant may create legal or financial issues.
Property decisions should be made with strategy, not panic.
Key Insight
A covenant is not just a minor title note.
It can directly affect how a property is used, developed and valued over the long term.
Understanding your position is the first step.


Property Ownership
Dual Key
A dual key property is a single property designed to function as two separate living spaces under one title.
It commonly includes:
one main residence,
plus a smaller secondary dwelling or unit,
with separate entrances and shared land ownership.
In simple terms
A dual key property allows two households to live independently within the same building structure.
For example:
a larger home may sit alongside a smaller studio or apartment,
often with separate kitchens, bathrooms and living areas.
Why dual key properties matter
Dual key properties may help owners and investors:
generate multiple income streams,
improve rental yield,
accommodate extended family,
create flexible living arrangements,
and maximise land use.
They are often viewed as a balance between traditional housing and dual occupancy investment strategies.
Dual key properties and investing
Dual key properties are commonly used for:
investment portfolios,
multi-generational living,
rental diversification,
and flexible occupancy strategies.
Some investors use dual key properties to potentially reduce vacancy risk by having two separate rental opportunities.
Things to consider
Before purchasing or building a dual key property, it is important to consider:
local council approvals,
zoning requirements,
finance conditions,
insurance implications,
tenant demand,
and future resale appeal.
Not all locations or developments allow dual key designs.
Bundaberg is not one market. Different suburbs are behaving like different products.
Property decisions should be made with strategy, not panic.
Key Insight
A dual key property is not simply a larger home.
It is a strategic property structure designed to create flexibility, multiple living options and potential income diversification.
Understanding your position is the first step.


Property Ownership
Dual Occupancy
Dual occupancy refers to two separate dwellings located on the same parcel of land.
The dwellings may be attached or detached, depending on the property design and local council regulations.
In simple terms
A dual occupancy property allows two homes to exist on one block.
For example:
a house and granny flat,
two attached townhouses,
or two separate dwellings on the same title.
Some dual occupancy properties remain on one title, while others may later be subdivided, subject to approvals.
Why dual occupancy matters
Dual occupancy properties may help owners and investors:
increase rental income,
maximise land use,
accommodate extended family,
create flexible living arrangements,
and potentially improve property value.
They are commonly used as part of long-term investment and development strategies.
Dual occupancy and property investing
Dual occupancy properties are commonly associated with:
rental yield strategies,
multi-generational living,
infill development,
and strategic land use opportunities.
Some investors use dual occupancy setups to diversify rental income across two dwellings instead of relying on a single tenant.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before developing or purchasing a dual occupancy property, it is important to consider:
zoning requirements,
council approvals,
infrastructure costs,
financing,
insurance,
tenant demand,
and future resale appeal.
Not all properties or locations are suitable for dual occupancy development.
Property decisions should be made with strategy, not panic.
Key Insight
Dual occupancy is not simply about fitting two homes onto one block.
It is a strategic property approach focused on flexibility, income potential and maximising land value.
Understanding your position is the first step.


Property Ownership
Easement
An easement is a legal right that allows someone else to use part of a property for a specific purpose, even though they do not own the land.
Easements are commonly used for:
access roads,
drainage,
sewer lines,
power infrastructure,
and shared services.
In simple terms
An easement creates a legal right over part of a property.
For example:
a neighbour may have legal access through part of the land,
or a utility provider may have rights to maintain underground infrastructure.
The landowner still owns the property, but certain restrictions or access rights may apply.
Why easements matter
Easements may affect:
how land can be used,
where buildings can be placed,
development potential,
access arrangements,
and future property value.
They are an important part of understanding a property’s legal and physical constraints.
Easements and property ownership
Easements are commonly found on:
residential properties,
acreage,
development land,
battle-axe blocks,
and rural properties.
Some easements are minor, while others can significantly impact property use and future development.
Things to consider
Before purchasing a property, it is important to understand:
the location of the easement,
who benefits from it,
restrictions on building over it,
maintenance responsibilities,
and how it may affect future plans.
A title search and survey plan may help identify easements affecting the property.
Bundaberg is not one market. Different suburbs are behaving like different products.
Property decisions should be made with strategy, not panic.
Key Insight
An easement is not necessarily a problem — but it is a legal constraint that should be properly understood before making property decisions.
Understanding your position is the first step.


Property Ownership
Encumbrance
An encumbrance is a legal claim, restriction or interest attached to a property that may affect its use, ownership or value.
Encumbrances can remain attached to the property title even when ownership changes.
In simple terms
An encumbrance is something that may limit how a property is used or create legal obligations for the owner.
Common examples may include:
easements,
covenants,
mortgages,
leases,
caveats,
or restrictions on use.
Why encumbrances matter
Encumbrances may affect:
development potential,
financing,
property access,
resale value,
and future property plans.
Some encumbrances are minor, while others can significantly impact a property.
Encumbrances and property ownership
Encumbrances are commonly identified during:
title searches,
conveyancing,
finance applications,
and due diligence investigations.
Different properties may carry very different legal restrictions or obligations.
Things to consider
Before purchasing a property, it is important to understand:
what encumbrances exist,
who benefits from them,
how they affect the land,
ongoing obligations,
and whether they may impact future plans or resale appeal.
Professional legal or conveyancing advice is often recommended.
Bundaberg is not one market. Different suburbs are behaving like different products.
Property decisions should be made with strategy, not panic.
Key Insight
An encumbrance is not automatically a problem — but it is a legal factor that should be fully understood before making property decisions.
Understanding your position is the first step.


Property Ownership
Equity
Equity is the difference between a property’s market value and the amount still owed on the loan secured against it.
As property values increase or loan balances reduce, equity may grow over time.
In simple terms
Equity represents the portion of the property that the owner effectively owns.
For example:
if a property is worth $800,000,
and the loan balance is $500,000,
the equity would be approximately $300,000.
Why equity matters
Equity may help property owners:
upgrade homes,
invest in additional property,
renovate,
refinance,
or improve financial flexibility.
Many homeowners are sitting on more opportunity than they realise.
Equity and property strategy
Some owners use equity as part of strategies involving:
investment property purchases,
sell-to-buy transitions,
debt restructuring,
renovations,
or long-term wealth building.
Usable equity may differ from total equity depending on lending policies and borrowing capacity.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Equity does not always mean accessible cash.
Important considerations may include:
borrowing capacity,
lender requirements,
interest rates,
existing debt levels,
and market conditions.
Property values may rise and fall over time.
Property decisions should be made with strategy, not panic.
Key Insight
Equity is not just a number on paper.
Used strategically, it can become a tool that helps create future opportunities and financial flexibility.
Understanding your position is the first step.
Property Ownership
Freehold
Freehold is a form of property ownership where the owner holds full ownership of both the land and any buildings on it, subject to laws and planning controls.
It is the most common form of property ownership in Australia.
In simple terms
Freehold ownership means the property owner generally has ongoing ownership rights over the land without a fixed expiry date.
The owner may have control over:
the home,
the land,
improvements,
and how the property is used, subject to council and legal requirements.
Why freehold matters
Freehold ownership may provide:
greater control over the property,
long-term ownership security,
flexibility for renovations or improvements,
and stronger land ownership rights.
Many traditional houses on individual lots are sold as freehold properties.
Freehold and property ownership
Freehold properties are commonly associated with:
detached houses,
residential land,
acreage properties,
and some commercial properties.
Freehold ownership differs from structures such as leasehold or some community title arrangements.
Things to consider
Even with freehold ownership, properties may still be affected by:
easements,
covenants,
zoning controls,
overlays,
and local planning regulations.
Ownership rights are not completely unrestricted.
Bundaberg is not one market. Different suburbs are behaving like different products.
Property decisions should be made with strategy, not panic.
Key Insight
Freehold ownership is not simply about owning a house.
It is about owning the land itself and the long-term control and opportunity that may come with it.
Understanding your position is the first step.


Property Ownership
Highest & Best Use
Highest and best use refers to the most valuable, legally permissible and financially viable use of a property or piece of land.
It is a common concept used in property valuation, development and strategic planning.
In simple terms
Highest and best use asks:
“What is the best possible use of this property based on its location, zoning, market demand and development potential?”
Sometimes the current use of a property may not be its most valuable use.
For example:
a large residential block may have subdivision potential,
an older house may suit redevelopment,
or a strategically located site may suit higher-density use.
Why highest and best use matters
Understanding highest and best use may help owners:
unlock hidden value,
identify development opportunities,
improve sale strategy,
attract different buyer types,
and make more informed long-term decisions.
Many homeowners are sitting on more opportunity than they realise.
Highest and best use and property strategy
Highest and best use is commonly considered during:
property appraisals,
development feasibility studies,
land acquisitions,
rezoning opportunities,
and investment planning.
Not every property’s highest and best use involves development. Sometimes the existing use is already the most suitable outcome.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Highest and best use may depend on:
zoning,
overlays,
infrastructure,
market demand,
access,
site dimensions,
and financial feasibility.
Potential does not always mean profitable or achievable.
Property decisions should be made with strategy, not panic.
Key Insight
Highest and best use is not about overdeveloping land.
It is about understanding the most appropriate and valuable long-term use of a property.
Understanding your position is the first step.


Property Ownership
Holding Costs
Holding costs are the ongoing expenses involved in owning a property over time.
They apply whether the property is owner-occupied, vacant, rented or being developed.
In simple terms
Holding costs are the expenses that continue while you hold the property.
Common holding costs may include:
loan repayments,
interest,
council rates,
insurance,
maintenance,
utilities,
body corporate fees,
and land tax where applicable.
Why holding costs matter
Holding costs may affect:
cash flow,
borrowing capacity,
investment returns,
development feasibility,
and financial pressure over time.
The longer a property is held, the more important holding costs may become.
Holding costs and property strategy
Holding costs are commonly considered during:
investment planning,
development projects,
renovations,
vacant land ownership,
and sell-to-buy transitions.
Some strategies may rely heavily on managing holding costs effectively during changing market conditions.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before purchasing or developing property, it is important to understand:
total monthly expenses,
interest rate exposure,
vacancy risk,
maintenance requirements,
and how long the property may need to be held.
Cash flow pressure can increase quickly if holding costs are underestimated.
Property decisions should be made with strategy, not panic.
Key Insight
Holding costs are not just small ongoing expenses.
Over time, they can significantly affect profitability, flexibility and long-term property decisions.
Understanding your position is the first step.


Property Ownership
Investment Property
An investment property is a property purchased primarily to generate income, capital growth or long-term financial returns.
Investment properties may include:
houses,
units,
townhouses,
commercial properties,
or vacant land.
In simple terms
An investment property is usually purchased to create financial benefit rather than being the owner’s main residence.
Returns may come from:
rental income,
property value growth,
or a combination of both.
Why investment properties matter
Investment properties may help investors:
build long-term wealth,
create passive income,
diversify investments,
improve financial flexibility,
and potentially access tax advantages.
Property remains one of the dominant wealth-building assets in Australian sentiment.
Investment properties and strategy
Different investment properties may suit different goals.
Some investors focus on:
cash flow,
capital growth,
development potential,
rental yield,
or long-term land value.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before purchasing an investment property, it is important to understand:
holding costs,
rental demand,
vacancy risk,
financing,
maintenance,
market conditions,
and long-term strategy.
Not all investment properties perform the same way.
Property decisions should be made with strategy, not panic.
Key Insight
An investment property is not simply about owning another property.
It is about using property strategically to create future opportunity, income and long-term financial growth.
Understanding your position is the first step.


Property Ownership
Leasehold
Leasehold is a form of property ownership where the buyer purchases the right to use and occupy a property or land for a fixed period of time under a lease agreement.
The land itself is usually owned by another party, often a government body, private owner or freehold owner.
In simple terms
With leasehold ownership:
you own the lease rights,
but not the underlying land itself.
The lease may run for a set number of years and often includes conditions, fees and obligations.
At the end of the lease term, ownership rights may expire unless the lease is renewed or extended.
Why leasehold matters
Leasehold properties may offer:
lower entry costs,
access to premium locations,
commercial opportunities,
and different investment structures.
However, leasehold ownership also involves additional considerations compared to freehold ownership.
Leasehold and property ownership
Leasehold arrangements are commonly associated with:
retirement villages,
some apartments,
commercial properties,
tourism developments,
marinas,
and government-owned land.
Different leasehold structures may have very different conditions and risks.
Things to consider
Before purchasing a leasehold property, it is important to understand:
remaining lease term,
annual fees or ground rent,
renewal rights,
restrictions,
financing conditions,
and resale appeal.
The value of a leasehold property may change as the lease term reduces over time.
Bundaberg is not one market. Different suburbs are behaving like different products.
Property decisions should be made with strategy, not panic.
Key Insight
Leasehold ownership is not the same as owning the land outright.
Understanding the lease structure, conditions and remaining term is critical before making a property decision.
Understanding your position is the first step.


Property Ownership
Market Value
Market value is the estimated price a property may reasonably sell for in the current market under normal conditions.
It reflects what a willing buyer may pay and what a willing seller may accept at a specific point in time.
In simple terms
Market value is influenced by:
buyer demand,
property condition,
location,
comparable sales,
market conditions,
and overall economic factors.
A property’s market value may change over time as market conditions shift.
Why market value matters
Understanding market value may help owners:
make informed selling decisions,
assess equity position,
refinance,
negotiate confidently,
and plan future property strategies.
Many homeowners are sitting on more opportunity than they realise.
Market value and property strategy
Market value is commonly considered during:
appraisals,
property sales,
refinancing,
investment decisions,
family law matters,
and development feasibility assessments.
Different buyers may place different values on the same property depending on their goals and circumstances.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Market value is not always the same as:
replacement cost,
council valuation,
insured value,
or personal opinion.
Factors such as presentation, timing, supply and demand, and buyer sentiment may significantly affect value.
Property decisions should be made with strategy, not panic.
Key Insight
Market value is not simply a number.
It is a reflection of what the market is prepared to pay at a specific point in time under current conditions.
Understanding your position is the first step.


Property Ownership
Owner Occupier
An owner occupier is a person who lives in the property they own as their primary residence, rather than renting it out as an investment.
Owner-occupied properties are commonly associated with long-term living, lifestyle and personal use.
In simple terms
An owner occupier purchases property mainly to live in it themselves.
This may include:
houses,
units,
townhouses,
or acreage properties used as a main home.
Why owner occupier properties matter
Owner occupier demand may significantly influence:
property prices,
buyer competition,
lending conditions,
and overall market activity.
Many buyers prioritise factors such as:
lifestyle,
location,
schools,
family needs,
and long-term stability.
Owner occupiers and property strategy
Owner occupier properties are commonly linked to:
family planning,
upgrading or downsizing,
sell-to-buy strategies,
equity growth,
and long-term financial security.
For many Australians, the family home remains one of the largest financial assets they will own.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before purchasing an owner-occupied property, it is important to consider:
affordability,
borrowing capacity,
lifestyle goals,
holding costs,
future flexibility,
and long-term plans.
A home should support both lifestyle and financial stability.
Property decisions should be made with strategy, not panic.
Key Insight
An owner occupier property is more than just a place to live.
It may also become a long-term financial foundation that shapes future opportunity and lifestyle choices.
Understanding your position is the first step.


Property Ownership
Principal Place of Residence (PPOR)
A Principal Place of Residence (PPOR) is the main property a person lives in as their primary home.
It is commonly referred to as an owner’s “main residence” for legal, financial and taxation purposes.
In simple terms
A PPOR is the property where you primarily live and consider home.
It may be:
a house,
unit,
townhouse,
or other residential property used as your main residence.
Why a PPOR matters
A Principal Place of Residence may provide benefits relating to:
capital gains tax exemptions,
home ownership grants,
land tax treatment,
lending policies,
and long-term financial security.
For many Australians, the family home becomes one of their largest long-term assets.
PPOR and property strategy
A PPOR is commonly linked to:
upgrading,
downsizing,
equity access,
refinancing,
sell-to-buy strategies,
and long-term lifestyle planning.
Some owners later convert a former PPOR into an investment property depending on their future goals.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before purchasing or changing a PPOR, it is important to consider:
affordability,
borrowing capacity,
holding costs,
lifestyle needs,
future flexibility,
and ownership structure.
Taxation and legal outcomes may differ depending on how the property is used over time.
Property decisions should be made with strategy, not panic.
Key Insight
A Principal Place of Residence is more than just where you live.
It can become a major financial foundation that influences lifestyle, equity growth and future opportunities.
Understanding your position is the first step.


Property Ownership
Rental Appraisal
A rental appraisal is an estimate of how much rent a property may achieve in the current rental market.
It is commonly prepared by a real estate agent or property manager using local market knowledge and comparable rental properties.
In simple terms
A rental appraisal helps estimate what tenants may currently be willing to pay to rent a property.
The estimate may be influenced by:
location,
property condition,
size,
features,
rental demand,
and local vacancy rates.
Why rental appraisals matter
Rental appraisals may help owners:
understand potential rental income,
assess investment performance,
estimate cash flow,
plan future investments,
and make informed property decisions.
Many homeowners are sitting on more opportunity than they realise.
Rental appraisals and property strategy
Rental appraisals are commonly used for:
investment property purchases,
refinancing,
insurance reviews,
sell-to-rent strategies,
and development feasibility assessments.
They may also help owners understand whether renovations or improvements could increase rental return.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
A rental appraisal is an estimate only and may change depending on:
market conditions,
tenant demand,
property presentation,
economic conditions,
and supply levels.
Actual rental outcomes may differ from the appraisal.
Property decisions should be made with strategy, not panic.
Key Insight
A rental appraisal is not simply about setting rent.
It is a tool that may help owners better understand property performance, cash flow potential and future opportunities.
Understanding your position is the first step.


Property Ownership
Rental Return
Rental return refers to the income a property generates from rent relative to the property’s value or purchase price.
It is commonly used by investors to assess property performance and compare investment opportunities.
In simple terms
Rental return helps measure how effectively a property generates rental income.
It is often expressed as a percentage.
For example:
a property earning $30,000 per year in rent,
on a $600,000 property,
would produce a gross rental return of approximately 5%.
Why rental return matters
Understanding rental return may help investors:
assess cash flow,
compare properties,
evaluate investment performance,
estimate holding costs,
and plan long-term strategies.
Different investors may prioritise rental return differently depending on their goals.
Rental return and property strategy
Some investors focus on:
higher rental yield,
long-term capital growth,
balanced cash flow,
or development potential.
Strong rental return does not always mean strong long-term growth potential, and vice versa.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Rental return may be affected by:
vacancy rates,
tenant demand,
property condition,
location,
holding costs,
and market conditions.
Gross rental return and net rental return may produce very different results once expenses are considered.
Property decisions should be made with strategy, not panic.
Key Insight
Rental return is not just about collecting rent.
It is a key metric used to understand property performance, cash flow and long-term investment potential.
Understanding your position is the first step.


Property Ownership
Secondary Dwelling
A secondary dwelling is a smaller self-contained residence located on the same property as a primary home.
It is commonly known as a:
granny flat,
secondary unit,
or ancillary dwelling.
In simple terms
A secondary dwelling provides additional living space on a property while remaining connected to the main residence.
It may include:
a bedroom,
bathroom,
kitchen,
and living area.
Some secondary dwellings are used for:
family members,
rental income,
guest accommodation,
or multigenerational living.
Why secondary dwellings matter
Secondary dwellings may help owners:
create additional income,
improve property flexibility,
accommodate family,
increase property functionality,
and potentially add value.
Many homeowners are sitting on more opportunity than they realise.
Secondary dwellings and property strategy
Secondary dwellings are commonly considered for:
investment strategies,
dual living,
ageing parents,
adult children,
lifestyle flexibility,
and long-term property planning.
Different councils and zoning rules may affect what is permitted.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before building or purchasing a property with a secondary dwelling, it is important to consider:
council approvals,
zoning,
site size,
access,
parking,
services,
and rental compliance requirements.
Not all properties are suitable for a secondary dwelling.
Property decisions should be made with strategy, not panic.
Key Insight
A secondary dwelling is not simply extra space.
Used strategically, it may create flexibility, income opportunities and stronger long-term property outcomes.
Understanding your position is the first step.


Property Ownership
Settlement
Settlement is the final stage of a property transaction where legal ownership officially transfers from the seller to the buyer.
It is the point where the sale is completed and the buyer takes ownership of the property.
In simple terms
During settlement:
the buyer pays the remaining purchase funds,
the seller transfers ownership,
legal documents are finalised,
and the property title is updated.
Once settlement occurs, the buyer officially becomes the new owner.
Why settlement matters
Settlement is a critical stage because it finalises:
the transfer of ownership,
payment of funds,
loan arrangements,
and legal obligations between buyer and seller.
Without settlement, the transaction is not fully completed.
Settlement and property transactions
Settlement commonly involves:
conveyancers,
solicitors,
lenders,
banks,
and government title offices.
Settlement periods may vary depending on the contract terms and agreement between the parties.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before settlement, it is important to ensure:
finance is approved,
inspections are completed,
insurance is arranged,
legal documents are signed,
and settlement funds are available.
Delays or issues before settlement may affect the transaction.
Property decisions should be made with strategy, not panic.
Key Insight
Settlement is not just paperwork.
It is the final legal and financial step that officially completes a property transaction.
Understanding your position is the first step.


Property Ownership
Stamp Duty
Stamp duty is a government tax paid when purchasing property or transferring ownership of certain assets.
In Queensland, stamp duty is generally referred to as transfer duty.
In simple terms
Stamp duty is usually calculated based on:
the property purchase price,
property type,
buyer status,
and how the property will be used.
The amount payable may vary depending on:
whether the buyer is an owner occupier or investor,
eligibility for concessions,
and the state or territory where the property is located.
Why stamp duty matters
Stamp duty may significantly affect:
upfront purchasing costs,
borrowing requirements,
cash flow,
and overall affordability.
Many buyers focus on the purchase price but underestimate the additional costs involved in buying property.
Stamp duty and property strategy
Stamp duty is commonly considered during:
first home purchases,
investment property purchases,
upgrades and downsizing,
trust or company purchases,
and long-term ownership planning.
Some buyers may qualify for grants or concessions depending on their circumstances.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before purchasing property, it is important to understand:
estimated stamp duty costs,
available concessions,
legal fees,
lender costs,
and total upfront expenses.
Different ownership structures may also affect stamp duty outcomes.
Property decisions should be made with strategy, not panic.
Key Insight
Stamp duty is not just a small transaction fee.
It can be one of the largest upfront costs involved in purchasing property and should be factored into planning from the beginning.
Understanding your position is the first step.


Property Ownership
Strata Title
Strata title is a form of property ownership where an individual owns a specific part of a property — such as a unit, townhouse or apartment — while also sharing ownership of common areas with other owners.
Common areas may include:
driveways,
lifts,
gardens,
pools,
hallways,
and shared facilities.
In simple terms
With strata title ownership:
you own your individual lot,
but also share responsibility for common property within the complex.
A body corporate or owners corporation is usually responsible for managing the shared areas.
Why strata title matters
Strata title may provide:
lower-maintenance living,
shared facilities,
community-style living,
and access to locations that may otherwise be unaffordable.
Strata title is commonly associated with units, apartments and townhouse complexes.
Strata title and property ownership
Strata title properties commonly involve:
body corporate fees,
shared maintenance costs,
bylaws and rules,
sinking funds,
and shared insurance arrangements.
Different strata complexes may operate very differently depending on management and financial position.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before purchasing a strata property, it is important to review:
body corporate fees,
sinking fund balances,
bylaws,
insurance,
maintenance obligations,
and the overall condition of the complex.
Shared ownership structures may affect flexibility and ongoing costs.
Property decisions should be made with strategy, not panic.
Key Insight
Strata title ownership is not just about buying a unit.
It also involves shared ownership responsibilities, ongoing costs and community management structures.
Understanding your position is the first step.


Property Ownership
Title Search
A title search is a legal search conducted on a property to confirm ownership details and identify any registered interests or restrictions affecting the land.
It is commonly performed during property purchases, sales and refinancing.
In simple terms
A title search helps confirm:
who legally owns the property,
property dimensions,
and whether there are any legal matters affecting the land.
The search may reveal:
easements,
covenants,
mortgages,
encumbrances,
caveats,
or other registered interests.
Why title searches matter
A title search may help buyers and owners:
verify ownership,
identify risks,
avoid legal surprises,
and better understand what affects the property.
It is one of the most important checks performed during a property transaction.
Title searches and property strategy
Title searches are commonly used during:
property purchases,
refinancing,
development planning,
subdivisions,
and legal due diligence.
Understanding title restrictions may significantly affect future plans for the property.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before purchasing property, it is important to understand:
easements,
access rights,
covenants,
existing mortgages,
zoning interactions,
and any restrictions registered on title.
Not all property issues are visible by simply inspecting the land.
Property decisions should be made with strategy, not panic.
Key Insight
A title search is not just a paperwork exercise.
It is a critical legal check that helps confirm ownership and identify issues that may affect the property now or in the future.
Understanding your position is the first step.


Property Ownership
Torrens Title
Torrens Title is the most common land ownership system in Australia.
It is a government-guaranteed system that records ownership and interests relating to land through an official title register.
In simple terms
Under Torrens Title:
the registered owner is recognised as the legal owner of the property,
and ownership details are recorded on a central government register.
The system is designed to simplify property ownership and improve certainty around land transactions.
Why Torrens Title matters
Torrens Title may provide:
clearer ownership records,
stronger legal certainty,
simpler property transfers,
and government-backed title registration.
Most standard residential houses in Australia are held under Torrens Title.
Torrens Title and property ownership
A Torrens Title property commonly allows the owner to:
own the land directly,
control the property independently,
and avoid some shared ownership structures associated with strata properties.
However, the title may still be affected by:
easements,
covenants,
mortgages,
and planning restrictions.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before purchasing a Torrens Title property, it is important to understand:
registered easements,
access rights,
zoning,
overlays,
and any restrictions listed on title.
Not all Torrens Title properties are completely unrestricted.
Property decisions should be made with strategy, not panic.
Key Insight
Torrens Title is not simply a certificate of ownership.
It is a legal ownership system designed to provide clarity, certainty and protection over land ownership.
Understanding your position is the first step.


Property Ownership
Transfer Duty
Transfer duty is a government tax charged when ownership of property or certain assets is transferred from one party to another.
In Queensland, transfer duty is the official term commonly used instead of stamp duty.
In simple terms
Transfer duty is usually calculated based on:
the property purchase price,
the value of the property,
buyer type,
and how the property will be used.
The amount payable may vary depending on:
whether the property is owner occupied or an investment,
eligibility for concessions,
and the ownership structure involved.
Why transfer duty matters
Transfer duty may significantly affect:
upfront buying costs,
borrowing requirements,
cash flow,
and overall affordability.
Many buyers underestimate how much transfer duty may add to the total cost of purchasing property.
Transfer duty and property strategy
Transfer duty is commonly considered during:
first home purchases,
investment property purchases,
refinancing structures,
trust or company purchases,
and long-term ownership planning.
Some buyers may qualify for grants or concessions depending on eligibility requirements.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before purchasing property, it is important to understand:
estimated transfer duty costs,
available concessions,
legal fees,
lender costs,
and total upfront expenses.
Different ownership structures may produce different transfer duty outcomes.
Property decisions should be made with strategy, not panic.
Key Insight
Transfer duty is not simply a government fee.
It can become one of the largest upfront costs involved in purchasing property and should be factored into planning from the beginning.
Understanding your position is the first step.


Property Ownership
Usable Equity
Usable equity is the portion of equity in a property that may potentially be accessed or borrowed against, subject to lender approval.
It is different from total equity.
In simple terms
Equity is generally the difference between:
a property’s market value,
and the amount still owed on the loan.
Usable equity is the amount a lender may allow you to access above your existing loan balance.
For example:
if a property is worth $800,000,
and the loan balance is $400,000,
total equity may be $400,000.
However, lenders often only allow borrowing up to a certain percentage of the property value, commonly around 80%.
That means the usable equity may be significantly lower than the total equity figure.
Why usable equity matters
Usable equity may help property owners:
purchase another property,
renovate,
refinance,
invest,
consolidate debt,
or improve financial flexibility.
Many homeowners are sitting on more opportunity than they realise.
Usable equity and property strategy
Usable equity is commonly considered during:
sell-to-buy planning,
investment strategies,
development projects,
refinancing,
and long-term wealth planning.
Accessing equity increases debt exposure and should be approached strategically.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before accessing usable equity, it is important to consider:
borrowing capacity,
interest rates,
cash flow,
lender policies,
property values,
and long-term financial goals.
Having equity does not automatically mean it can be accessed.
Property decisions should be made with strategy, not panic.
Key Insight
Usable equity is not just a number on paper.
It may become a strategic financial tool that can create future opportunity when used carefully and responsibly.
Understanding your position is the first step.


Property Ownership
Valuation
A valuation is a professional assessment of a property’s estimated market value at a specific point in time.
Valuations are commonly conducted by qualified valuers for lending, legal, financial and property purposes.
In simple terms
A valuation helps determine what a property may reasonably be worth in the current market.
The assessment may consider:
comparable sales,
location,
land size,
property condition,
improvements,
and current market conditions.
Why valuations matter
Valuations may help property owners:
refinance,
assess equity,
buy or sell confidently,
settle legal matters,
and make informed financial decisions.
Many homeowners are sitting on more opportunity than they realise.
Valuations and property strategy
Valuations are commonly used for:
property purchases,
refinancing,
family law matters,
deceased estates,
investment planning,
and development feasibility assessments.
Lenders often require formal valuations before approving finance.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
A valuation may differ from:
an appraisal,
insured value,
replacement cost,
or personal opinion of value.
Different valuers may also produce slightly different outcomes depending on timing and methodology.
Property decisions should be made with strategy, not panic.
Key Insight
A valuation is not simply an opinion.
It is a professional assessment designed to provide an informed estimate of market value based on available evidence and market conditions.
Understanding your position is the first step.


Property Ownership
Vendor Disclosure
Vendor disclosure refers to the legal obligation of a property seller to provide certain information about a property to potential buyers before or during a sale process.
The purpose is to help buyers make informed decisions and reduce the risk of hidden issues or disputes after the sale.
In simple terms
Vendor disclosure may include information relating to:
title details,
easements,
zoning,
encumbrances,
body corporate information,
approvals,
or other matters affecting the property.
Disclosure requirements may vary depending on the state, property type and transaction.
Why vendor disclosure matters
Vendor disclosure may help:
improve transparency,
reduce legal disputes,
build buyer confidence,
and ensure buyers are aware of important property information before purchasing.
Failing to disclose certain matters may create legal risks for sellers.
Vendor disclosure and property strategy
Vendor disclosure is commonly considered during:
residential sales,
unit and strata sales,
development site transactions,
off-market sales,
and commercial property transactions.
Proper preparation before listing a property may help avoid delays and complications later in the transaction.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before selling property, it is important to understand:
legal disclosure obligations,
title issues,
approvals,
zoning matters,
body corporate information,
and any known issues affecting the property.
Buyers should still conduct their own due diligence and independent investigations.
Property decisions should be made with strategy, not panic.
Key Insight
Vendor disclosure is not simply paperwork.
It is an important part of creating transparency, reducing risk and helping buyers make informed property decisions.
Understanding your position is the first step.


Property Ownership
Form 6
A Form 6 is the legally required appointment form used in Queensland to authorise a real estate agent to act on behalf of a property owner.
It is officially known as the:
Property Occupations Form 6 — Appointment and Reappointment of a Property Agent, Resident Letting Agent or Property Auctioneer.
In simple terms
A Form 6 sets out:
who the agent is,
who the client is,
the services being provided,
commission arrangements,
appointment terms,
and the authority granted to the agent.
Without a properly completed Form 6, a real estate agent may not legally be entitled to claim commission in Queensland.
Why Form 6 matters
A Form 6 helps provide:
legal clarity,
transparency,
written authority,
and protection for both the seller and the agent.
It forms a critical part of Queensland real estate compliance.
Form 6 and property sales
A Form 6 is commonly used for:
residential sales,
commercial sales,
property management,
auctions,
and buyer agency appointments.
The document may include:
exclusive agency appointments,
sole agency appointments,
or open listing arrangements.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before signing a Form 6, it is important to understand:
commission structure,
appointment type,
authority period,
termination conditions,
marketing arrangements,
and the services being provided.
Property owners should always read the document carefully before signing.
Property decisions should be made with strategy, not panic.
Key Insight
A Form 6 is not just administration paperwork.
It is the legal agreement that formally authorises a real estate agent to act on behalf of a property owner in Queensland.
Understanding your position is the first step.


Property Ownership
Off-Market Sale
An off-market sale is a property sale that occurs without publicly advertising the property to the open market.
Instead of listing the property on major websites or running a public marketing campaign, the property is usually offered privately to selected buyers.
In simple terms
An off-market sale may involve:
private buyer databases,
direct agent contacts,
investor networks,
existing buyer enquiries,
or targeted introductions.
The property may sell without:
online advertising,
open homes,
signboards,
or broad public exposure.
Why off-market sales matter
Off-market sales may offer benefits such as:
greater privacy,
reduced public attention,
lower marketing costs,
flexible negotiation,
and faster transactions in some situations.
Some sellers prefer a quieter approach rather than launching a full public campaign.
Off-market sales and property strategy
Off-market selling is commonly considered for:
prestige properties,
development sites,
investment portfolios,
sellers testing the market,
sensitive situations,
and buyers seeking opportunities before properties hit the public market.
In tightly supplied markets, some buyers actively seek off-market opportunities to reduce competition.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
An off-market sale may reduce:
public exposure,
competition between buyers,
and broad market reach.
In some situations, a fully marketed campaign may achieve a stronger result depending on buyer demand and property type.
Property decisions should be made with strategy, not panic.
Key Insight
An off-market sale is not simply a “secret sale.”
It is a strategic selling method that may suit certain properties, sellers and market conditions when approached correctly.
Understanding your position is the first step.


Property Ownership
Conditional Contract
A conditional contract is a property contract that depends on certain conditions being satisfied before the sale becomes fully binding.
If the required conditions are not met within the agreed timeframe, the contract may be cancelled.
In simple terms
A conditional contract allows the buyer or seller time to complete specific requirements before proceeding to settlement.
Common conditions may include:
finance approval,
building and pest inspections,
sale of another property,
due diligence,
or council and legal searches.
Until the conditions are satisfied or waived, the contract remains conditional.
Why conditional contracts matter
Conditional contracts may help:
reduce risk,
provide flexibility,
protect buyers and sellers,
and allow time to complete important checks before committing fully.
They are one of the most common contract structures in residential property transactions.
Conditional contracts and property strategy
Conditional contracts are commonly used for:
financed purchases,
first-home buyers,
investment purchases,
development sites,
and transactions involving complex due diligence.
Different conditions may significantly affect negotiation strength and contract certainty.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before signing a conditional contract, it is important to understand:
the specific contract conditions,
deadlines,
rights of termination,
finance obligations,
and what happens if conditions are not satisfied.
Missing deadlines or misunderstanding conditions may create legal and financial complications.
Property decisions should be made with strategy, not panic.
Key Insight
A conditional contract is not simply a “pending sale.”
It is a legal agreement that gives parties time to satisfy important requirements before the transaction becomes unconditional.
Understanding your position is the first step.


Property Ownership
Unconditional Contract
An unconditional contract is a property contract where all conditions have either been satisfied, waived, or the contract was unconditional from the beginning.
At this stage, both the buyer and seller are legally committed to completing the transaction.
In simple terms
Once a contract becomes unconditional:
the buyer is legally required to proceed with the purchase,
and the seller is legally required to complete the sale.
The contract is no longer dependent on conditions such as:
finance approval,
building and pest inspections,
due diligence,
or the sale of another property.
Why unconditional contracts matter
An unconditional contract provides:
greater certainty,
stronger legal commitment,
and a clearer path toward settlement.
For sellers, it often means the risk of the contract collapsing is significantly reduced.
Unconditional contracts and property strategy
A contract may become unconditional:
immediately after signing,
or after all contract conditions are satisfied within the agreed timeframe.
This stage is commonly important for:
coordinating settlement,
organising moving arrangements,
securing finance drawdowns,
and planning linked transactions.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before allowing a contract to become unconditional, buyers should ensure:
finance is formally approved,
inspections are completed,
legal advice has been obtained,
and they are fully comfortable proceeding with the purchase.
Terminating an unconditional contract may result in serious legal and financial consequences.
Property decisions should be made with strategy, not panic.
Key Insight
An unconditional contract is not simply a “done deal.”
It is the stage where both parties become fully legally committed to completing the property transaction.
Understanding your position is the first step.


Property Ownership
Acquisition Costs
Acquisition costs are the total expenses involved in purchasing a property or development site beyond just the purchase price itself.
These costs should be factored into planning from the very beginning.
In simple terms
Acquisition costs may include:
stamp duty or transfer duty,
legal and conveyancing fees,
lender fees,
valuation costs,
due diligence expenses,
inspections,
government charges,
and finance-related costs.
For developers and investors, acquisition costs may also include:
consultant reports,
feasibility studies,
planning investigations,
holding deposits,
and negotiation costs.
Why acquisition costs matter
Acquisition costs may significantly affect:
borrowing requirements,
cash flow,
project feasibility,
and overall profitability.
Many buyers focus only on the purchase price and underestimate the true cost of acquiring property.
Acquisition costs and property strategy
Acquisition costs are commonly assessed during:
residential purchases,
investment acquisitions,
development projects,
commercial transactions,
and land banking opportunities.
In development projects, accurately calculating acquisition costs may heavily influence whether a project is financially viable.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before purchasing property, it is important to understand:
total upfront costs,
available cash reserves,
finance structure,
holding costs,
and the impact acquisition costs may have on returns or feasibility.
Poor planning around acquisition costs may create financial pressure later.
Property decisions should be made with strategy, not panic.
Key Insight
Acquisition costs are not simply “extra fees.”
They are a critical part of understanding the true cost of purchasing property and assessing whether a deal actually makes financial sense.
Understanding your position is the first step.


Property Development
Approval Risk
Approval risk refers to the possibility that a proposed property transaction, finance application or development project may not receive the required approvals needed to proceed.
It is one of the most important risks to consider in property development and complex property transactions.
In simple terms
Approval risk may involve uncertainty around:
council approvals,
finance approvals,
zoning compliance,
planning outcomes,
environmental requirements,
infrastructure conditions,
or regulatory approvals.
If approvals are delayed, rejected or changed, the project or transaction may become financially or legally unworkable.
Why approval risk matters
Approval risk may significantly affect:
project feasibility,
timelines,
holding costs,
profitability,
and overall deal certainty.
Many property opportunities look attractive on paper until approval risks are properly assessed.
Approval risk and property strategy
Approval risk is commonly considered during:
development site acquisitions,
subdivision projects,
Material Change of Use (MCU) applications,
refinancing,
commercial projects,
and higher-density developments.
Different properties carry different levels of approval risk depending on location, zoning and intended use.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before proceeding with a project or acquisition, it is important to understand:
zoning and overlays,
council planning schemes,
infrastructure requirements,
environmental constraints,
flood or bushfire overlays,
and likely approval pathways.
Professional advice and due diligence may significantly reduce unnecessary risk.
Property decisions should be made with strategy, not panic.
Key Insight
Approval risk is not simply “paperwork uncertainty.”
It can directly affect whether a project becomes profitable, delayed or completely unviable.
Understanding your position is the first step.


Property Development
Brownfield Site
A brownfield site is land that has previously been developed or used for industrial, commercial, agricultural or residential purposes and may now be considered for redevelopment.
These sites often already contain existing infrastructure, buildings or past land use impacts.
In simple terms
A brownfield site is not “raw” undeveloped land.
It may include:
old industrial land,
former commercial sites,
ageing shopping centres,
disused facilities,
old housing stock,
or previously developed land being repurposed.
Some brownfield sites may also involve contamination, demolition or remediation requirements.
Why brownfield sites matter
Brownfield sites may offer opportunities for:
redevelopment,
higher-density projects,
infill development,
urban renewal,
and strategic land repositioning.
Because infrastructure often already exists nearby, these sites may sometimes reduce expansion pressure on undeveloped land.
Brownfield sites and property strategy
Brownfield sites are commonly considered for:
townhouse projects,
mixed-use developments,
subdivision projects,
commercial repositioning,
and redevelopment within established areas.
However, these sites may also carry higher complexity and approval risk.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before purchasing or developing a brownfield site, it is important to understand:
zoning,
contamination risk,
demolition costs,
infrastructure capacity,
environmental requirements,
planning overlays,
and redevelopment feasibility.
Some brownfield sites may involve substantial hidden costs.
Property decisions should be made with strategy, not panic.
Key Insight
A brownfield site is not simply “old land.”
It may represent a strategic redevelopment opportunity — but success often depends on careful due diligence, feasibility analysis and risk management.
Understanding your position is the first step.


Property Development
Density
Density refers to the number of dwellings, buildings or people permitted within a specific area of land.
In property and town planning, density is commonly used to describe how intensively land may be developed.
In simple terms
Higher density generally means:
more dwellings on smaller areas of land,
smaller lot sizes,
or multi-dwelling developments such as units and townhouses.
Lower density usually involves:
larger blocks,
fewer dwellings,
and more open space.
Density controls are typically managed through zoning and planning schemes.
Why density matters
Density may significantly affect:
property value,
development potential,
infrastructure demand,
neighbourhood character,
and project feasibility.
Changes to density rules may create new opportunities for redevelopment or subdivision.
Density and property strategy
Density is commonly considered during:
subdivision projects,
townhouse developments,
unit developments,
infill projects,
land acquisitions,
and long-term strategic landholding.
Higher density allowances may increase the potential value of certain properties.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before purchasing or developing property, it is important to understand:
zoning,
minimum lot sizes,
site coverage limits,
setback requirements,
parking requirements,
infrastructure capacity,
and council planning rules.
Not every site is suitable for higher-density development even if demand exists.
Property decisions should be made with strategy, not panic.
Key Insight
Density is not simply about “fitting more houses on land.”
It is about balancing land use, infrastructure, feasibility and long-term planning outcomes.
Understanding your position is the first step.


Property Development
Development Application (DA)
A Development Application, commonly called a DA, is a formal application submitted to a local council or assessment authority seeking approval for a proposed property development or change in land use.
A DA is often required before certain development or construction activities can legally proceed.
In simple terms
A Development Application may be required for:
subdivisions,
townhouse projects,
unit developments,
commercial developments,
land use changes,
material change of use,
operational works,
or developments outside standard planning rules.
The application is assessed against:
zoning,
overlays,
planning schemes,
infrastructure requirements,
environmental considerations,
and local government policies.
Why Development Applications matter
A DA may significantly affect:
property value,
development potential,
project timelines,
approval risk,
and overall feasibility.
In some cases, gaining development approval may substantially increase the value or usability of a property.
Development Applications and property strategy
Development Applications are commonly considered during:
site acquisitions,
feasibility studies,
infill developments,
subdivision projects,
commercial projects,
and strategic landholding opportunities.
Some projects may proceed smoothly, while others may face delays, objections or significant approval conditions.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before lodging or purchasing property for development, it is important to understand:
zoning,
overlays,
infrastructure capacity,
flood and environmental constraints,
site access,
servicing requirements,
and likely approval pathways.
Professional consultants such as planners, engineers, surveyors and environmental specialists are often involved in the DA process.
Property decisions should be made with strategy, not panic.
Key Insight
A Development Application is not simply “asking council for permission.”
It is a detailed planning and assessment process that may determine whether a project is financially viable, achievable and legally compliant.
Understanding your position is the first step.


Property Development
Development Management Agreement (DMA)
A Development Management Agreement, commonly called a DMA, is a legal agreement where a property owner engages a development manager to coordinate and manage a development project on their behalf.
Instead of selling the property outright, the owner may retain ownership while partnering with an experienced party to help deliver the project.
In simple terms
A DMA allows a development manager to assist with:
feasibility analysis,
project planning,
consultant coordination,
council approvals,
finance coordination,
construction management,
marketing,
and project delivery.
The landowner and development manager typically agree on:
responsibilities,
profit sharing,
management fees,
project structure,
risk allocation,
and decision-making authority.
Why DMAs matter
A DMA may allow landowners to:
unlock additional value,
participate in development profits,
retain greater control,
and access development expertise without managing the project alone.
In some situations, a DMA may produce a stronger financial outcome than a simple land sale.
Development Management Agreements and property strategy
DMAs are commonly considered for:
subdivision projects,
townhouse developments,
mixed-use developments,
strategic landholdings,
infill developments,
and redevelopment opportunities.
These agreements are often used where a property has development potential but the owner does not wish to undertake the project independently.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before entering a DMA, it is important to understand:
project feasibility,
approval risk,
funding requirements,
profit distribution,
legal structure,
tax implications,
timeframes,
and exit strategies.
Professional legal, accounting and planning advice is essential before entering any development agreement.
Property decisions should be made with strategy, not panic.
Key Insight
A Development Management Agreement is not simply “hiring someone to build.”
It is a structured partnership arrangement designed to combine land, expertise and strategy to unlock development potential.
Understanding your position is the first step.


Property Development
Emerging Community
Emerging Community is a planning and zoning term used to describe land identified for future urban growth and development.
These areas are generally intended to transition over time from rural, low-intensity or undeveloped land into new residential, commercial or mixed-use communities.
In simple terms
Emerging Community land is often viewed as:
future growth land,
urban expansion land,
or land positioned for future development potential.
The zoning usually signals that long-term development may eventually occur, but the land may still require:
infrastructure upgrades,
planning approvals,
servicing,
and staged development over time.
Why Emerging Community zoning matters
Emerging Community land may offer opportunities for:
land banking,
future subdivision,
residential estates,
mixed-use projects,
and long-term capital growth.
However, timing and feasibility are critical.
Not all Emerging Community land can be immediately developed.
Emerging Community and property strategy
Emerging Community zoning is commonly considered during:
strategic land acquisitions,
long-term investment planning,
subdivision feasibility,
development site sourcing,
and infrastructure-led growth planning.
These areas are often heavily influenced by:
council planning strategy,
infrastructure delivery,
population growth,
and servicing capacity.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before purchasing or developing Emerging Community land, it is important to understand:
infrastructure availability,
zoning intent,
staging requirements,
flood and environmental overlays,
servicing costs,
approval pathways,
and realistic development timelines.
Holding costs and delays may significantly affect project feasibility.
Property decisions should be made with strategy, not panic.
Key Insight
Emerging Community land is not simply “future subdivision land.”
It is land positioned within long-term growth planning frameworks that may create significant opportunity when timing, infrastructure and strategy align.
Understanding your position is the first step.


Property Development
Feasibility Study
A feasibility study is an assessment used to determine whether a proposed property project is financially, legally and practically viable before proceeding.
It is one of the most important tools used in property development and investment decision-making.
In simple terms
A feasibility study helps answer questions such as:
Will the project make money?
Can the site actually be developed?
What are the risks?
What approvals are required?
What will the total costs likely be?
Is the potential return worth the risk?
A feasibility study may assess:
acquisition costs,
construction costs,
holding costs,
council requirements,
infrastructure,
market demand,
projected sale prices,
rental returns,
and development timelines.
Why feasibility studies matter
A feasibility study may help:
reduce financial risk,
identify hidden issues,
avoid poor investments,
improve planning,
and determine whether a project should proceed at all.
Some projects look profitable at first glance but become unviable once all costs and risks are properly assessed.
Feasibility studies and property strategy
Feasibility studies are commonly used for:
subdivisions,
townhouse developments,
unit projects,
mixed-use developments,
commercial developments,
land banking,
and renovation or redevelopment opportunities.
They are often completed before entering contracts or lodging Development Applications (DAs).
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before proceeding with a project, it is important to understand:
zoning and overlays,
approval risk,
infrastructure costs,
market demand,
finance availability,
construction costs,
holding costs,
and realistic end values.
Good feasibility studies should include contingency allowances because projects rarely go perfectly to plan.
Property decisions should be made with strategy, not panic.
Key Insight
A feasibility study is not simply a spreadsheet exercise.
It is a strategic decision-making tool used to assess whether a project is realistically achievable, financially worthwhile and worth the risk involved.
Understanding your position is the first step.


Property Development
Flood Overlay
A flood overlay is a planning map layer used by councils and planning authorities to identify land that may be affected by flooding.
Flood overlays help determine how land can be used, developed or built on based on flood risk.
In simple terms
A flood overlay may identify areas that are:
prone to river flooding,
stormwater flooding,
overland flow,
coastal inundation,
or other flood-related risks.
Properties within a flood overlay may be subject to:
development restrictions,
building requirements,
floor height controls,
engineering conditions,
or additional approval requirements.
Why flood overlays matter
Flood overlays may significantly affect:
development potential,
insurance costs,
construction requirements,
finance approvals,
property value,
and long-term risk exposure.
Flood overlays are a critical part of due diligence when buying, developing or investing in property.
Flood overlays and property strategy
Flood overlays are commonly assessed during:
property purchases,
development feasibility studies,
subdivision planning,
renovation projects,
infrastructure planning,
and insurance assessments.
Some flood-affected properties may still offer strong opportunities if properly understood and planned for.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things to consider
Before purchasing or developing property affected by a flood overlay, it is important to understand:
flood mapping,
historical flood data,
minimum floor levels,
engineering requirements,
evacuation considerations,
insurance implications,
and council planning controls.
Not all flood overlays carry the same level of risk.
Property decisions should be made with strategy, not panic.
Key Insight
A flood overlay is not automatically a “deal breaker.”
It is a planning and risk management tool designed to help guide safer development, construction and land use decisions.
Understanding your position is the first step.


Property Development
Greenfield Development
A greenfield development refers to a project built on previously undeveloped land — usually farmland, vacant rural land, or open space located on the outskirts of towns or cities.
These projects are typically developed from a blank canvas, with entirely new infrastructure, roads, services and allotments created as part of the development process.
In simple terms
A greenfield development helps answer questions such as:
Can undeveloped land be turned into a residential or commercial project?
What infrastructure will be required?
Is the land located inside a future growth area?
What approvals are required?
What will the total development costs likely be?
Is the project financially viable?
A greenfield development may involve:
subdivision design,
new roads,
sewer and water infrastructure,
power and telecommunications,
stormwater systems,
parks and public spaces,
and creation of new residential or commercial lots.
Why Greenfield Developments Matter
Greenfield developments may help:
increase housing supply,
support population growth,
expand regional areas,
create new communities,
and unlock long-term land value.
These projects often play a major role in shaping the future growth of towns and cities.
Some greenfield sites may appear highly valuable, but infrastructure costs, approval risks and servicing constraints can significantly affect project viability.
Greenfield Developments and Property Strategy
Greenfield developments are commonly associated with:
residential estates,
acreage subdivisions,
industrial land releases,
mixed-use communities,
master-planned developments,
land banking,
and long-term growth corridor projects.
They are often assessed years before construction begins due to the scale of planning and infrastructure required.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before proceeding with a project, it is important to understand:
zoning and planning controls,
infrastructure availability,
servicing costs,
environmental constraints,
flood overlays,
market demand,
finance availability,
and realistic end values.
Large-scale developments can involve significant holding costs and lengthy approval timeframes, so proper planning and feasibility analysis are critical.
Property decisions should be made with strategy, not panic.
Key Insight
A greenfield development is more than simply subdividing vacant land.
It is a long-term strategic project that requires careful planning, infrastructure coordination, financial analysis and an understanding of future market demand.
Understanding your position is the first step.


Property Development
Gross Realisation Value (GRV)
Gross Realisation Value (GRV) refers to the total estimated end value of a property development project once completed and sold.
It is one of the most important figures used in property feasibility studies because it helps determine whether a project may be financially viable before construction begins.
In simple terms
Gross Realisation Value helps answer questions such as:
What could the completed project potentially sell for?
What is the estimated total end value of the development?
Does the potential revenue justify the project risk?
Will the project likely be profitable after costs?
How much funding may a lender provide?
Is the site worth pursuing?
GRV is commonly calculated by estimating:
future sale prices,
expected market demand,
end product values,
unit or lot pricing,
commercial leasing value,
and overall project revenue.
Why Gross Realisation Value Matters
GRV may help:
assess project feasibility,
determine potential profitability,
support finance applications,
guide acquisition decisions,
compare development opportunities,
and identify whether risk and reward are balanced.
A project may appear attractive initially, but if the projected GRV is too low compared to total costs and risk, the development may not be financially worthwhile.
GRV and Property Strategy
Gross Realisation Value is commonly used for:
residential subdivisions,
townhouse projects,
unit developments,
mixed-use projects,
commercial developments,
land banking assessments,
and redevelopment opportunities.
It is often one of the first figures developers and financiers assess when reviewing a project.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before relying on a projected GRV, it is important to understand:
current market conditions,
realistic sale prices,
local buyer demand,
competing stock levels,
construction costs,
finance costs,
development timelines,
and changing economic conditions.
Overestimating GRV is one of the most common mistakes made in property development feasibility studies.
Property decisions should be made with strategy, not panic.
Key Insight
Gross Realisation Value is not a guaranteed future sale result.
It is a strategic forecasting tool used to estimate the potential end value of a project based on market evidence, assumptions and projected demand.
Understanding your position is the first step.


Property Development
Headworks
Headworks refers to infrastructure charges or contributions that may be required as part of a property development project.
These charges are commonly imposed by councils or service authorities to help fund the infrastructure needed to support additional development and population growth.
In simple terms
Headworks helps answer questions such as:
What infrastructure costs may apply to the project?
Will council infrastructure charges be payable?
What services need to be upgraded or connected?
How much could infrastructure contributions cost?
Will the project place additional demand on public infrastructure?
How will these costs affect project feasibility?
Headworks charges may relate to:
water infrastructure,
sewer infrastructure,
roads and transport,
stormwater systems,
parks and public spaces,
community facilities,
and network upgrades.
Why Headworks Matter
Headworks charges may help:
fund infrastructure expansion,
support growing communities,
offset public infrastructure costs,
improve service capacity,
and ensure developments contribute toward future demand.
For developers and landowners, headworks can become a major project cost that significantly affects profitability and feasibility.
Some projects may appear financially viable until infrastructure charges are properly factored into the numbers.
Headworks and Property Strategy
Headworks are commonly considered for:
subdivisions,
residential estates,
townhouse developments,
unit projects,
commercial developments,
industrial land,
and mixed-use projects.
These costs are often assessed during feasibility studies and before lodging Development Applications (DAs).
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before proceeding with a project, it is important to understand:
council infrastructure charging policies,
available service capacity,
connection requirements,
infrastructure upgrade obligations,
staging of developments,
finance and holding costs,
and the impact headworks may have on project profitability.
Infrastructure costs can vary significantly depending on location, zoning, development scale and existing servicing availability.
Property decisions should be made with strategy, not panic.
Key Insight
Headworks are not simply an “extra fee” added to a development.
They are a major part of the infrastructure funding system that supports roads, water, sewer, drainage and community services required for future growth.
Understanding your position is the first step.


Property Development
Infrastructure Agreement
An infrastructure agreement is a formal agreement between a developer and a council or infrastructure authority that outlines how infrastructure will be delivered, funded or upgraded as part of a development project.
These agreements are commonly used in larger or more complex developments where additional infrastructure is required to support future growth.
In simple terms
An infrastructure agreement helps answer questions such as:
Who is responsible for delivering infrastructure?
What infrastructure upgrades are required?
How will infrastructure costs be shared?
When must infrastructure be completed?
What conditions apply to the development?
How will services connect to the project?
Infrastructure agreements may cover:
roads and intersections,
water and sewer upgrades,
stormwater systems,
parks and public spaces,
power and utility infrastructure,
staging requirements,
and developer contributions.
Why Infrastructure Agreements Matter
Infrastructure agreements may help:
coordinate large-scale development,
clarify infrastructure responsibilities,
reduce uncertainty between parties,
manage future servicing needs,
and support orderly urban growth.
For developers, these agreements can significantly affect project timing, costs and feasibility.
Some projects may not proceed until infrastructure delivery arrangements are finalised.
Infrastructure Agreements and Property Strategy
Infrastructure agreements are commonly associated with:
residential estates,
greenfield developments,
industrial projects,
mixed-use developments,
master-planned communities,
subdivision projects,
and major urban expansion areas.
They are often negotiated during the planning and approval process before construction begins.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before entering into an infrastructure agreement, it is important to understand:
infrastructure delivery obligations,
timing and staging requirements,
project cash flow impacts,
servicing availability,
upgrade costs,
approval conditions,
legal obligations,
and long-term maintenance responsibilities.
Infrastructure timing can heavily affect when land can be developed, sold or connected to essential services.
Property decisions should be made with strategy, not panic.
Key Insight
An infrastructure agreement is not simply a standard council requirement.
It is a strategic framework used to coordinate how essential infrastructure is delivered to support development, population growth and long-term community expansion.
Understanding your position is the first step.


Property Development
Infrastructure Charges
Infrastructure charges are fees or contributions that developers may be required to pay to councils or infrastructure authorities as part of a development project.
These charges help fund the infrastructure needed to support additional population growth and future development within an area.
In simple terms
Infrastructure charges help answer questions such as:
What council charges may apply to the development?
How much could infrastructure contributions cost?
What services or upgrades are required?
Will the project place additional demand on infrastructure?
How do these costs affect project feasibility?
When are infrastructure charges payable?
Infrastructure charges may relate to:
water infrastructure,
sewer infrastructure,
roads and transport,
stormwater systems,
parks and public spaces,
community facilities,
and utility network upgrades.
Why Infrastructure Charges Matter
Infrastructure charges may help:
support growing communities,
fund public infrastructure upgrades,
improve servicing capacity,
offset the impact of new development,
and ensure future infrastructure can meet demand.
For developers and landowners, these charges can become a major project expense that significantly affects profitability and feasibility.
Some projects may appear financially viable until infrastructure charges are properly factored into the feasibility study.
Infrastructure Charges and Property Strategy
Infrastructure charges are commonly considered for:
subdivisions,
residential estates,
townhouse developments,
unit projects,
commercial developments,
industrial projects,
and mixed-use developments.
They are often assessed during feasibility analysis and before lodging Development Applications (DAs).
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before proceeding with a project, it is important to understand:
council infrastructure charging policies,
timing of payments,
infrastructure servicing availability,
project staging,
upgrade requirements,
finance and holding costs,
and the impact these charges may have on profitability.
Infrastructure charges can vary significantly depending on location, zoning, development scale and existing infrastructure capacity.
Property decisions should be made with strategy, not panic.
Key Insight
Infrastructure charges are not simply an administrative fee added to a project.
They are part of the broader infrastructure funding system designed to support roads, water, sewer, drainage and community services required for future growth and development.
Understanding your position is the first step.


Property Development
Infill Development
An infill development refers to new development that occurs within an existing built-up urban area rather than expanding outward into undeveloped land.
These projects commonly involve subdividing large residential blocks, redeveloping older properties, or increasing housing density within established suburbs.
In simple terms
An infill development helps answer questions such as:
Can an existing property be subdivided or redeveloped?
Is there unused land within an established suburb?
Could higher density housing be achieved?
What approvals may be required?
Is the site financially viable to develop?
Will the area support increased housing density?
Infill developments may involve:
backyard subdivisions,
duplex developments,
townhouse projects,
unit developments,
secondary dwellings,
redevelopment of older homes,
and mixed-density housing projects.
Why Infill Development Matters
Infill development may help:
increase housing supply,
reduce urban sprawl,
improve land efficiency,
support population growth,
revitalise older suburbs,
and create additional value from existing land.
For property owners, infill opportunities can sometimes unlock hidden value within established residential areas.
Some large residential blocks may carry significantly more development potential than many owners realise.
Infill Development and Property Strategy
Infill development is commonly associated with:
established suburbs,
residential rezoning areas,
medium-density projects,
strategic landholdings,
town planning opportunities,
and redevelopment sites close to services and infrastructure.
These projects are often assessed through feasibility studies and town planning investigations before proceeding.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before proceeding with an infill project, it is important to understand:
zoning and overlays,
minimum lot sizes,
infrastructure availability,
access and frontage requirements,
neighbourhood character provisions,
stormwater and drainage,
approval risks,
and realistic end values.
Not every large block is automatically suitable for infill development, and some projects may involve significant planning, infrastructure or construction costs.
Property decisions should be made with strategy, not panic.
Key Insight
Infill development is not simply “building more houses on a block.”
It is a strategic form of urban development designed to better utilise existing infrastructure, services and land within established communities.
Understanding your position is the first step.


Property Development
Joint Venture
A joint venture is a partnership arrangement where two or more parties work together on a property project while sharing resources, risks, responsibilities and profits.
In property development, joint ventures are commonly used when one party has land and another party has funding, development expertise, construction capability or project management experience.
In simple terms
A joint venture helps answer questions such as:
Can multiple parties combine resources for a project?
Who contributes the land, funding or expertise?
How will profits be shared?
Who manages the development process?
What risks does each party carry?
Is the project financially worthwhile for everyone involved?
A joint venture may involve:
landowners,
developers,
investors,
builders,
project managers,
or finance partners.
Why Joint Ventures Matter
Joint ventures may help:
unlock development opportunities,
reduce upfront capital requirements,
share project risk,
combine expertise and resources,
improve project feasibility,
and create opportunities that may not be achievable individually.
For landowners, a joint venture can sometimes provide an alternative to simply selling the land outright.
Some property owners may be sitting on land with significant development potential but lack the experience or funding required to unlock it themselves.
Joint Ventures and Property Strategy
Joint ventures are commonly associated with:
subdivisions,
townhouse developments,
unit projects,
mixed-use developments,
infill developments,
greenfield projects,
and strategic landholdings.
These projects are usually assessed through feasibility studies, legal agreements and financial modelling before proceeding.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before entering into a joint venture, it is important to understand:
ownership structures,
profit-sharing arrangements,
project responsibilities,
finance requirements,
development risks,
legal agreements,
tax implications,
and exit strategies.
The success of a joint venture often depends on selecting the right partners, maintaining clear communication and properly structuring the agreement from the beginning.
Property decisions should be made with strategy, not panic.
Key Insight
A joint venture is not simply “going into business together.”
It is a structured strategic partnership designed to combine land, capital, expertise and opportunity to create a project outcome that may not be achievable individually.
Understanding your position is the first step.


Property Development
Land Banking
Land banking refers to the strategy of purchasing and holding land with the expectation that it may increase in value over time due to future growth, rezoning, infrastructure expansion or development potential.
Rather than immediately developing the land, the owner typically holds the property strategically while waiting for surrounding areas, population growth or planning changes to increase demand and value.
In simple terms
Land banking helps answer questions such as:
Could the land become more valuable in the future?
Is the area expected to grow or expand?
Could rezoning or infrastructure improve the land’s potential?
Is there future subdivision or development opportunity?
Is the holding strategy financially viable?
What risks exist while waiting for growth?
Land banking strategies may involve:
rural land,
emerging community land,
strategic landholdings,
infill sites,
greenfield sites,
future growth corridors,
and properties near planned infrastructure projects.
Why Land Banking Matters
Land banking may help:
create long-term capital growth,
secure strategic land positions,
benefit from future rezoning,
unlock future development opportunities,
and build wealth through long-term planning.
For some investors and landowners, the biggest value increase may come from future planning changes rather than immediate rental income or development.
Some land may appear underutilised today but carry significant long-term strategic potential.
Land Banking and Property Strategy
Land banking is commonly associated with:
urban expansion areas,
emerging communities,
future residential estates,
infrastructure corridors,
industrial growth areas,
strategic redevelopment sites,
and long-term investment strategies.
These opportunities are often assessed using feasibility studies, town planning investigations and population growth forecasts.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before proceeding with a land banking strategy, it is important to understand:
zoning and overlays,
future planning intentions,
infrastructure expansion,
holding costs,
finance requirements,
development timing risks,
environmental constraints,
and realistic long-term demand.
Land banking can involve long holding periods and there is never a guarantee that rezoning or development approvals will occur.
Property decisions should be made with strategy, not panic.
Key Insight
Land banking is not simply “buying cheap land and waiting.”
It is a long-term strategic investment approach focused on positioning land in areas that may benefit from future growth, infrastructure and planning changes over time.
Understanding your position is the first step.


Property Development
Material Change of Use (MCU)
A Material Change of Use (MCU) refers to a change in how land or a property is legally used under a council planning scheme.
An MCU approval is commonly required when a property owner or developer wants to change the approved use of land or buildings beyond what is currently permitted.
In simple terms
A Material Change of Use helps answer questions such as:
Can the land be used for a different purpose?
Is council approval required for the proposed use?
Does the zoning support the intended project?
What planning rules apply to the site?
Could the use increase density or activity?
What risks or conditions may apply?
An MCU may involve:
changing rural land to residential use,
establishing commercial uses,
increasing residential density,
creating mixed-use developments,
establishing industrial activities,
changing approved land uses,
or intensifying existing development.
Why Material Change of Use Matters
An MCU may help:
unlock development potential,
allow higher-value land uses,
increase site flexibility,
support urban growth,
improve project feasibility,
and create opportunities not currently available under existing approvals.
For some properties, the land’s highest value may depend heavily on whether an MCU approval can be achieved.
Some sites may appear ordinary today but carry significant upside through planning changes and approved future use.
MCU and Property Strategy
Material Change of Use approvals are commonly associated with:
subdivisions,
townhouse developments,
unit projects,
commercial developments,
industrial projects,
mixed-use developments,
and strategic landholdings.
MCUs are often assessed through feasibility studies, town planning advice and council planning scheme analysis before lodging an application.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before proceeding with an MCU application, it is important to understand:
zoning and overlays,
planning scheme requirements,
infrastructure capacity,
traffic and access impacts,
environmental constraints,
approval risks,
holding costs,
and realistic end values.
MCU approvals are never guaranteed and may involve conditions, infrastructure upgrades or lengthy approval timeframes.
Property decisions should be made with strategy, not panic.
Key Insight
A Material Change of Use is not simply “asking council for permission.”
It is a strategic planning process used to change, intensify or unlock a property’s legal use potential under the planning scheme.
Understanding your position is the first step.


Property Development
Medium Density
Medium density refers to a style of development that provides more housing than traditional detached homes, while remaining lower density than high-rise apartment developments.
Medium density developments are designed to increase housing supply and make more efficient use of land within urban and suburban areas.
In simple terms
Medium density helps answer questions such as:
Can more dwellings be built on the land?
Is the zoning suitable for increased density?
Could the site support townhouses or units?
What type of housing is permitted?
Is the development financially viable?
Will the area support higher population density?
Medium density development may include:
townhouses,
duplexes,
terrace housing,
villa developments,
low-rise unit complexes,
mixed-density projects,
and small apartment developments.
Why Medium Density Matters
Medium density development may help:
increase housing supply,
improve land efficiency,
support population growth,
reduce urban sprawl,
create more affordable housing options,
and unlock additional land value.
For property owners and developers, medium density zoning can significantly increase the development potential of a site compared to standard low-density residential use.
Some established residential blocks may hold far more potential than many owners realise.
Medium Density and Property Strategy
Medium density developments are commonly associated with:
infill development,
urban renewal areas,
strategic landholdings,
transport corridors,
mixed-use precincts,
town planning opportunities,
and growing regional centres.
These projects are usually assessed through feasibility studies, planning investigations and market analysis before proceeding.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before proceeding with a medium density project, it is important to understand:
zoning and overlays,
height restrictions,
site coverage requirements,
parking requirements,
infrastructure capacity,
neighbourhood character provisions,
approval risks,
and realistic end values.
Medium density developments can involve significant construction, infrastructure and holding costs, so proper planning and feasibility analysis are critical.
Property decisions should be made with strategy, not panic.
Key Insight
Medium density is not simply “building more homes closer together.”
It is a strategic urban planning approach designed to balance population growth, housing supply, infrastructure efficiency and community outcomes.
Understanding your position is the first step.


Property Development
Mixed Use
Mixed use refers to a type of development that combines multiple property uses within the same site, building or precinct.
These developments are designed to integrate different activities such as residential, commercial, retail, office or hospitality uses into one coordinated project.
In simple terms
Mixed use helps answer questions such as:
Can residential and commercial uses operate together?
Is the zoning suitable for multiple land uses?
Could the site support retail, office or residential components?
Will the project improve convenience and activity?
Is the development financially viable?
What planning or approval requirements apply?
Mixed use developments may include:
apartments above retail shops,
commercial offices with residential units,
hospitality and entertainment precincts,
retail and medical centres,
mixed residential and commercial buildings,
and integrated urban developments.
Why Mixed Use Matters
Mixed use development may help:
improve land efficiency,
activate urban areas,
increase housing supply,
support local businesses,
create walkable communities,
and generate multiple income streams from a single site.
For developers and investors, mixed use projects can provide diversification by combining different property sectors within the same development.
Some strategically located sites may carry significantly more value when multiple land uses are combined effectively.
Mixed Use and Property Strategy
Mixed use developments are commonly associated with:
town centres,
urban renewal precincts,
transport corridors,
medium and high-density areas,
commercial hubs,
strategic redevelopment sites,
and growing regional centres.
These projects are typically assessed through feasibility studies, planning investigations and market demand analysis before proceeding.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before proceeding with a mixed use project, it is important to understand:
zoning and planning controls,
parking requirements,
traffic and access impacts,
infrastructure capacity,
noise and compatibility issues,
approval risks,
construction complexity,
and realistic market demand for each use type.
Mixed use developments can involve more complex design, approval and management requirements than single-use projects.
Property decisions should be made with strategy, not panic.
Key Insight
Mixed use is not simply “combining different buildings together.”
It is a strategic planning approach designed to integrate residential, commercial and community activity into connected, efficient and functional urban environments.
Understanding your position is the first step.


Property Development
Net Realisation
Net Realisation refers to the estimated amount of money remaining from a project after all costs, expenses and liabilities have been deducted from the Gross Realisation Value (GRV).
In property development, net realisation is commonly used to assess the true financial outcome of a project rather than simply focusing on total sales revenue.
In simple terms
Net realisation helps answer questions such as:
How much profit may actually remain after costs?
Is the project financially worthwhile?
What is the likely final return?
Are the risks justified by the outcome?
How much value could realistically be created?
Does the project stack up financially?
Net realisation calculations may include deductions for:
acquisition costs,
construction costs,
infrastructure charges,
consultant fees,
finance and interest costs,
holding costs,
marketing and sales expenses,
taxes and GST,
and contingency allowances.
Why Net Realisation Matters
Net realisation may help:
determine project profitability,
improve feasibility analysis,
identify financial risk,
guide acquisition decisions,
compare development opportunities,
and assist with funding discussions.
A project with a high Gross Realisation Value may still perform poorly if total costs become too high.
Some developments appear profitable at first glance until all expenses and risks are properly accounted for.
Net Realisation and Property Strategy
Net realisation is commonly used for:
subdivisions,
townhouse developments,
unit projects,
mixed-use developments,
commercial projects,
land banking assessments,
and redevelopment opportunities.
It is often one of the most important figures used in development feasibility studies and strategic planning.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before relying on a projected net realisation figure, it is important to understand:
realistic sale values,
construction and infrastructure costs,
finance and holding costs,
market demand,
approval risks,
project timeframes,
contingency allowances,
and changing economic conditions.
Underestimating costs or overestimating end values can significantly affect the true profitability of a project.
Property decisions should be made with strategy, not panic.
Key Insight
Net realisation is not simply “sales minus costs.”
It is a strategic financial measurement used to determine the realistic financial outcome of a project after properly accounting for risk, expenses and market conditions.
Understanding your position is the first step.


Property Development
Operational Works
Operational Works refers to the physical construction and civil works required to support an approved development project.
These works are typically completed after planning approvals are granted and before titles, buildings or final development outcomes can be achieved.
In simple terms
Operational Works helps answer questions such as:
What physical works are required for the project?
What infrastructure needs to be constructed?
Are engineering approvals required?
What civil works standards apply?
What construction costs may be involved?
When can development physically commence?
Operational Works may include:
road construction,
stormwater drainage,
water and sewer infrastructure,
earthworks and retaining walls,
driveways and access works,
electrical and utility connections,
landscaping,
and civil infrastructure upgrades.
Why Operational Works Matter
Operational Works may help:
deliver essential infrastructure,
prepare land for development,
support subdivision approvals,
improve servicing capacity,
ensure compliance with engineering standards,
and allow projects to progress toward completion.
For developers and landowners, Operational Works can become one of the largest and most complex stages of a development project.
Some projects may appear financially viable until civil construction and infrastructure costs are properly assessed.
Operational Works and Property Strategy
Operational Works are commonly associated with:
subdivisions,
residential estates,
townhouse developments,
commercial projects,
industrial developments,
mixed-use projects,
and infrastructure upgrades.
These works are usually undertaken after Development Approval and often require detailed engineering plans and separate approvals before construction begins.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before proceeding with Operational Works, it is important to understand:
engineering requirements,
infrastructure standards,
stormwater management,
site conditions,
construction costs,
environmental impacts,
staging requirements,
and project timeframes.
Unexpected ground conditions, service upgrades or civil construction costs can significantly affect project feasibility and profitability.
Property decisions should be made with strategy, not panic.
Key Insight
Operational Works are not simply “construction works.”
They are the critical infrastructure and civil construction stage that transforms an approved concept into a physically functional development project.
Understanding your position is the first step.


Property Development
Overlay
An overlay is a planning control used by councils to identify specific conditions, risks or characteristics that may affect how land can be used or developed.
Overlays sit on top of the underlying zoning and may introduce additional rules, restrictions or assessment requirements for a property.
In simple terms
An overlay helps answer questions such as:
Are there special planning controls affecting the land?
Does the property carry environmental or flood risk?
Are there development restrictions or extra requirements?
Will additional approvals or reports be required?
Could overlays affect property value or development potential?
What risks need to be considered before purchasing or developing?
Overlays may relate to:
flood risk,
bushfire risk,
environmental protection,
heritage controls,
biodiversity areas,
landslide or erosion risk,
airport noise corridors,
infrastructure corridors,
and neighbourhood character protections.
Why Overlays Matter
Overlays may help:
manage environmental and safety risks,
guide appropriate development,
protect community infrastructure,
preserve important environmental or heritage areas,
and improve long-term planning outcomes.
For property owners and developers, overlays can significantly affect what may or may not be achievable on a site.
Some properties may appear highly developable until overlay constraints are properly investigated.
Overlays and Property Strategy
Overlays are commonly considered for:
subdivisions,
infill developments,
acreage projects,
residential developments,
commercial projects,
industrial developments,
and strategic landholdings.
These controls are usually reviewed during feasibility studies, due diligence investigations and town planning assessments before proceeding with a project.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before proceeding with a property or development project, it is important to understand:
applicable overlays,
approval requirements,
engineering or environmental reports,
building restrictions,
infrastructure impacts,
insurance implications,
construction costs,
and realistic development potential.
Not all overlays are “deal breakers,” but they can significantly affect risk, cost, approval timeframes and project feasibility.
Property decisions should be made with strategy, not panic.
Key Insight
An overlay is not simply a line on a council planning map.
It is a strategic planning tool used to identify risks, constraints and additional considerations that may affect how land can be used, developed and protected over time.
Understanding your position is the first step.


Property Development
Planning Scheme
A planning scheme is the set of rules and policies used by a council to guide how land can be used and developed within a region.
It controls zoning, overlays, development standards and assessment requirements to help manage future growth, infrastructure and community outcomes.
In simple terms
A planning scheme helps answer questions such as:
What can legally be built on the land?
What zoning applies to the property?
Are there overlays or restrictions affecting development?
What approvals are required?
Can the land be subdivided or redeveloped?
What development standards apply?
A planning scheme may regulate:
zoning,
land use,
building height,
density,
setbacks,
infrastructure requirements,
environmental protections,
and development assessment processes.
Why Planning Schemes Matter
Planning schemes may help:
manage population growth,
guide future development,
protect environmental and community interests,
coordinate infrastructure delivery,
improve land use planning,
and provide consistency for development assessment.
For property owners and developers, the planning scheme can significantly affect land value, development potential and approval risk.
Some properties may carry far more opportunity — or more limitations — than many owners realise.
Planning Schemes and Property Strategy
Planning schemes are commonly considered for:
subdivisions,
infill developments,
townhouse projects,
mixed-use developments,
commercial developments,
industrial land,
and strategic landholdings.
These rules are usually reviewed during feasibility studies, due diligence investigations and town planning assessments before proceeding with a project.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before purchasing or developing property, it is important to understand:
zoning and overlays,
permitted land uses,
development constraints,
infrastructure requirements,
approval pathways,
environmental considerations,
neighbourhood character controls,
and realistic development potential.
Planning schemes can change over time, and future amendments may affect what can be achieved on a property.
Property decisions should be made with strategy, not panic.
Key Insight
A planning scheme is not simply a collection of council rules.
It is the strategic framework used to shape how cities, suburbs and communities grow, develop and function over time.
Understanding your position is the first step.


Property Development
Reconfiguration of a Lot (ROL)
A Reconfiguration of a Lot (ROL) refers to changing the boundaries, size or arrangement of land parcels through subdivision or other land boundary adjustments.
ROL approvals are commonly required when land is being divided into multiple lots, combined together, or reconfigured for future development purposes.
In simple terms
A Reconfiguration of a Lot helps answer questions such as:
Can the land be subdivided?
How many lots may be created?
Does the property meet minimum lot size requirements?
What infrastructure or access is required?
Will council approval be needed?
Is the subdivision financially viable?
An ROL may involve:
residential subdivisions,
boundary realignments,
amalgamating lots,
creating access easements,
rural subdivisions,
development staging,
and community title arrangements.
Why Reconfiguration of a Lot Matters
ROL approvals may help:
unlock additional land value,
create development opportunities,
increase housing supply,
improve land usability,
support future development,
and allow strategic land planning.
For some property owners, the ability to subdivide or reconfigure land may significantly increase the overall value of the site.
Some properties may carry hidden subdivision potential that is not immediately obvious.
ROL and Property Strategy
Reconfiguration of a Lot is commonly associated with:
infill developments,
greenfield subdivisions,
townhouse projects,
acreage developments,
emerging community land,
strategic landholdings,
and development feasibility assessments.
These projects are usually reviewed through planning investigations, engineering assessments and feasibility studies before proceeding.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before proceeding with an ROL application, it is important to understand:
zoning and overlays,
minimum lot sizes,
access and frontage requirements,
infrastructure servicing,
stormwater management,
approval pathways,
infrastructure charges,
and realistic end values.
Subdivision projects can involve significant engineering, infrastructure and holding costs that may affect overall project profitability.
Property decisions should be made with strategy, not panic.
Key Insight
A Reconfiguration of a Lot is not simply “splitting land.”
It is a strategic planning and development process used to reshape land boundaries, unlock development potential and create future opportunities through subdivision and land reorganisation.
Understanding your position is the first step.


Property Development
Residential A
Residential A is a zoning classification used in some planning schemes to identify land intended primarily for low-density residential living.
This zoning is generally designed to support detached housing and traditional suburban neighbourhoods while controlling development intensity and preserving residential character.
In simple terms
Residential A zoning helps answer questions such as:
What type of housing can be built on the land?
Is the property suitable for subdivision?
What density restrictions apply?
Can higher-density development occur?
What planning controls affect the site?
What future development potential may exist?
Residential A areas commonly include:
detached houses,
owner-occupier housing,
family residential neighbourhoods,
low-density subdivisions,
and established suburban housing areas.
Why Residential A Matters
Residential A zoning may help:
protect neighbourhood character,
manage housing density,
support family residential living,
maintain suburban amenity,
guide future growth,
and provide certainty around land use expectations.
For property owners and developers, the zoning can significantly affect subdivision potential, redevelopment opportunities and overall land value.
Some properties within Residential A zones may still carry strategic upside depending on lot size, frontage, overlays and future planning changes.
Residential A and Property Strategy
Residential A zoning is commonly associated with:
established residential suburbs,
family housing areas,
low-density developments,
infill opportunities,
subdivision investigations,
and long-term residential landholdings.
These properties are often reviewed through planning investigations, overlay analysis and feasibility studies before redevelopment or subdivision is considered.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before purchasing or developing Residential A land, it is important to understand:
minimum lot sizes,
subdivision potential,
overlays and planning constraints,
access and frontage requirements,
infrastructure availability,
neighbourhood character controls,
approval pathways,
and realistic end values.
Not all Residential A land carries the same development potential, and some sites may have significant limitations depending on overlays, shape, access or servicing.
Property decisions should be made with strategy, not panic.
Key Insight
Residential A zoning is not simply “standard residential land.”
It is a strategic planning classification designed to guide low-density residential growth, protect neighbourhood character and manage how suburban communities develop over time.
Understanding your position is the first step.


Property Development
Setback
A setback refers to the minimum required distance between a building or structure and a property boundary.
Setback rules are controlled through planning schemes and building regulations to manage spacing, privacy, access, streetscape appearance and overall neighbourhood character.
In simple terms
A setback helps answer questions such as:
How close can a building be to the boundary?
What building envelope applies to the site?
Will the design comply with council requirements?
How much usable building area exists?
Could setbacks affect subdivision or redevelopment potential?
Are there different setbacks for front, side or rear boundaries?
Setbacks commonly apply to:
houses,
garages,
sheds,
townhouses,
unit developments,
commercial buildings,
and other structures.
Why Setbacks Matter
Setbacks may help:
maintain neighbourhood character,
improve privacy,
allow access around buildings,
manage overshadowing,
improve ventilation and light,
and support safer, more functional development outcomes.
For developers and property owners, setback requirements can significantly affect building design, site yield and development potential.
Some sites may appear large enough for development until setback requirements reduce the usable building area.
Setbacks and Property Strategy
Setbacks are commonly considered for:
new home construction,
subdivisions,
townhouse developments,
unit projects,
renovations and extensions,
commercial developments,
and redevelopment sites.
These requirements are usually reviewed during planning investigations, building design and feasibility assessments before construction begins.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before proceeding with a project, it is important to understand:
front, side and rear setback requirements,
zoning and overlays,
building height restrictions,
site coverage limits,
easements and access requirements,
neighbourhood character provisions,
approval pathways,
and realistic building envelopes.
Different zoning areas and planning schemes may carry different setback rules depending on the intended land use and development type.
Property decisions should be made with strategy, not panic.
Key Insight
A setback is not simply “empty space around a building.”
It is a strategic planning and design control used to shape streetscapes, protect amenity and manage how buildings interact with surrounding properties and public areas.
Understanding your position is the first step.


Property Development
Site Coverage
Site coverage refers to the percentage of a property’s land area that is occupied by buildings or roofed structures.
Planning schemes and building regulations often use site coverage controls to manage density, open space, drainage, privacy and neighbourhood character.
In simple terms
Site coverage helps answer questions such as:
How much of the land can be built on?
Is there enough open space remaining?
Will the development comply with council requirements?
Could site coverage limit future extensions or redevelopment?
How does the building footprint affect the property?
Are there maximum coverage limits for the zoning?
Site coverage calculations may include:
houses,
garages,
sheds,
patios,
roofed outdoor areas,
commercial buildings,
and other covered structures.
Why Site Coverage Matters
Site coverage controls may help:
prevent overdevelopment,
maintain neighbourhood character,
improve drainage and stormwater management,
preserve private open space,
improve ventilation and sunlight access,
and create more functional living environments.
For developers and property owners, site coverage requirements can significantly affect design flexibility, subdivision potential and development yield.
Some sites may appear large enough for redevelopment until site coverage limits reduce the achievable building footprint.
Site Coverage and Property Strategy
Site coverage is commonly considered for:
new home construction,
renovations and extensions,
subdivisions,
townhouse developments,
unit projects,
mixed-use developments,
and commercial developments.
These controls are usually reviewed during planning investigations, feasibility studies and building design stages before construction begins.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before proceeding with a project, it is important to understand:
maximum site coverage limits,
zoning and overlays,
setbacks and building envelopes,
open space requirements,
stormwater management,
building height restrictions,
approval pathways,
and realistic development potential.
Different planning schemes and zoning areas may carry different site coverage requirements depending on the intended land use and development type.
Property decisions should be made with strategy, not panic.
Key Insight
Site coverage is not simply “how much building fits on the land.”
It is a strategic planning control used to balance development intensity, open space, drainage, amenity and long-term neighbourhood functionality.
Understanding your position is the first step.


Property Development
Stormwater
Stormwater refers to rainwater runoff that flows across land, roads, roofs and hard surfaces during rainfall events.
In property development and construction, stormwater management is used to control how water is collected, directed, stored and discharged to reduce flooding, erosion and infrastructure damage.
In simple terms
Stormwater helps answer questions such as:
Where does rainwater flow on the site?
Will the development increase runoff or flooding risk?
How will water be drained safely?
Are detention or drainage systems required?
Could stormwater affect approvals or construction costs?
Will neighbouring properties be impacted?
Stormwater systems may include:
drainage pipes,
pits and grates,
swales,
detention basins,
retention systems,
kerb and channel infrastructure,
on-site drainage,
and overland flow paths.
Why Stormwater Matters
Stormwater management may help:
reduce flooding risk,
protect buildings and infrastructure,
prevent erosion,
improve public safety,
protect neighbouring properties,
and support sustainable development outcomes.
For developers and property owners, stormwater requirements can significantly affect site design, engineering costs and development feasibility.
Some sites may appear suitable for development until drainage constraints or overland flow issues are properly investigated.
Stormwater and Property Strategy
Stormwater considerations are commonly associated with:
subdivisions,
townhouse developments,
infill projects,
commercial developments,
industrial developments,
flood-prone land,
and civil infrastructure works.
Stormwater management is usually reviewed during engineering assessments, feasibility studies and development approval processes before construction begins.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before proceeding with a project, it is important to understand:
flood overlays and overland flow,
drainage capacity,
site levels and topography,
council engineering requirements,
detention and retention requirements,
neighbouring property impacts,
infrastructure costs,
and long-term maintenance obligations.
Stormwater problems can create major approval delays, unexpected costs and long-term property risks if not properly addressed early in the process.
Property decisions should be made with strategy, not panic.
Key Insight
Stormwater is not simply “where the water goes.”
It is a critical engineering and planning consideration used to manage runoff, reduce flood risk and protect both development projects and surrounding communities.
Understanding your position is the first step.


Property Development
Site Coverage
Site coverage refers to the percentage of a property’s land area that is occupied by buildings or roofed structures.
Planning schemes and building regulations often use site coverage controls to manage density, open space, drainage, privacy and neighbourhood character.
In simple terms
Site coverage helps answer questions such as:
How much of the land can be built on?
Is there enough open space remaining?
Will the development comply with council requirements?
Could site coverage limit future extensions or redevelopment?
How does the building footprint affect the property?
Are there maximum coverage limits for the zoning?
Site coverage calculations may include:
houses,
garages,
sheds,
patios,
roofed outdoor areas,
commercial buildings,
and other covered structures.
Why Site Coverage Matters
Site coverage controls may help:
prevent overdevelopment,
maintain neighbourhood character,
improve drainage and stormwater management,
preserve private open space,
improve ventilation and sunlight access,
and create more functional living environments.
For developers and property owners, site coverage requirements can significantly affect design flexibility, subdivision potential and development yield.
Some sites may appear large enough for redevelopment until site coverage limits reduce the achievable building footprint.
Site Coverage and Property Strategy
Site coverage is commonly considered for:
new home construction,
renovations and extensions,
subdivisions,
townhouse developments,
unit projects,
mixed-use developments,
and commercial developments.
These controls are usually reviewed during planning investigations, feasibility studies and building design stages before construction begins.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before proceeding with a project, it is important to understand:
maximum site coverage limits,
zoning and overlays,
setbacks and building envelopes,
open space requirements,
stormwater management,
building height restrictions,
approval pathways,
and realistic development potential.
Different planning schemes and zoning areas may carry different site coverage requirements depending on the intended land use and development type.
Property decisions should be made with strategy, not panic.
Key Insight
Site coverage is not simply “how much building fits on the land.”
It is a strategic planning control used to balance development intensity, open space, drainage, amenity and long-term neighbourhood functionality.
Understanding your position is the first step.
Property Development
Strategic Landholding
A strategic landholding refers to land that is held primarily because of its future potential rather than its current use.
These properties are often positioned in areas expected to benefit from future growth, rezoning, infrastructure investment, population expansion or long-term development demand.
In simple terms
A strategic landholding helps answer questions such as:
Could the land become more valuable in the future?
Is the area expected to grow or change?
Could rezoning unlock additional value?
Is infrastructure planned nearby?
Does the property have future subdivision or development potential?
Is the long-term opportunity worth the holding costs and risk?
Strategic landholdings may include:
emerging community land,
greenfield sites,
infill sites,
rural land near urban expansion,
transport corridor properties,
large development parcels,
and land near future infrastructure projects.
Why Strategic Landholdings Matter
Strategic landholdings may help:
create long-term capital growth,
secure future development opportunities,
benefit from planning changes,
position owners ahead of infrastructure delivery,
and unlock significant long-term land value.
For some investors and landowners, the greatest value of a property may come from future positioning rather than immediate income generation.
Some land may appear underutilised today but hold major long-term strategic upside.
Strategic Landholdings and Property Strategy
Strategic landholdings are commonly associated with:
land banking,
future residential estates,
mixed-use precincts,
subdivision opportunities,
industrial growth corridors,
infrastructure expansion areas,
and long-term development planning.
These opportunities are often assessed through feasibility studies, town planning investigations and growth forecasting before acquisition or development decisions are made.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before proceeding with a strategic landholding strategy, it is important to understand:
zoning and overlays,
future planning intentions,
infrastructure timing,
holding costs,
finance requirements,
environmental constraints,
development risks,
and realistic long-term demand.
Strategic landholding opportunities can involve long timeframes and there is never a guarantee that future planning changes or development outcomes will occur.
Property decisions should be made with strategy, not panic.
Key Insight
A strategic landholding is not simply “holding land and waiting.”
It is a long-term positioning strategy focused on securing land in areas that may benefit from future growth, infrastructure, planning changes and evolving market demand over time.
Understanding your position is the first step.


Property Development
Subdivision
A subdivision is the process of dividing one parcel of land into two or more separate lots.
Subdivision is one of the most common forms of property development and is often used to unlock additional land value, create new housing opportunities or prepare land for future development.
In simple terms
A subdivision helps answer questions such as:
Can the land be split into multiple lots?
How many lots may be achievable?
What approvals are required?
Will the project be financially viable?
What infrastructure upgrades may be needed?
Could the subdivision increase the property’s overall value?
Subdivision projects may involve:
residential lot creation,
acreage subdivisions,
infill developments,
staged residential estates,
boundary realignments,
community title developments,
and future development land releases.
Why Subdivision Matters
Subdivision may help:
unlock hidden land value,
create additional saleable lots,
increase housing supply,
improve land efficiency,
support future population growth,
and create long-term development opportunities.
For many property owners, the land itself may carry more value than the existing dwelling sitting on it.
Some sites may appear like ordinary homes until subdivision potential is properly assessed.
Subdivision and Property Strategy
Subdivision projects are commonly associated with:
infill development,
greenfield development,
strategic landholdings,
emerging community land,
townhouse projects,
medium density opportunities,
and long-term growth corridors.
These projects are usually assessed through feasibility studies, town planning investigations and engineering reviews before proceeding.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before proceeding with a subdivision project, it is important to understand:
zoning and overlays,
minimum lot size requirements,
frontage and access requirements,
stormwater and infrastructure servicing,
headworks and infrastructure charges,
engineering and civil construction costs,
approval pathways,
and realistic end values.
Subdivision projects can involve significant timeframes, holding costs and approval risks that may affect overall profitability.
Property decisions should be made with strategy, not panic.
Key Insight
Subdivision is not simply “splitting land.”
It is a strategic planning and development process used to reshape land, create additional value and unlock future opportunities through careful planning, approvals and infrastructure delivery.
Understanding your position is the first step.


Property Development
Town Planning
Town planning is the process of managing how land is used and developed to guide the growth, function and future of communities.
It involves balancing housing, infrastructure, environment, transport, business activity and public spaces to create organised and sustainable development outcomes.
In simple terms
Town planning helps answer questions such as:
What can be built on the land?
Is the proposed development permitted?
What approvals are required?
Are there zoning or overlay constraints?
Will infrastructure support the project?
How could future planning changes affect the property?
Town planning may involve:
zoning controls,
development applications,
subdivision design,
infrastructure planning,
environmental considerations,
transport networks,
population growth management,
and community planning.
Why Town Planning Matters
Town planning may help:
guide future growth,
manage development impacts,
protect community amenity,
coordinate infrastructure delivery,
improve land efficiency,
and create more functional and sustainable communities.
For property owners and developers, town planning can significantly affect land value, approval pathways and long-term development potential.
Some properties may carry hidden opportunities — or major limitations — depending on planning controls and future growth strategies.
Town Planning and Property Strategy
Town planning is commonly associated with:
subdivisions,
infill developments,
medium density projects,
mixed-use developments,
commercial developments,
industrial projects,
strategic landholdings,
and urban growth areas.
These opportunities are usually reviewed through feasibility studies, planning investigations and consultant advice before major decisions are made.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before proceeding with a project, it is important to understand:
zoning and overlays,
planning scheme requirements,
approval pathways,
infrastructure availability,
environmental constraints,
development contributions,
community impacts,
and realistic project feasibility.
Town planning outcomes can change over time as councils update planning schemes, infrastructure priorities and future growth strategies.
Property decisions should be made with strategy, not panic.
Key Insight
Town planning is not simply “council paperwork.”
It is the strategic framework used to shape how communities grow, how land is used and where future opportunity may be created over time.
Understanding your position is the first step.


Property Development
Yield Analysis
Yield analysis is the process of assessing the income return a property or development may generate compared to its value, purchase price or total project cost.
It is commonly used by investors, developers and lenders to evaluate whether a property investment or project is financially worthwhile.
In simple terms
Yield analysis helps answer questions such as:
How much income could the property generate?
Is the return strong enough for the risk involved?
How does the property compare to other investments?
Will rental income support holding costs?
Could the project deliver acceptable returns?
Is the property more suited for growth or income?
Yield analysis may assess:
rental income,
purchase price,
development costs,
operating expenses,
vacancy risk,
holding costs,
net returns,
and market conditions.
Why Yield Analysis Matters
Yield analysis may help:
assess investment performance,
compare different property opportunities,
identify cash flow potential,
support lending and finance decisions,
improve feasibility assessments,
and guide long-term investment strategy.
A property with strong capital growth potential may still produce weak rental returns, while high-yield properties may carry different risks or growth profiles.
Good investors assess both income and long-term positioning — not just headline numbers.
Yield Analysis and Property Strategy
Yield analysis is commonly associated with:
residential investment properties,
commercial property,
industrial property,
mixed-use developments,
build-to-rent projects,
subdivisions,
and strategic land acquisitions.
It is often reviewed during feasibility studies, due diligence investigations and acquisition assessments before proceeding with a project or purchase.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before relying on yield analysis, it is important to understand:
gross vs net yield,
vacancy rates,
maintenance and operating costs,
property management expenses,
finance costs,
market demand,
tenant quality,
and long-term growth potential.
Higher yield does not always mean lower risk, and some properties with lower initial yield may offer stronger long-term growth opportunities.
Property decisions should be made with strategy, not panic.
Key Insight
Yield analysis is not simply “working out rental income.”
It is a strategic financial assessment used to measure income performance, compare opportunities and evaluate whether a property or project aligns with the investor’s goals, risk profile and long-term strategy.
Understanding your position is the first step.


Property Development
Zoning
Zoning is the system councils use to control how land can be used and developed within a particular area.
Every property is allocated a zoning classification that helps determine what activities, buildings and development types may be permitted on the land.
In simple terms
Zoning helps answer questions such as:
What can legally be built on the property?
Is the land residential, commercial, industrial or rural?
Can the property be subdivided or redeveloped?
Are there restrictions on density or building type?
Could the zoning affect property value?
Is there future development potential?
Common zoning categories may include:
residential,
medium density,
commercial,
industrial,
rural,
mixed use,
emerging community,
and environmental management zones.
Why Zoning Matters
Zoning may help:
guide future growth,
separate incompatible land uses,
protect neighbourhood character,
manage infrastructure demand,
improve development outcomes,
and create long-term planning certainty.
For property owners and developers, zoning can significantly affect land value, subdivision potential, development opportunities and approval risk.
Some properties may hold far greater value because of their zoning position rather than the existing improvements on the land.
Zoning and Property Strategy
Zoning is commonly considered for:
subdivisions,
infill developments,
townhouse projects,
commercial developments,
industrial developments,
mixed-use projects,
strategic landholdings,
and redevelopment opportunities.
These opportunities are often assessed through feasibility studies, planning investigations and consultant advice before major decisions are made.
Bundaberg is not one market. Different suburbs are behaving like different products.
Things To Consider
Before purchasing or developing property, it is important to understand:
current zoning,
permitted land uses,
overlays and planning constraints,
density controls,
infrastructure availability,
approval pathways,
future planning intentions,
and realistic development potential.
Zoning can change over time through planning scheme amendments, infrastructure expansion and council growth strategies.
Property decisions should be made with strategy, not panic.
Key Insight
Zoning is not simply a colour on a planning map.
It is a strategic planning framework used to guide how land is used, how communities grow and where future development opportunities may exist over time.
Understanding your position is the first step.

